Why KTC’s Black Friday Blitz Signals the Death of the Monitor Premium Business

Why KTC’s Black Friday Blitz Signals the Death of the Monitor Premium

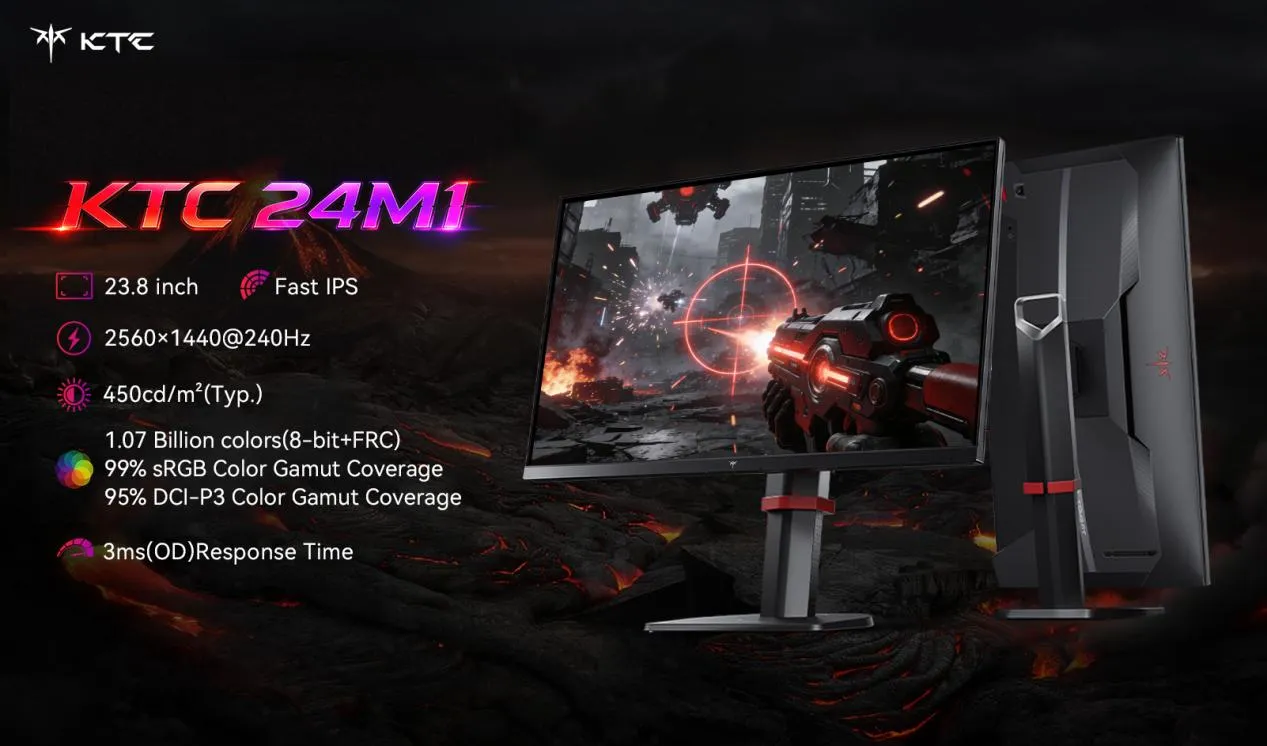
(SeaPRwire) - Stop pretending high refresh rate gaming displays are luxury items. The days of paying $300 for a 144Hz panel are over. KTC just hammered that point home with a 30% discount on its H27E6S. We are seeing a brutal price floor form in Europe. The H27E6S drops to £101.49 in the UK. That is less than the cost of a decent pair of headphones. The 24M1 follows suit at £118.99. This is not a discount. It is a statement. The market for "value" monitors has swallowed the middle tier. If you are still paying more, you are buying a brand logo. The hardware is identical. The spec sheet is dense with red flags for traditionalists. Both monitors use Fast IPS panels. The H27E6S is a 27-inch 240Hz unit. It supports overclocking to 275Hz. The 24M1 is smaller at 23.8 inches. But it packs 123 PPI. That is sharpness reserved for 4K screens. Both handle QHD 2560x1440 resolution. Response times sit at 3ms GtG. Motion blur reduction is included. Color gamut covers 95% DCI-P3. Delta E is under 2. These are factory-calibrated figures. You get HDR 400 certification. The 24M1 peaks at 450 nits. The H27E6S hits 400 nits. These numbers usually appear on displays costing twice as much. The commercial loop is clear. KTC leverages thirty-one years of manufacturing expertise. They skip the middleman markup. Direct-to-consumer Amazon codes drive the margin down. In Germany, the H27E6S costs €167.99. In France, it is €153.89. The 24M1 hovers around €188.79 in Germany. These prices undercut Samsung and LG significantly. The end game is consolidation. Brand loyalty is the only thing left. Performance per euro is the new king. If your GPU cannot push 240 frames at 1440p, this discount does nothing for you. But if it does, the barrier to entry has vanished. The industry has bottomed out.
More
从里约狂欢到全球战场:捷途粉丝节的真实商业意图是什么? Business

从里约狂欢到全球战场:捷途粉丝节的真实商业意图是什么?

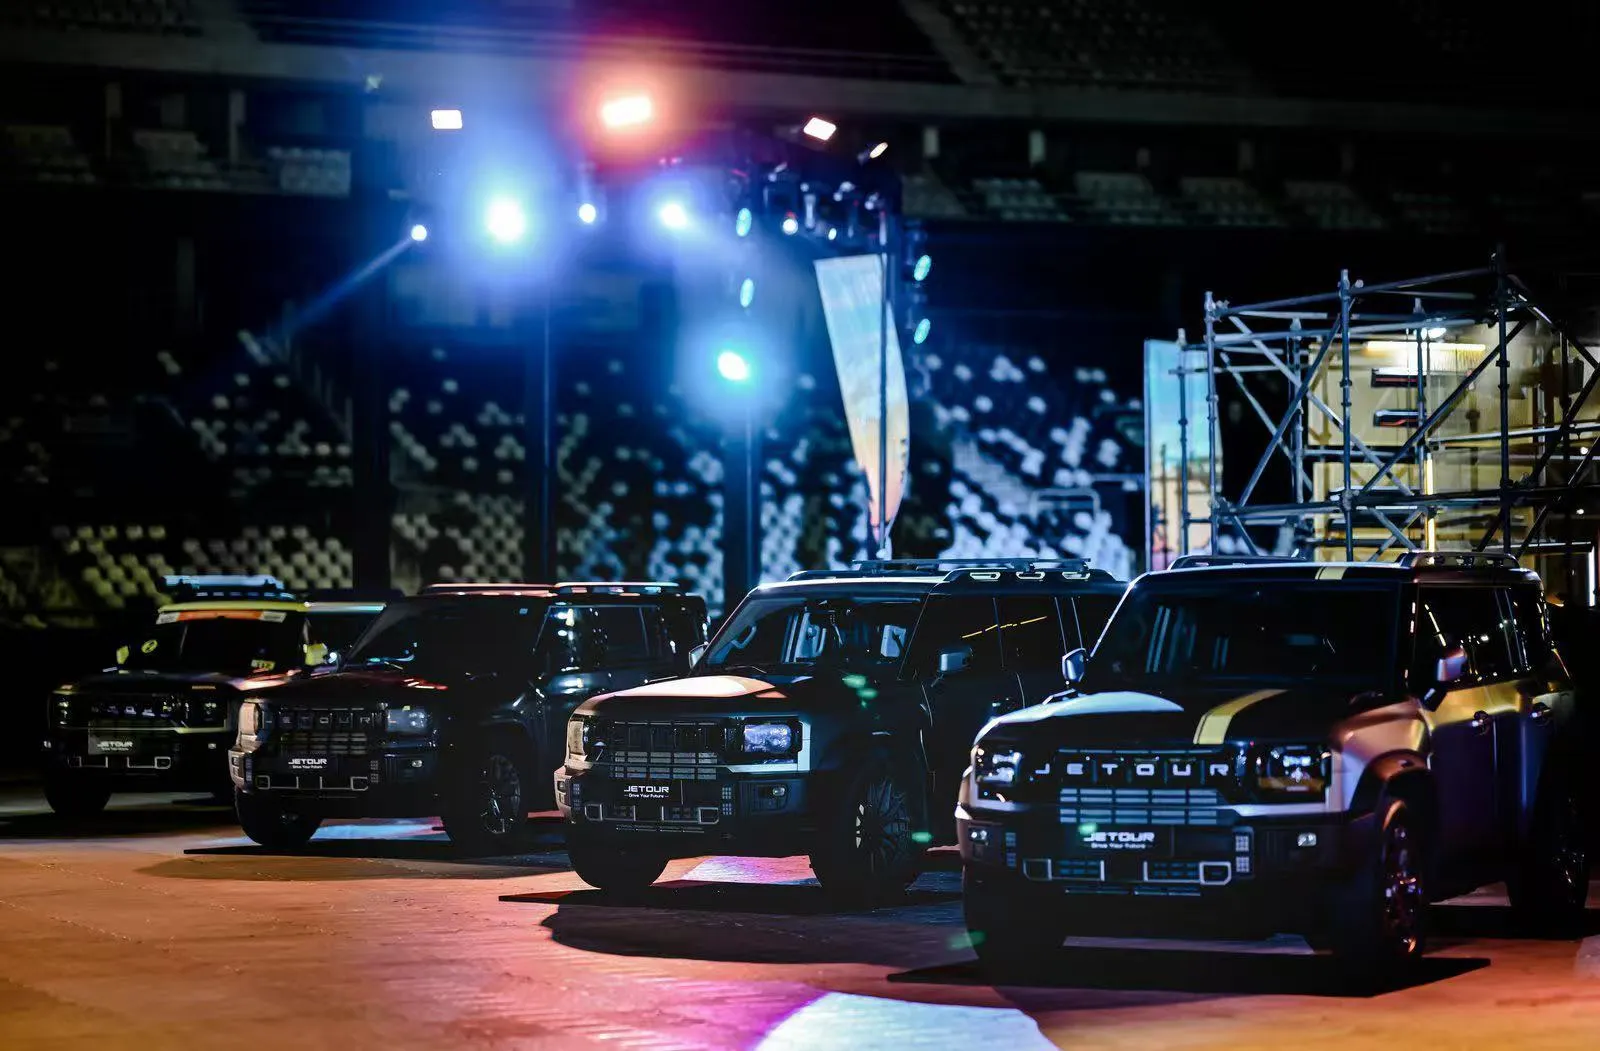
(SeaPRwire) - 一场在里约热内卢举办的粉丝节,真的只是一场派对吗?2026年11月18日至19日,捷途在巴西举办的全球粉丝节,表面上是车主和媒体的狂欢,实际上更像一次精心设计的市场试探。当改装车列队穿过里约街头时,捷途真正想测试的,是南美市场对中国硬派SUV品牌的反响。这个问题的答案,将决定捷途未来几年的全球扩张速度。 捷途把活动安排在巴西并非偶然。这是其进入巴西市场后的首次全球车主活动。官方宣称的重点是"多样化产品线",包括T1、T2和G700。T系列主打城市通勤与户外探索的平衡,G700则瞄准豪华越野市场。技术层面上,T系列的XWD全自动智能四驱系统采用地形识别与智能动力分配,G700基于GAIA全地形智能架构,混动系统配合专业越野装备。这些技术细节被包装成体验,但本质上,捷途在用产品力教育潜在消费者——这是一家能造硬核越野车的品牌。 数据层面,捷途的"Travel+"战略正在构建一套用户生态。捷途CLUB已拥有300多个车主俱乐部,覆盖30多个国家和地区,核心成员超过3万名。巴西粉丝节将这套体系第一次带到南美。对当地车主而言,这是身份认同的建立;对捷途而言,这是在陌生市场搭建情感纽带。值得注意的是,这些数字背后隐藏着商业逻辑:车主俱乐部是复购率与口碑传播的基石,而南美正是SUV增长潜力巨大的区域。 竞争格局正在变化。巴西市场长期被日系和德系品牌主导,但中国品牌正在凭借差异化产品切入。捷途选择"旅行+"而非单纯性能竞赛,是一种差异化策略。T系列与G系列的分工,覆盖了从家庭出行到硬核越野的不同需求层次。混动技术的引入,则是对当地燃油经济性需求的回应。这场粉丝节的试驾环节——沙地、泥地、陡坡——其实是在展示产品的可靠性,以此对抗市场对"中国制造"的固有疑虑。 供应链层面,巴西本地改装车主的参与值得深思。活动展示了当地车主自己改装的车辆,这不仅是用户共创,更意味着捷途正在培育本地改装生态。改装文化是越野车市场的高附加值环节,也是品牌忠诚度的催化剂。捷途让当地车主参与改装展示,实际上是在为本地化生产或深度合作埋下伏笔。当用户愿意为品牌付出额外改装成本时,品牌溢价才真正形成。 捷途的这一步棋,不是简单的品牌营销,而是一场针对南美市场的长期渗透。粉丝节只是序幕,真正的考验在于后续能否将活动带来的好感转化为持续销量。
More
QIDI’s Black Friday Playbook: Why Family 3D Printers Just Got Serious About Margins Business

QIDI’s Black Friday Playbook: Why Family 3D Printers Just Got Serious About Margins

(SeaPRwire) - QIDI is betting that your kitchen table is the next competitive battleground for 3D printing. The Shenzhen-based maker just dropped its Black Friday sale with savings topping $300 on select machines, plus another $50 off orders over $1,000. But look past the discount numbers and you'll see something more calculated: QIDI is reshuffling its entire lineup strategy in one promotional push. The question isn't whether these deals are good value. It's what category QIDI is trying to own. The press release lists five machines, each occupying a deliberate position. The MakeBuddy Smart5 targets children and beginners with AI-powered Image-to-3D conversion, a library of over 1,000 models, STEAM courses, an air filtration system, and flame-retardant chamber design. The QIDI Q2 claims the entry-level throne with remote slicing, mobile app control, AI camera monitoring, multi-color capability, and carbon-fiber composite support all wrapped in a beginner-friendly package. The PLUS5 moves upmarket with a 320 × 320 × 300 mm build volume, nozzle-contact auto-leveling, and a third-generation active chamber heating system holding 65°C with 550W output. The MAX4 pushes further still at 390 × 390 × 340 mm with a 40 mm³/s high-flow hotend, hardened steel nozzle, and Polar Cooler active toolhead cooling paired with second-generation chamber heating. Then there's the QIDI Q3D, announced at Formnext 2026, a next-generation dual-nozzle system now available for pre-order that supports dedicated support materials and lightweight toolhead design for stability during multi-material runs. What's striking is how QIDI is threading two markets simultaneously. The Smart5 rebrands 3D printing as a safe, educational family device — filtered air, child-oriented learning paths, AI-assisted modeling that turns a single photo into a printable object. That's a different buyer than the PLUS5 or MAX4 customer chasing industrial-grade ABS, PC, and carbon-fiber nylon output at scale. Selling both under one brand at one sale is a play to own the entire household-to-workshop pipeline. The accessory and filament discount tiers reinforce it — once that first machine is sitting on someone's desk, the recurring revenue kicks in. QIDI's pricing architecture tells you who they're courting next: parents with kids, small workshop operators, and hobbyists upgrading from entry-level. The installed base becomes the margin engine.
More
Why DIVEVOLK’s “Best Deal” Is Actually Your Most Expensive Choice—and What the Discounts Really Reveal About Underwater Smartphone Photography Business

Why DIVEVOLK’s “Best Deal” Is Actually Your Most Expensive Choice—and What the Discounts Really Reveal About Underwater Smartphone Photography

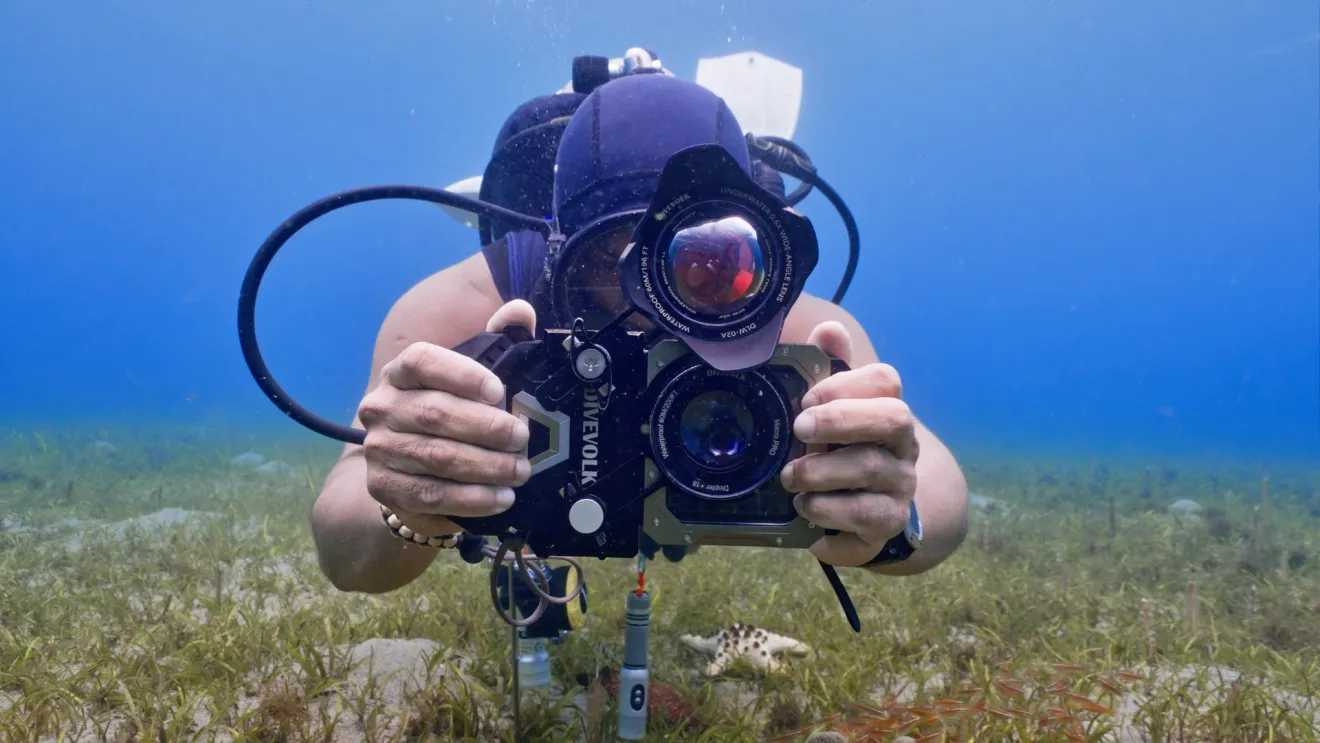
(SeaPRwire) - DIVEVOLK's Black Friday sale lands at a strange moment for anyone who actually follows underwater imaging. The company is pushing smartphone housings—the cheapest segment of the pro dive-camera market—into a promotional cycle that rewards bigger spending. Up to 27 percent sounds aggressive until you realize it's attached to the entry-tier housing only. That's not generosity. That's funnel design. The official numbers are straightforward. Between November 20 and December 1, 2026, the SeaTouch 4 Max Plus housing runs 27 percent off when bundled with a free Pink or Blue camo protective cover. The SeaTouch 4 Max Plus kits sit at 20 percent off. All accessories—lenses, filters, lights, trays—are 20 percent off. The SeaLink transmitter shares that same 20 percent rate. The SeaTouch 6 Pro takes a softer cut: 12 percent on the base kit, 15 percent on dual-lens or single-light configurations, and 18 percent on dual-light kits. There's a deliberate asymmetry here. The deeper you go into the kit stack, the better your percentage gets—but so does your absolute spend. The press release itself confirms this gap by noting that 6 Pro discounts apply to kits only, not the bare housing. DIVEVOLK isn't hiding that. It's the entire point. Let's look at what you're actually buying beneath the percentages. The SeaTouch 4 Max Plus seals phones up to 180 × 82.5 × 11.2 mm with a camera module no thicker than 15 mm, rated to 60 meters. Its touchscreen membrane supports native apps and third-party camera tools without converting your phone into a brick once sealed. The protective cover in Pink or Blue camo shields both the membrane and lens glass between dives—a genuinely useful addition, not window dressing. The four 4 Max Plus kits each map to a shooting discipline. Ocean Kit pairs a 0.6X wide-angle lens with a 67 mm red filter for reef and large-animal work. Macro Kit adds a +8 lens for nudibranchs and shrimp. Creator Kit mounts a single SL20 or SL50 video light on a handle tray with an external shutter for single-light video. Deep Dive and Almighty kits move to dual lights for full-color footage at depth. The SeaTouch 6 Pro, launched in 2026, raises the ceiling significantly. Its sixth-generation membrane carries a 150,000-touch rating and a wider touch window designed so swiping up to return home still registers even on the largest current flagships. The housing accepts phones up to 17 mm thick at the camera module—two millimeters more clearance than the 4 Max Plus—which matters as telephoto bumpers keep growing. Construction uses engineering plastic reinforced with an aluminum-alloy frame and 316 stainless steel. A dedicated desiccant slot and a pre-tuned red filter for 0 to 10 meters ship inside every unit. The kit ladder mirrors the 4 Max Plus logic but targets a different diver. The Dual Lens Kit pairs the 0.6X wide-angle with the Macro Lens Pro +18, collapsing two separate purchases into one rig. The Creator Kit steps up to an SL20, SL50, or SL120 light with the external shutter built in. The Deep Dive Dual Light Kit mounts two SL50 or SL120 units on a dual-handle tray for even illumination where ambient color has already fallen away. Here's the structural insight most buyers miss. DIVEVOLK's discount curve penalizes single-component shopping and rewards complete-system commitment. Buy the 6 Pro housing alone and you get zero percent off under the advertised range. Buy the same housing inside a dual-light kit and you unlock 18 percent—the same effective margin offered on the entry-level 4 Max Plus bare housing. That inverted arithmetic exists because the cost of goods along the kit boundary is far denser than the cost of the housing plus a late-add lens. The accessory margin subsidizes the hardware discount. It's standard consumer-electronics playwriting, executed cleanly. The practical takeaway is blunt. If you're entering underwater smartphone photography for the first time, the SeaTouch 4 Max Plus Ocean Kit with its included protective cover represents the strongest absolute value in this sale window. If you already own compatible accessories, the bare SeaTouch 6 Pro housing makes sense—you skip the bundle tax and buy only what you need later. But if you're building a system from scratch and plan to shoot video at meaningful depth, the 6 Pro Dual-Light Kit at 18 percent off closes the gap faster than any à la carte path. Buy the housing alone, add lights and lenses piecemeal, and you'll pay back the difference twice over once the sale ends.
More

A Swim School Goes Fishing for $5 Million on Nasdaq — and the Warrants Tell the Real Story

(SeaPRwire) -Fitness Champs Holdings Limited is not a tech unicorn. It teaches swimming in Singapore. It has run private lessons under the "Fitness Champs" brand since 2012, and it sits among the largest providers of swim instruction to children in Singapore's public schools through the Ministry of Education's SwimSafer program. A steady, local, real-economy business. Yet here it is on Nasdaq under ticker FCHL, pricing a best-efforts public offering of roughly $5 million. That gap between business reality and listing venue is the whole story. Small-cap foreign issuers keep using US markets as an ATM, and the terms of this deal show exactly how expensive that habit has become. Strip the release to its bones. The offering consists of 14,285,715 units priced at $0.35 each. Each unit carries one Class A ordinary share, par value $0.00225, or a pre-funded warrant in lieu, plus one additional warrant to buy another Class A share. Gross proceeds land near $5 million before placement agent fees and expenses, and that figure excludes any money from warrant exercise. Univest Securities, LLC runs the deal as sole placement agent. The securities come off a Form F-1 registration statement, File No. 333-299806, which the SEC declared effective on November 13, 2026. Closing is expected November 20, 2026, subject to customary conditions. Now look at the warrant math, because that is where the deal gets honest. Each warrant carries an exercise price of $1.02 per share. That is nearly triple the $0.35 unit price. The warrants are exercisable immediately upon issuance and die six months later. Six months is an unusually short fuse. It tells you the buyers are not long-term believers in aquatic education. They are trading vehicles. They got cheap stock today and a free option on any speculative pop. If the stock spikes, they exercise fast and exit. If it drifts, the warrants expire worthless and they still hold shares bought at a steep discount to wherever the market was quoting before the dilution hit. The stated use of proceeds deserves equal scrutiny. The company says the money goes to business expansion, general working capital, and other general corporate purposes. That is the vaguest formulation available in securities drafting. It commits to nothing. For context, Fitness Champs has said it wants to grow into a diversified sports education provider, adding offerings like pickleball alongside its swimming, water polo, competitive swimming, and lifesaving classes. Ambition is fine. But $5 million gross, minus placement agent fees, leaves a thin war chest for genuine multi-sport expansion. This raise smells more like runway maintenance than growth capital. Working capital first, headlines second. Zoom out and the pattern sharpens. Singapore has a deep pool of profitable small education and services businesses, and a growing number of them have chosen Nasdaq listings over their home exchange. The logic is simple. SGX liquidity for micro-caps is poor, and US retail appetite for foreign small-caps, however cyclical, still exists. Placement agents like Univest specialize in exactly this pipeline. The cost is brutal dilution at low prices, warrant overhang that caps any rally, and a shareholder base built for flipping rather than holding. Competitors watching this deal will note the price of admission: roughly $0.35 per unit, with warrants struck far above market, just to access public capital. The SwimSafer contract position and a decade-plus of operating history give this company real substance, but the structure of this raise suggests public markets will treat the stock as a trade, not an investment. Watch the warrant expiry six months from issuance; the volume around that date will reveal who actually owns this company.
More

NewGenIvf Just Sold 71 Million Shares at 3.5 Cents. That’s a Liquidity Signal, Not a Growth Story.

(SeaPRwire) - The press release calls it a "firm commitment underwritten offering." Read the number underneath. NewGenIvf (NASDAQ: NIVF) sold 71,428,570 Class A ordinary shares at $0.035 apiece. Gross proceeds: $2.5 million. That is not a capital raise. That is a tab kept open. This company spans IVF clinics, Ras Al Khaimah real estate, and DeFi. It should not sell paper at three and a half cents. Work the arithmetic before the narrative. 71.4 million shares for $2.5 million gross. Underwriting fees and other offering expenses come out first. The company keeps the remainder. It then says net proceeds go to "general corporate purposes and working capital." That phrase appears when there is no specific plan. Aegis Capital Corp. runs the book alone. Han Kun and Kaufman & Canoles handle the two sides of the legal file. Small deal. Small syndicate. Fast close. Now read the three segments against that cash position. NewGenProperty develops in Ras Al Khaimah. NewGenDigital chases digital assets and decentralized finance. NewGenSup sells health and longevity products. Real estate consumes capital for years before returning any. DeFi consumes engineering and compliance money. Longevity products consume marketing. The legacy IVF and assisted reproductive business across Asia is the only operating cash generator on the list. One engine. Three cost sinks. That is the structure. Watch the shelf mechanics. Form F-3 No. 333-299649 went effective on November 12, 2026. Pricing came on November 19, 2026. Seven days. Pre-funded warrants priced at $0.03499 with a $0.00001 exercise price sum to $0.035. One-for-one, they replace shares in the offering. That structure exists for buyers who want the economics without tripping reporting thresholds. Closing is set for on or about November 20, 2026. That is a tight clock. The revealing number is not $2.5 million. It is $0.035. That is the market's clearing price for this diversified-growth story. Any future raise clears at or below it. Watch the first Form 4 and the first 13D filed after the close. Whoever takes down 71 million shares at this level is not buying the IVF clinics.
More

The $1.00 Trap: NetClass’s Reverse Split Exposes the Brutal Reality of B2B Ed-Tech

(SeaPRwire) -NetClass Technology is playing a dangerous game with its share price. The Singapore and Hong Kong-based firm just announced a major corporate action. It is a 1-for-10 reverse stock split. This move is not about raising capital. It is a desperate bid to meet Nasdaq's one-dollar rule. For a B2B education tech firm, this is a strict line. It operates across Shanghai, Hong Kong, Singapore, and Tokyo. It triggers a silent panic among institutional holders. Many fear that this consolidation signals deeper troubles. The education IT market is incredibly crowded. The stock's liquidity could dry up overnight. Investors might reject this corporate rescue attempt. The board approved this consolidation on November 10, 2026. The new trading structure goes live on November 20, 2026. It will start trading at the Nasdaq open. The ticker symbol remains NTCL. Traders will see a new CUSIP number. It is G6427C207. The consolidation ratio is exactly 1-for-10. Class A shares will combine. The par value changes from $0.0125 to $0.125. Class B shares will undergo the exact same mathematical reduction. No cash payments will be made for fractional shares. Instead, the company will issue one full share. It will cover any fractional leftovers. The total Class A shares will shrink. The count goes from 6.15 million to 0.615 million. The Class B count will drop from 440,000 to 44,000. This reverse split is a temporary patch for a deeper operational challenge. NetClass operates in the brutal B2B smart education sector. It sells SaaS subscriptions and application software. It also distributes AI smart hardware through a joint venture. These services cover campus management, online teaching, and examinations. To survive, the company must prove its recurring SaaS revenue is stable. The reverse split alone will not convince long-term institutional investors. They want to see consistent user retention and hardware adoption rates. The ultimate end-game in this niche is a massive consolidation. Only a few integrated platforms will survive the current capital winter. NetClass must leverage its Asian footprint to secure strategic partnerships. Otherwise, it will become a cheap acquisition target.
More

The $1.1 Billion Robotics Lie: Why WeTouch’s $25M Framework is a Smokescreen for a Shareholder’s Bailout

(SeaPRwire) - You see a twenty-five-million-dollar contract. I see a desperate attempt to prop up a falling knife. WeTouch Technology, a mid-tier Chinese touchscreen manufacturer listed on NASDAQ, just announced a "framework" deal with Anhui Changxin Huitong. The press release breathes down our necks about robotics and AI-enabled systems. It paints a picture of a company pivoting from boring POS terminals to sexy humanoid interfaces. But look closer. This isn’t a sales victory. It’s a valuation fix. The company claims its stock is undervalued. Its largest shareholder is stepping in with open-market purchases of at least $1 million. That is not confidence. That is a lifeline thrown to a sinking ship. Let’s strip the PR varnish. The deal is for "integrated touchscreen systems." We are talking 4.3-inch compact units, 7-inch industrial panels, and 10.1-inch screens for AI robots. These are commodity hardware items. Any Tier-2 display maker can source these panels. WeTouch adds value through firmware adaptation and mounting hardware. It is an integration play, not a component monopoly. The financials tell the real story. In the first nine months of 2026, revenue hit $43.55 million. That is up 9.0% year-over-year. Operating income is $11.74 million. Net income is $8.54 million. Solid, but not explosive. They sit on $170.12 million in cash. They have $191.84 million in stockholders’ equity. They are cash-rich and low-velocity. The robotics contract is a way to justify that cash pile to shareholders who are watching the stock price bleed. Here is the subtext you need to understand. The framework agreement is not a purchase order. The cautionary note in the release is explicit. The $25 million figure is a ceiling, not a floor. Actual revenue depends on "subsequent batch orders." That means WeTouch is betting the farm on future demand that does not exist yet. They are signing a blank check to show the market they have traction in the robotics supply chain. The largest shareholder’s $1 million buy-in is a tiny fraction of WeTouch’s cash reserves. It is a signal, not a transaction. It says, "I am not fleeing, but I am not burning my money to support your valuation." It is a defensive posture. The company is leveraging its balance sheet to manufacture a narrative of growth before the actual hardware hits the robot chassis. The supply chain landscape is not ready for this level of vertical integration. Every robot maker is trying to be a touchscreen designer. WeTouch is trying to be every robot maker’s display vendor. It is a crowded, low-margin space. The real winner here isn’t WeTouch. It’s the shareholder who buys stock at the bottom while the company spins tales of future synergy. Watch the batch orders. Until they come, this is just a press release with a price tag.
More

CTW’s December Roadshow: A Liquidity Play for a Niche Anime Gamification Bet

(SeaPRwire) - Small-cap Nasdaq names often hide in plain sight, relying on conference appearances to manufacture visibility. CTW is doing exactly that with its December itinerary. The company is pitching its G123.jp platform, a browser-based gaming hub built on licensed anime IPs. This is not a massive infrastructure play. It is a targeted attempt to stabilize investor confidence among a specific subset of tech-focused traders. The real question is whether the underlying unit economics justify the current valuation pressure. The facts from the November 17, 2026 release are straightforward. CTW’s management and IR teams will attend two key events. First, the iAccess Alpha Virtual Best Ideas Winter Investment Conference runs December 8-9, 2026. The presentation is scheduled for December 8 at 11:30am ET. Second, the 15th Annual StoneX Discovery Conference takes place December 10, 2026. The venue is the New York Athletic Club at 180 Central Park S in New York. One-on-one meetings with investors are planned for both stops. Why this matters commercially is about access and friction. G123.jp removes the installation barrier. Players do not download games. They do not register accounts. They just click and play. The catalog includes titles like So I’m a Spider, So What? Ruler of the Labyrinth and Queen’s Blade Limit Break. The platform launched in 2018. It claims paying users in over 200 countries. This low-friction model is the core commercial loop. It targets casual gamers who value immediate access over deep engagement. The December presentations aim to prove that this model scales.
More

Adagene’s Bet on Tumor-Specific Antibodies: Why Phase 1 Matters More Than Hype

(SeaPRwire) -I watched a oncologist in San Diego shrug off a new press release last week. He called it "marketing math." Adagene is pushing ADG126, a masked CTLA-4 antibody, into a Phase 1 trial with City of Hope. The pitch is clean: activate immune cells only inside tumors. Cut off blood supply. Kill the cancer. But the market smells hype. It’s another biotech story where the science is solid, but the commercial exit is foggy. The real question isn't whether the drug works. It’s whether anyone will pay for it. The facts are stark. Colorectal cancer kills 55,230 Americans this year. It is the second deadliest cancer in the U.S. Adagene’s trial enrolls just 36 patients. They are testing ivonescimab and ADG126 together. Ivonescimab hits PD-1 and VEGF. It starves tumors of blood. ADG126 boosts immune recognition. The combination aims to break resistance in microsatellite stable (MSS) cases. These are the tough ones. 85% of colorectal cancers are MSS. They rarely respond to standard immunotherapy. Here is the subtext. Adagene isn’t alone in this space. But their "SAFEbody" tech is a differentiator. It masks the drug’s active part until it hits the tumor. This limits side effects in healthy tissue. That is a smart engineering fix. It addresses the "on-target, off-tumor" toxicity that plagues old-school checkpoint inhibitors. Dr. Marwan Fakih leads the trial. He is a consultant to Adagene. That conflict of interest is disclosed. It also signals strong industry commitment. The trial is investigator-initiated. That means doctors, not just sales reps, are driving the design. It feels more clinical, less promotional. The endgame is clear. If ADG126 works, it becomes a backbone for future combinations. Adagene’s CEO, Peter Luo, says this is their third clinical program using this approach. They want to build a platform, not just sell one drug. The risk is high. Phase 1 is about safety, not efficacy. But the data will set the stage. If toxicity stays low, Adagene gets leverage. If not, the mask fails. Investors should watch the dosing results. That is where the real value sits.
More

A Leader Shouldn’t Need to Hustle. Silicon Motion Is Doing It Anyway.

(SeaPRwire) - I have sat through enough investor roadshows to know what they are for. Silicon Motion trades on Nasdaq as SIMO. It is based in Taipei and Milpitas. It already leads the market for NAND flash controllers. It is still working a packed schedule of six events from Singapore to Park City. A leader should not have to hustle. But Silicon Motion is doing exactly that. The company wants investors to understand its position, not just its schedule. The official schedule is dense. On Nov. 18, 2026, Silicon Motion holds meetings only at Morgan Stanley's 25th Annual Asia Pacific Summit in Singapore. It also holds meetings only at Roth's 15th Annual Technology Conference in New York. On Nov. 30, 2026, it presents a webcast at the UBS Global Technology and AI Conference in Scottsdale. The session starts at 11:35 a.m. MST. On Dec. 8, 2026, it holds meetings only at Wells Fargo's 10th Annual TMT Summit in Rancho Palos Verdes. On Dec. 9, 2026, it presents a webcast at the Nasdaq 55th London Investor Conference in London. On Dec. 10, 2026, it holds meetings only at Roth's 15th Annual Deer Valley Event in Park City. Interested parties can listen to the live audio webcast on the investor relations section of Silicon Motion's website. A replay will stay available for 90 days. Now the subtext. Silicon Motion designs and markets NAND flash controllers for solid state storage devices. It also supplies automotive and boot drive solutions. The company sells more SSD controllers than anyone else for servers, PCs, and client devices. It is the leading merchant supplier of eMMC and UFS embedded storage controllers. These are used in smartphones, IoT devices, and other applications. It makes customized high-performance SSD solutions for hyperscale data centers. It also makes specialized industrial and automotive SSD solutions. Its customers include most NAND flash vendors, storage device module makers, and leading OEMs. The roadshow is not about survival. It is about dominance. Now the blunt part. Conference meetings create visibility. They do not create design wins. The real contest happens in hyperscale data center qualification, automotive validation, and storage device module maker sourcing decisions. Silicon Motion has the technology and the customer base. The roadshow simply makes sure that everyone in the room knows it. The market share reshuffle will not be decided in a hotel suite. It will be decided in the supply chain.
More
Forget the Scarf. The Best Holiday Gift for Nurses Is a Pocket Heater That Survives the Night Shift. Business

Forget the Scarf. The Best Holiday Gift for Nurses Is a Pocket Heater That Survives the Night Shift.

(SeaPRwire) - Cold reality hits healthcare workers hardest. Hospital corridors stay drafty year-round. Pharmacies blast air conditioning even in winter. Nurses wash hands dozens of times per shift. That strips natural warmth from fingers. Thick gloves are useless for fine motor tasks. Counting pills, typing, starting an IV—all demand bare hands. A portable heater in the pocket is not a luxury. It's a daily necessity for the people who keep us safe. The brand gets that. On Nov. 16 in New York, AUIIAH released two hand warmer models built for these exact shifts. The timing is deliberate—holiday gifting season starts now. First model is the YZE-B23. It brings dual-sided heating. Eight adjustable modes let you dial in comfort. The battery is 8000mAh. Across the two-pack, continuous warmth lasts 4 to 30 hours. That covers a full shift and then some. There's a built-in flashlight too. That matters for late-night walks to the parking lot. The hand warmers recharge via USB-C. They fit into a lab coat, scrub pocket, or tote bag. This is the endurance option for long shifts. It's the one you grab before a 12-hour overnight. The 2-pack lets you keep one unit for yourself and hand the other to a colleague. Second model is the YI08. It's the lightweight one. The owl-inspired design is playful. A small moment of levity in a stressful place. The magnetic build snaps together. Four heat levels give quick control. Two-second instant heating means no waiting. A smart LED display shows battery and heat setting. No guesswork. This one fits into winter gloves. It's the on-the-go option. Perfect for someone who wants warmth without bulk. It also works for Raynaud's, arthritis, or just always-cold hands. Both models are available on Amazon in multiple colors now. The holiday gifting angle is real—patients and families can show appreciation. AUIIAH is not chasing the outdoor crowd exclusively. The healthcare worker angle is smart. Pharmacists and nurses face a cold reality most people never think about. The holiday gift market is huge. Black Friday pricing is coming later this month. That lowers the barrier. For hospital management, a 2-pack is an easy employee gift. For families, it's a way to say thank you to someone who works nights. The message is simple. This is practical emotional value. It's not just for hospitals. Outdoor workers, hunters, sports fans—they all get cold. The real game is building a brand that owns personal warmth in cold environments. Safety is the unspoken selling point. These devices sit against bare skin for hours. AUIIAH uses lithium polymer batteries. That is the same reliable type found in modern smartphones. High-quality chip control systems prevent overcharging and short circuits. That is complete peace of mind. The market is crowded with cheap alternatives. But cheap heaters fail or get too hot. AUIIAH's focus on safety and portability is the differentiator. The brand understands real-life use cases. That's why it's a credible gift for professionals who deserve better. The magnetic 2-pack design adds another layer—you share warmth with a colleague. This is not a gadget; it's an acknowledgment of hard work. Next winter, the pocket heater becomes standard issue in every hospital break room.
More
The Credit Card-Sized Heat Source Trying to Rewrite Winter Gear Rules Business

The Credit Card-Sized Heat Source Trying to Rewrite Winter Gear Rules

(SeaPRwire) -Winter outdoor gear often fails the usability test. We want warmth. We also need phone access. We need to adjust goggles. Traditional gloves fail this balance. The consumer market floods us with bulky, single-use chemical warmers. Heavy rechargeable units feel like bricks inside thick gloves. This gap between thermal utility and daily usability quietly kills winter wearables. FYALLASO tries to bridge this divide. Their new magnetic split-system weighs barely two ounces. Can a gadget this small survive sub-zero mountain physics? Or is it just a colorful novelty? FYALLASO launched its YI08 model on November 15, 2026, targeting the winter ski season. The device features a split magnetic design. Users snap the units together for double-sided heat. Or they separate them, slipping one into each glove. Each unit packs a 2000mAh battery. It delivers 5 to 10 hours of warmth on a single charge. Combined, they reach up to 20 hours. Measuring 3.39 by 1.81 inches, the unit is tiny. It weighs just 2 ounces. It is smaller than a credit card. It heats up in 2 seconds. It sports a digital LED display. Vibrant eagle-themed colors add style. The package includes a Y-shaped USB-C cable. It is currently available on Amazon. The move by FYALLASO highlights a broader shift in consumer wearables. Brands are moving away from generic, utilitarian accessories. They are moving toward specialized, aesthetic-driven gadgets. These devices double as lifestyle statement pieces. By targeting ski slopes, winter vacations, and outdoor hunts, FYALLASO carves a niche. Style meets function here. The upcoming Black Friday promotional pricing on Amazon signals an aggressive push. They want to capture holiday gift-seekers early. The ultimate end-game is commoditizing warmth. As winter travel rebounds, brands that make portable heating invisible will win. FYALLASO has a solid shot. Success depends on magnetic joints surviving real-world drops. It also depends on the batteries holding up in freezing temperatures.
More
Geekvape’s Dubai Move: The Quiet Shift From Coils to Chips Business

Geekvape’s Dubai Move: The Quiet Shift From Coils to Chips

(SeaPRwire) - Dubai is not the place to announce a new coil. The Middle East is a regulatory minefield. Yet Geekvape chose it to unveil VPU 2.0 on November 10, 2026. The timing suggests a strategic pivot. They are no longer selling hardware. They are selling a control layer. The “platform” label is the real signal. This is about locking in users via firmware updates. The hardware is just the carrier. Geekvape claims 25% faster wicking. Liquid coverage increased by 31%. Absorption capacity rose 17.1%. These numbers beat the old material. The mesh coil design shifts too. Effective atomisation area grew by 28.2%. Vapour output hit 29% higher. Uniform heat distribution is the target. The physics are standard, but the execution is tight. They cite internal R&D testing for all figures. The data supports a more efficient burn. The AI layer changes the game. Startup control now activates flavour in 0.01 seconds. This is not just speed. It is coordination. Airflow, heating, and liquid delivery sync up. The device tells the coil what to do. SONDER Q MAX uses this stack. Geekbar BURJ, PCE40000, and ICE MASTER 60K follow. OEM projects confirm the shift. Manufacturers are adopting the VPU standard. The component becomes a service. Users depend on Geekvape’s algorithmic updates. The supply chain landscape is flattening. Component makers are losing leverage. Device brands are winning the margin. VPU 2.0 is a tollbooth. Every puff runs through their code. The hardware depreciates. The software retains value. This is the new reality. Coils are commodities. Control is the product.
More
Why Your Golf Game Is Failing in November (And How an 8000mAh Battery Fixes It) Business

Why Your Golf Game Is Failing in November (And How an 8000mAh Battery Fixes It)

(SeaPRwire) - Stop blaming the wind. Your grip is failing you because your hands are numb. That 8 a.m. tee time in late fall isn’t about strategy. It’s about biology. Stiff fingers wreck your swing. Hunters face the same wall. Sitting in a blind, cold kills aim and patience. Gloves help warmth but kill motor control. You need to feel the trigger. You need to feel the lure. This isn’t a comfort issue. It’s a performance defect. Most gear ignores this. They sell you jackets. They don’t sell you functionality. JMOSTRG just dropped a solution that reads like a spec sheet for survival. The device packs an 8000mAh battery. That is a lot of power for a pocket item. It delivers 4 to 15 hours of heat per unit. A two-pack setup gives you up to 30 hours. Eight modes control the temperature. The max output hits 127.4°F. Crucially, the heating is dual-sided. No more cold fingertips while your palms are warm. It fixes the "half-cold hand" problem. The smart LED display shows battery and heat level. No guessing game. The utility extends beyond warmth. A built-in flashlight is included. This matters for pre-dawn walks to a deer stand. It helps when you are digging through a dark truck for gear. It lights the trail back to the car. The weight is negligible. Each unit is 3.7 ounces. Lanyards keep them secure. The form factor fits in a vest pocket or a golf cart. It is not a bulky heater. It is a tool. The price point is flexible. Black Friday pricing is coming later this month. The standard version is already on Amazon. Here is the blunt truth. This is a commodity play. The technology is not new. Batteries are cheap. Heating elements are standard. The value is in the packaging and the specific use-case targeting. The market for niche outdoor comfort is fragmented. JMOSTRG is carving a slice by speaking directly to golfers and hunters. They are not selling tech. They are selling extended season time. If your hands are cold, your season is effectively over. This device buys you time. The supply chain is stable. The demand is seasonal. Buy before the peak if you need it. Do not wait for the winter rush.
More

Chery’s Moblie Empire Dream: Why Owning Every Link Is a Dangerous Bet

(SeaPRwire) - Chery is not pitching individual vehicles at the 2026 International User Summit in Wuhu. They are pitching total trip orchestration. One stop handles parking, charging, ground departure, and air departure. The ambition is obvious. Here are the components sitting on the stage. The factory-integrated Level 4 Robotaxi handles app-based bookings, remote cabin pre-conditioning, autonomous pickup, and fleet maintenance alongside automated charging robots. The Lingxiao Q212 is a two-seat compound-wing eVTOL. The Lingxiao J506 carries five passengers using a fully tilting six-rotor layout, targeting speeds above 350 km/h and ranges exceeding 1,000 km, powered by CheryMind and the CHERY All-World Engine platform. Add Super Intelligent Valet Parking for hands-off vehicle drop-off, Volt-dragon Ultra-Fast Charging infrastructure, and vehicle-to-grid energy routing. The concept threads these pieces together so a traveler parks at SIVP in one city, boards a Robotaxi for local transit, transfers to an eVTOL for intercity leg coverage, and arrives at a destination where intelligent handoffs eliminate waiting periods and ground-dependent bottlenecks. This is where the strategic wager becomes clear. Chery is attempting to control every node in the travel chain instead of supplying components inside someone else's platform. Parking facilities, ground fleets, low-altitude flight corridors, and energy distribution all converge under one brand handshake. Automobile manufacturers rarely survive by owning the full stack. The risk is enormous. If Chery executes even partially, they become the default booking layer for multi-modal travel. If execution fractures across any segment, the whole architecture stalls. Either way, they are forcing competitors, regulators, and energy utilities to react to their timetable rather than the other way around.
More
Solana’s Onboarding Nightmare Just Met Its Match: Why Finchb’s Radical Transparency Is a Masterclass in Trust Business

Solana’s Onboarding Nightmare Just Met Its Match: Why Finchb’s Radical Transparency Is a Masterclass in Trust

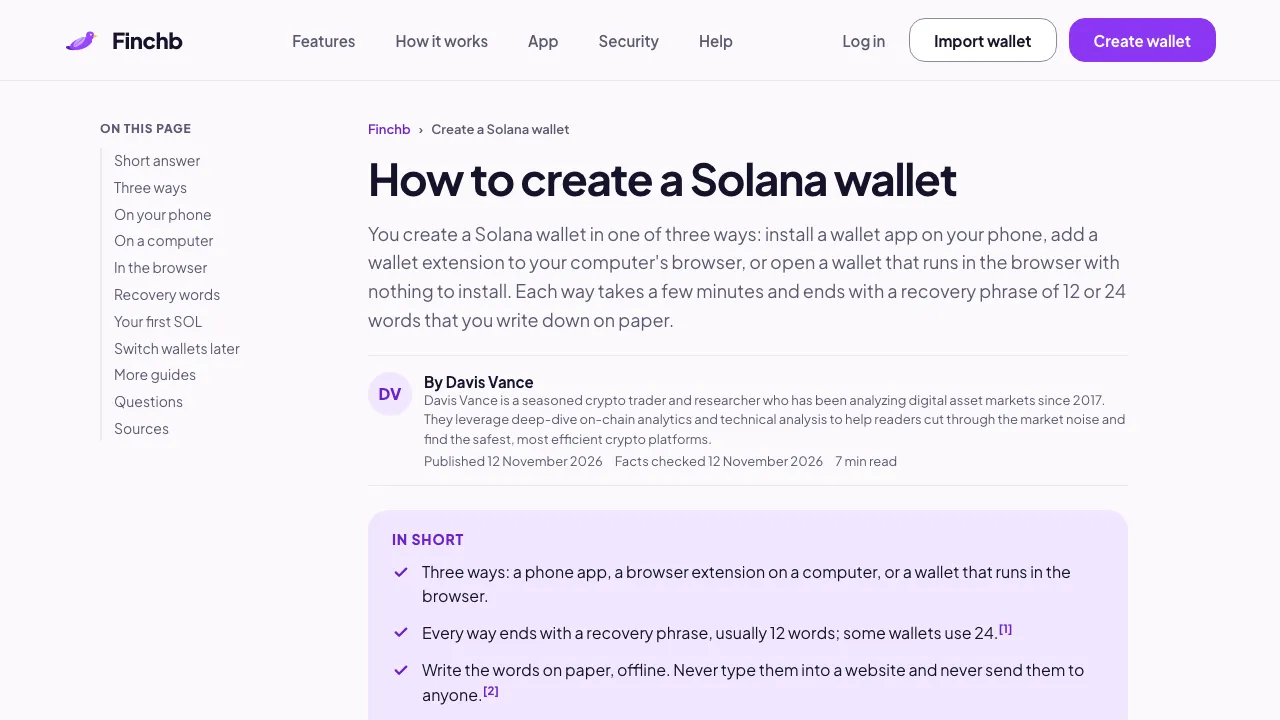
(SeaPRwire) - Solana is a beast to enroll into without proper preparation. One wrong network selection means permanent loss of funds. A simple copy-paste error can send your assets into the cryptographic void forever. This is the brutal reality of Web3 onboarding that venture capitalists gloss over in polished pitch decks. Finchb, a Singapore-based wallet running in your browser and Telegram, is stepping into this mess. They are handing out absolute, fully referenced guides to the average user. They treat transparency as a core utility, not a marketing slogan. This approach challenges the traditional closed-door playbook of the industry. The raw mechanics of what Finchb actually launched are clear. They published four specific guides covering wallet creation, stablecoin transfers, Telegram integrations, and an address validation tool. The wallet creation guide compares browser extensions, installable apps, and web wallets. It emphasizes the sacred importance of writing down a twelve or twenty-four-word recovery phrase on physical paper. The stablecoin guide cuts through the confusing alphabet soup of TRC20, ERC20, BEP20, and SPL networks. It maps out safe transfer pathways for moving USDT from TRON to Solana. All of this is written by Davis Vance. It is completely free of any login wall. It is translated into Spanish and German. The transparency extends to a brutally honest comparison table of six Solana wallets. This table is available in nine languages. It does not hide Finchb's limitations. It explicitly lists what they lack, such as hardware wallet support, native apps, and NFT capabilities. Alongside this, their twenty-one article help center is localized in nine languages. It includes English, French, Spanish, Arabic, and Russian. It uses real screenshots to answer painful support queries. This is raw, unvarnished utility designed to solve the painful first-week questions that every single newcomer faces. The help center covers withdrawal issues, wrong network transactions, and blockchain verification. Why would a wallet operator invest heavily in generic, non-branded educational content? The answer lies in the brutal economics of user acquisition in the crypto space. Trust is the scarcest resource in this sector, and newcomers are constantly abandoned by opaque platforms. By publishing unbiased guides and explicitly listing their own wallet's limitations, Finchb plays a long-game of radical honesty. They position themselves as a neutral public utility, building a massive trust reservoir. Users will naturally choose the path of least resistance. When they need a wallet, they will default to the brand that was honest with them when others were not. This strategy is a double-edged sword in the highly competitive Solana landscape. By openly admitting the lack of hardware wallet support, dApp connectivity, and NFT features, Finchb risks steering security-conscious power users directly toward competitors. However, this level of candor also shields them from the severe backlash that typically accompanies overhyped marketing. It appeals strongly to the casual trader or the absolute beginner. This demographic just wants to hold USDT and make simple transfers without the overwhelming complexity of a comprehensive feature suite. This is the exact segment where their simplified, browser-based model excels. As the broader Solana blockchain environment matures beyond its speculative peaks, expect the next wave of aggressive wallet consolidation to be driven not by superficial feature checklists, but by the single provider that successfully earns the absolute, long-term trust of the casual everyday holder through radical, unbranded transparency, ultimately forcing every silent competitor to either open their proprietary source code, disclose their full security audits, or abandon any pretense of targeting the mass market entirely, a shift that will redefine how casual users interact with decentralized finance protocols without even realizing they are crossing a corporate boundary.
More
Genius Group’s 27 Million Share Bonfire: Rescue Plan or Reverse-Split Survival Game?

(SeaPRwire) - Strip away the press release language and this is what remains: a small-cap education company fighting to keep its NYSE American listing alive. Genius Group has called an EGM for December 29, 2026, in Singapore. The agenda is cancelling up to 27,387,374 Class A ordinary shares and gaining blanket authority for yet another reverse split. Management frames it as building an "institutional-grade share structure." The market reads it differently. When a company needs a 1-for-10 consolidation just to stay listed, the narrative is about survival mechanics, not growth. That is the real story here. The facts are precise. In June 2026, Genius Group bought back roughly 12.6 million shares. Now it wants approval to cancel 20 million ERL-related shares: 14,546,057 surrendered by Entrepreneur Resorts Ltd for nil consideration, plus 5,453,943 treasury shares. A second resolution covers up to 7,387,374 shares from LZG International, tied to an ICC arbitration award dated April 20, 2026. Those get cancelled only after a court order, liquidator transfer, or voluntary return. Special resolutions need 75% approval. ERL and LZG abstain. The record date is November 24, 2026. Resolution three is the sleeper item. The Board wants precautionary authority to execute another consolidation, anywhere from 1-for-3 to 1-for-19, within 18 months. Management says nothing is planned. But note the timing: a 1-for-10 split takes effect November 20, 2026, nine days before this authority would even be voted on. That sequence tells you the compliance pressure is immediate. NYSE American minimum price rules do not care about your AI education story. Pre-authorizing a second split means the first one may not hold. Competitors and capital providers watch these moves coldly. Genius Group reports US$106 million in net assets, 99% of third-party debt repaid, and US$6.7 million in combined operating profit on 112% revenue growth over nine months. NAVPS sits at $0.61, and the 1-for-10 split lifts that mechanically to about $6.10. None of this changes actual enterprise value. It changes the ticker optics. Institutional desks have price floors and mandate constraints. A sub-dollar stock is simply unbuyable for many funds, regardless of fundamentals. The strategic layer is the proposed ASX dual listing and the Genius City and GENIUSpark data center ambitions in Australia and Southeast Asia. A cleaner share count and a higher nominal price are prerequisites for courting that investor base. Cancelling surrendered and arbitrated shares is genuinely shareholder-friendly arithmetic, assuming net assets hold. But it also concentrates control among remaining holders and shrinks the public float. Reduced float means thinner liquidity, wider spreads, and more volatile price action. That is a trade-off the release does not dwell on. Watch what happens to the share price in the 90 days after November 20, because if it drifts back toward compliance territory, that precautionary 1-for-19 authority stops being precautionary.
More

Beyond Ticker Swaps: Why Skyline’s Shift to ‘CRMN’ Can’t Mask Raw Material Bottlenecks

(SeaPRwire) -Rebranding an offshore shell company does not instantly deliver enriched uranium or heavy rare earths. Skyline Builders Group Holding changed its Nasdaq ticker from KAZR to CRMN on November 12, 2026. Hardware architects care about physical supply volumes, not corporate symbol updates. Pumping paper assets into complex holding structures creates market noise. The hard reality of processing critical minerals remains entirely untouched by ticker changes. Investors need actual refined tonnage. Wall Street filings cannot replace physical refining capacity. On November 2, 2026, Skyline mutually terminated its business combination agreement with Cove Kaz Capital Group. The official narrative presents this deal split as a clean strategic realignment. Cove Kaz now aims for a direct listing in the first half of 2027. Executive Chairman Paul Mann claimed full support for the listing strategy of Cove Kaz. The company then executed the Nasdaq ticker change to CRMN on November 12, 2026. In reality, breaking off a business combination forces both parties back to independent balance sheet risk. Changing ticker symbols requires no action from existing shareholders. Yet it marks a sharp pivot after walking away from the original merger architecture. Skyline originated as a Cayman Islands exempted company tied to Asian construction assets. In the third quarter of 2025, US investors led by American Ventures injected cash to take control. Their declared mandate was divesting legacy Asian construction assets. They shifted focus toward securing critical minerals and nuclear fuels for US customers. In November 2025, Skyline bought an approximate 20 percent stake in Kaz Resources LLC. The corporate pitch highlights supply security for American critical materials. However, holding a 20 percent passive interest in Kaz Resources LLC does not equal operational supply control. Transitioning from Asian real estate to strategic nuclear fuels requires heavy physical capital. Financial engineering alone cannot build domestic refining infrastructure. US buyers seeking critical minerals must look past ticker shifts like CRMN. Strategic material security requires actual refineries, long-term off-take contracts, and operational processing nodes. Until paper holding companies deliver physical tonnage into supply chains, ticker changes remain cosmetic market placeholding.
More
Vatrer’s $2,400 Price War Is a Warning Shot to Every Lithium Battery Competitor Business

Vatrer’s $2,400 Price War Is a Warning Shot to Every Lithium Battery Competitor

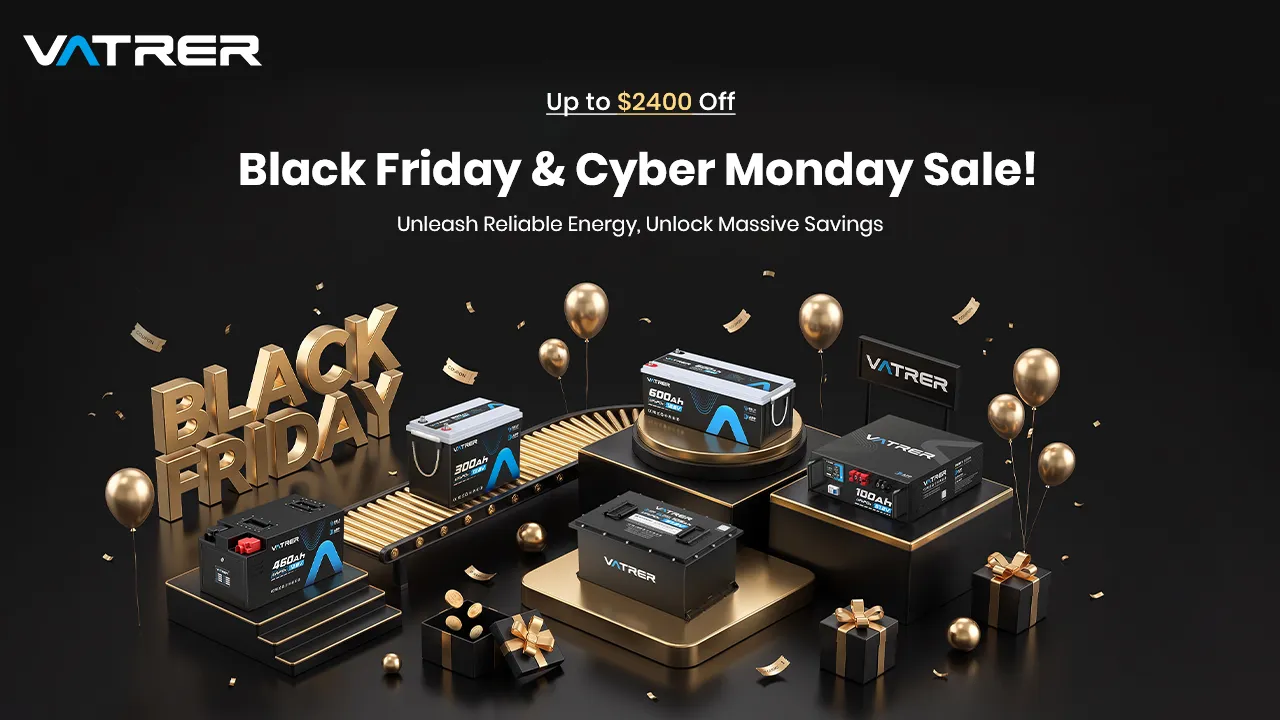
(SeaPRwire) - Most lithium battery promotions sound the same. Discount headlines, urgency tricks, seasonal framing. Vatrer Power's Black Friday pitch looks different only because the numbers behind it are louder than usual. A $2,400 maximum discount on LiFePO4 cells is not a marketing flourish. It is a signal about where the commoditization line currently sits — and who plans to defend it. The headline figures trace directly to Vatrer's own release. The 48V 105Ah golf cart model delivers 5.376 kWh and up to 50 miles of range. Step up to the 48V 150Ah and you get 7.68 kWh with roughly 70 miles. For RV use, the self-heating line runs from 12V 300Ah at 3.84 kWh through 12V 460Ah at 5.888 kWh. The server-rack entry point hits 48V 100Ah at 5.12 kWh per unit, with Bluetooth monitoring, Wi-Fi connectivity, and self-heating built in. Marine SKUs include a 12V 100Ah Group 24 and a 24V 200Ah variant aimed at trolling motors. Add chargers, DC-DC converters, and pure sine wave inverters to the basket and the upgrade path broadens quickly. The discount window does exactly what any deep-discount cycle does under pressure. It accelerates lead-acid-to-lithium conversion among cost-conscious buyers who would otherwise shop incremental trade-in deals over months. That matters more than the sticker saving. Conversion lock-in raises lifetime value per customer. It also raises switching costs when the next upgrade arrives. Behind the spec sheet sits the commercial architecture most press releases leave unstated. Vatrer bundles gift incentives — Facebook and YouTube giveaways valued at $4,500 combined, Energy Cubes for subscriptions, shares, and cart adds, free shipping, a 30-day price guarantee, and seven-day free returns. Qualifying multi-battery purchases include complimentary server racks. These are not gratuitous perks. They are margin-preserving tactics that shift acquisition cost away from direct price cuts while keeping the headline number compelling. The real question is supply chain durability. Lithium-cell pricing has tracked raw-material corridors and Chinese export dynamics. A discount this wide either rides current cell-cost headwinds favorable to importers or burns margin intentionally to widen share before competitors reprice. Either way, the move draws a line around the accessible-price tier of residential and recreational storage — the segment where Chinese-made LiFePO4 packs already compete on weight, usable capacity, and maintenance reduction. Vatrer is staking turf inside that segment rather than chasing premium branding. The compact version of where this leaves the market is straightforward. Holiday促销 cycles compress buying decisions that normally stretch across quarters. Buyers who hesitate will likely transact now if the perceived gap between lead-acid replacement cost and lithium savings looks real on paper. Vatrer is betting that the $2,400 headline, paired with accessory bundling and cross-category coverage across golf carts, RVs, marine, solar, and home backup, creates enough breadth to convert single-SKU shoppers into multi-product customers. The endgame for competitors is not to match the deepest cut. It is to survive the conversion wave without eroding their own margin floors. If Vatrer sustains this pricing cadence into Q1, the consolidation pressure on mid-tier brands rises sharply. Market share reshuffles inLiFePO4 discretionary segments usually follow a pattern — volume leaders prune their SKU depth, niche players retreat to application-specific margins, and the rest adjust to whoever sets the price floor first.
More