(SeaPRwire) – By: Oliver Hawthorne
The stablecoin story used to be loud. In the early days, the pitch was simple. Move money faster. Cut out banks. Skip settlement delays. That pitch has quietly died. Not because the technology failed, but because the real world pushed back. Merchants demand compliance. Treasury teams demand controls. Regulators demand visibility. So the industry stopped talking about replacing payment networks and started worrying about something far less glamorous. The settlement layer. The central anxiety now sits in the gap between tokenized liquidity and regulated payment rails. Can a stablecoin issuer mint a dollar, move it across a border, and settle it into a Visa card program without creating audit chaos? Can a corporate treasurer hold stablecoin reserves and still reconcile accounts at midnight? Can an enterprise run a global payout system with the same fraud controls that apply to fiat? Those are the questions WasabiCard is forcing into the open during TOKEN2049 week. It sounds technical. It is actually existential. If stablecoin liquidity cannot survive contact with card networks, corporate expense policies, and cross-border compliance, then the whole experiment stays stuck on trading desks.
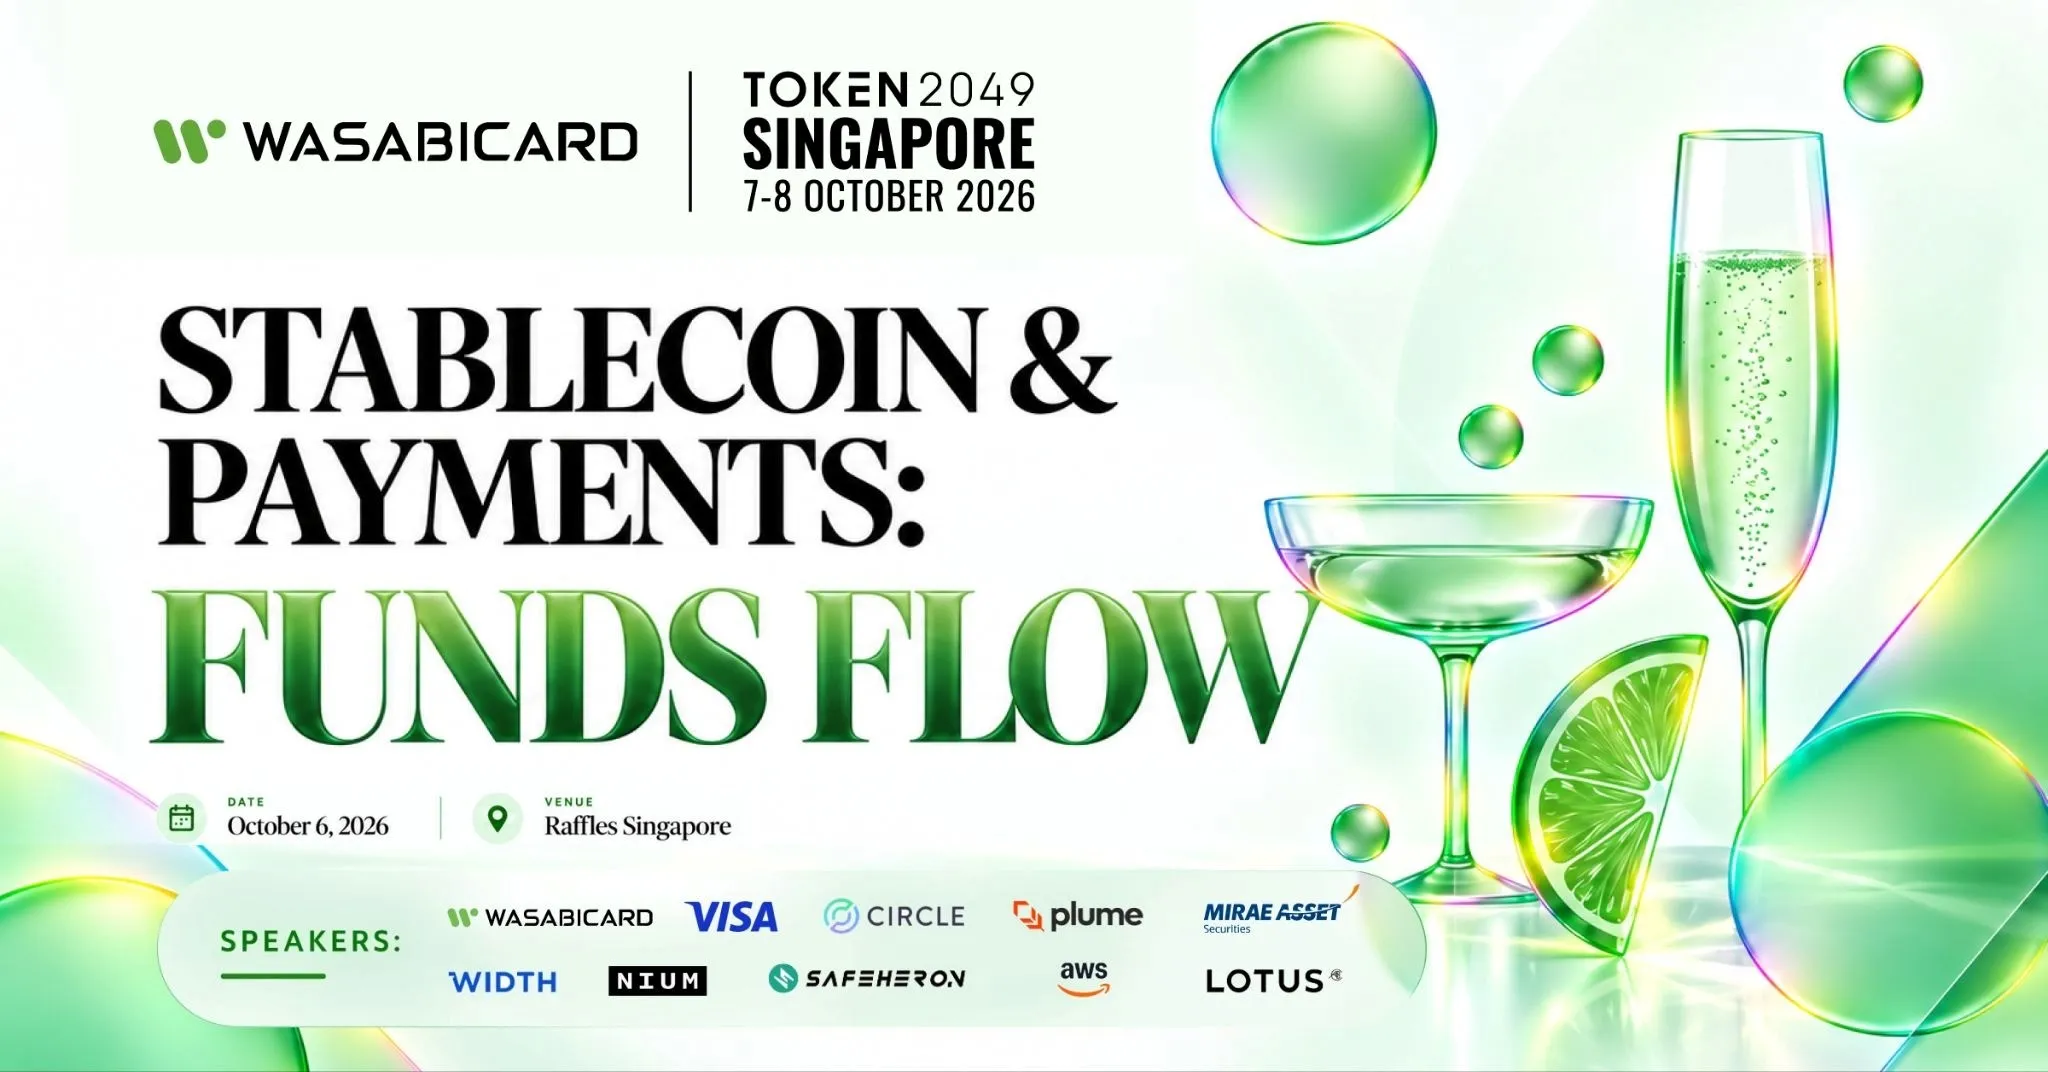
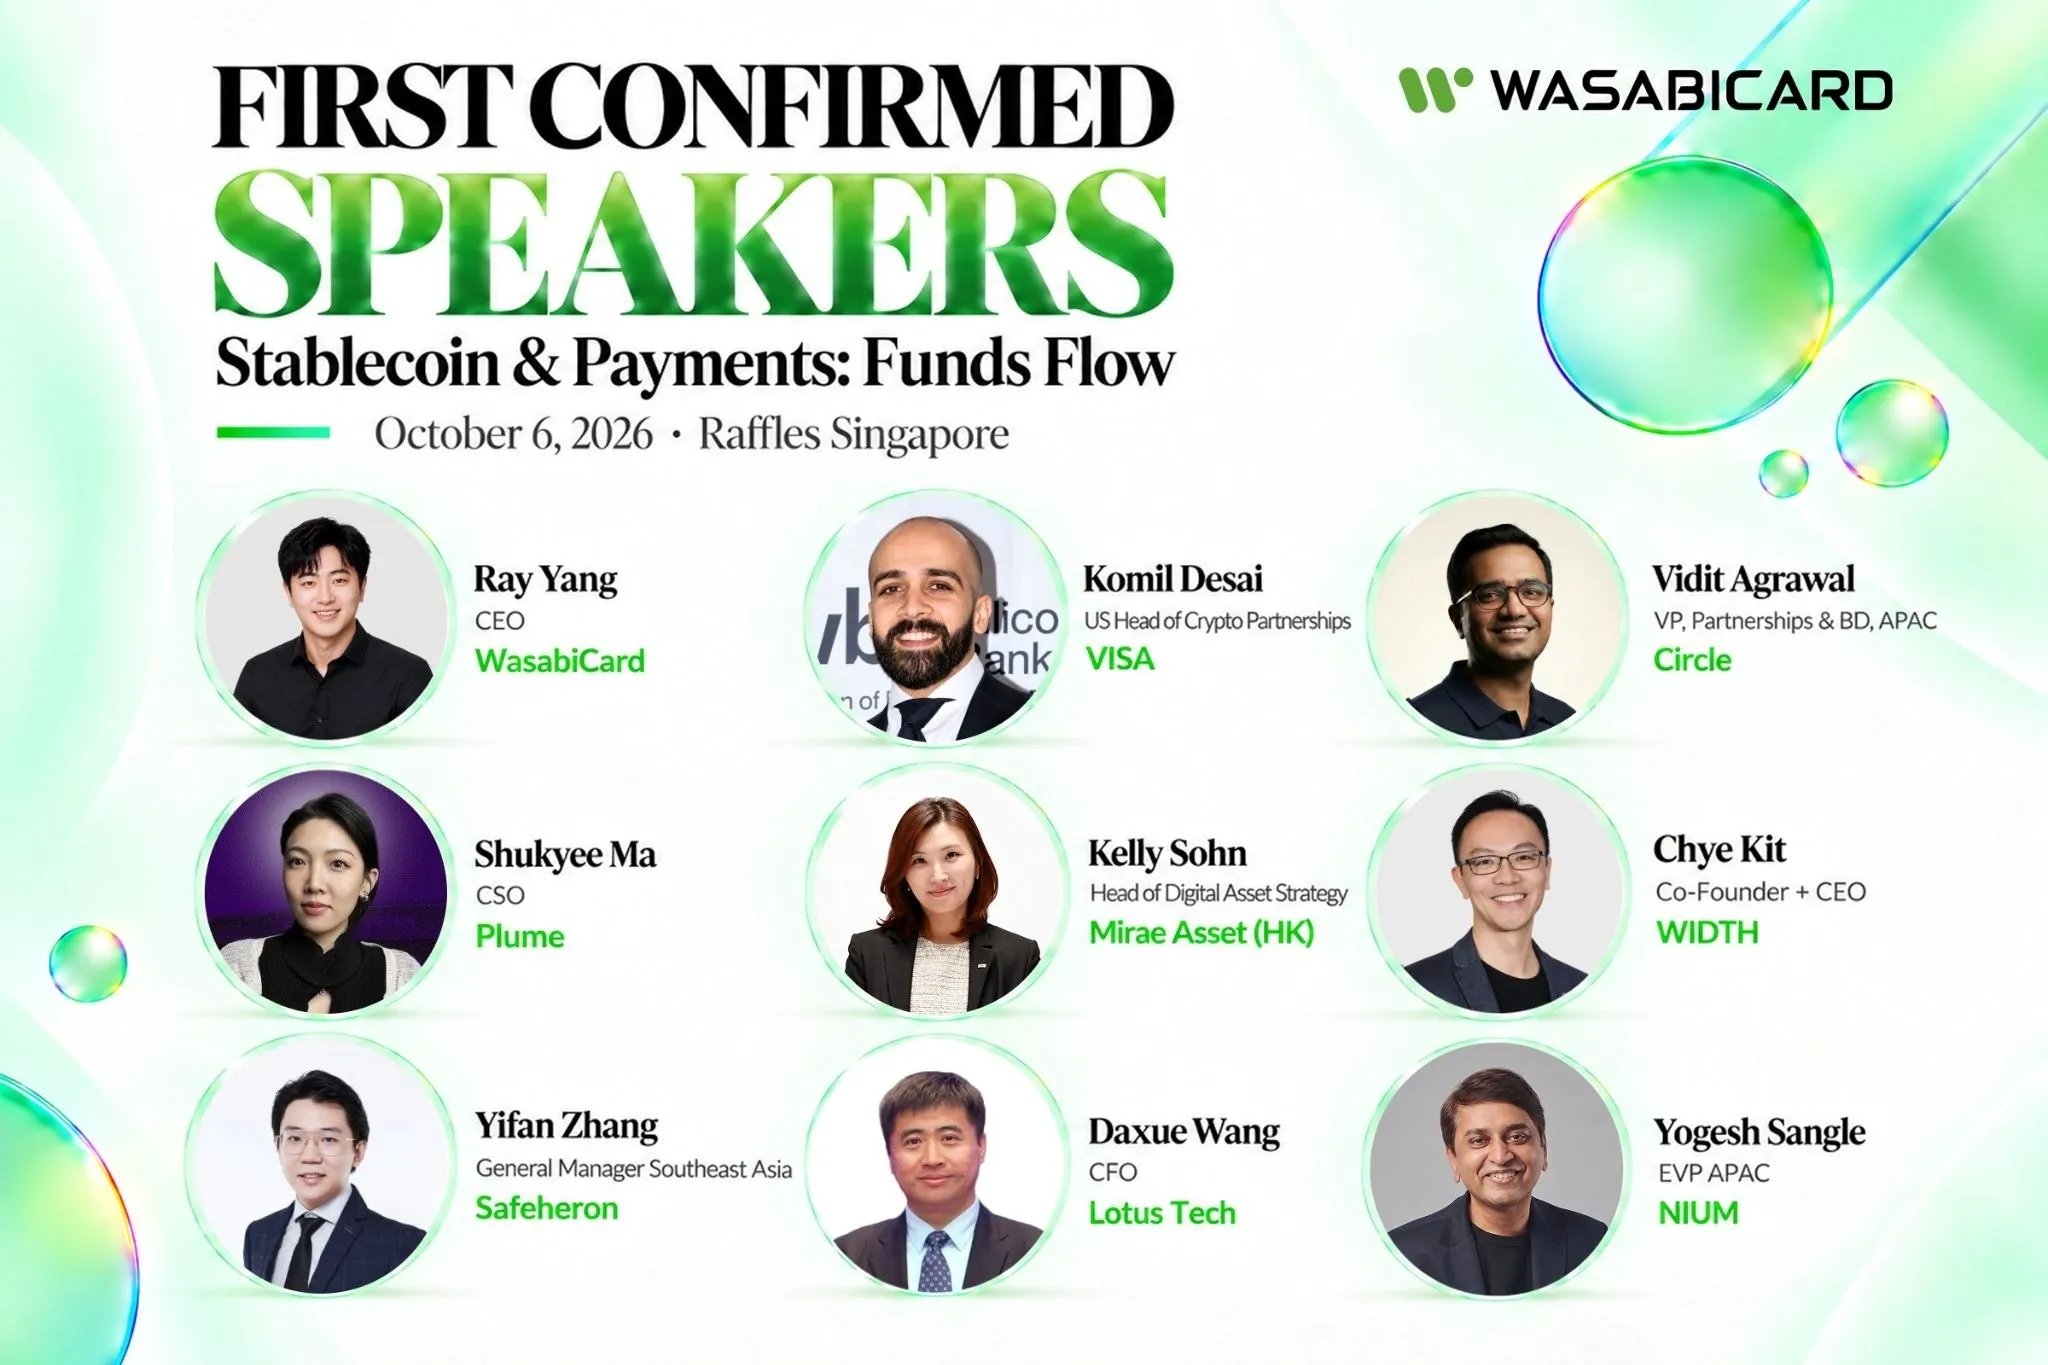
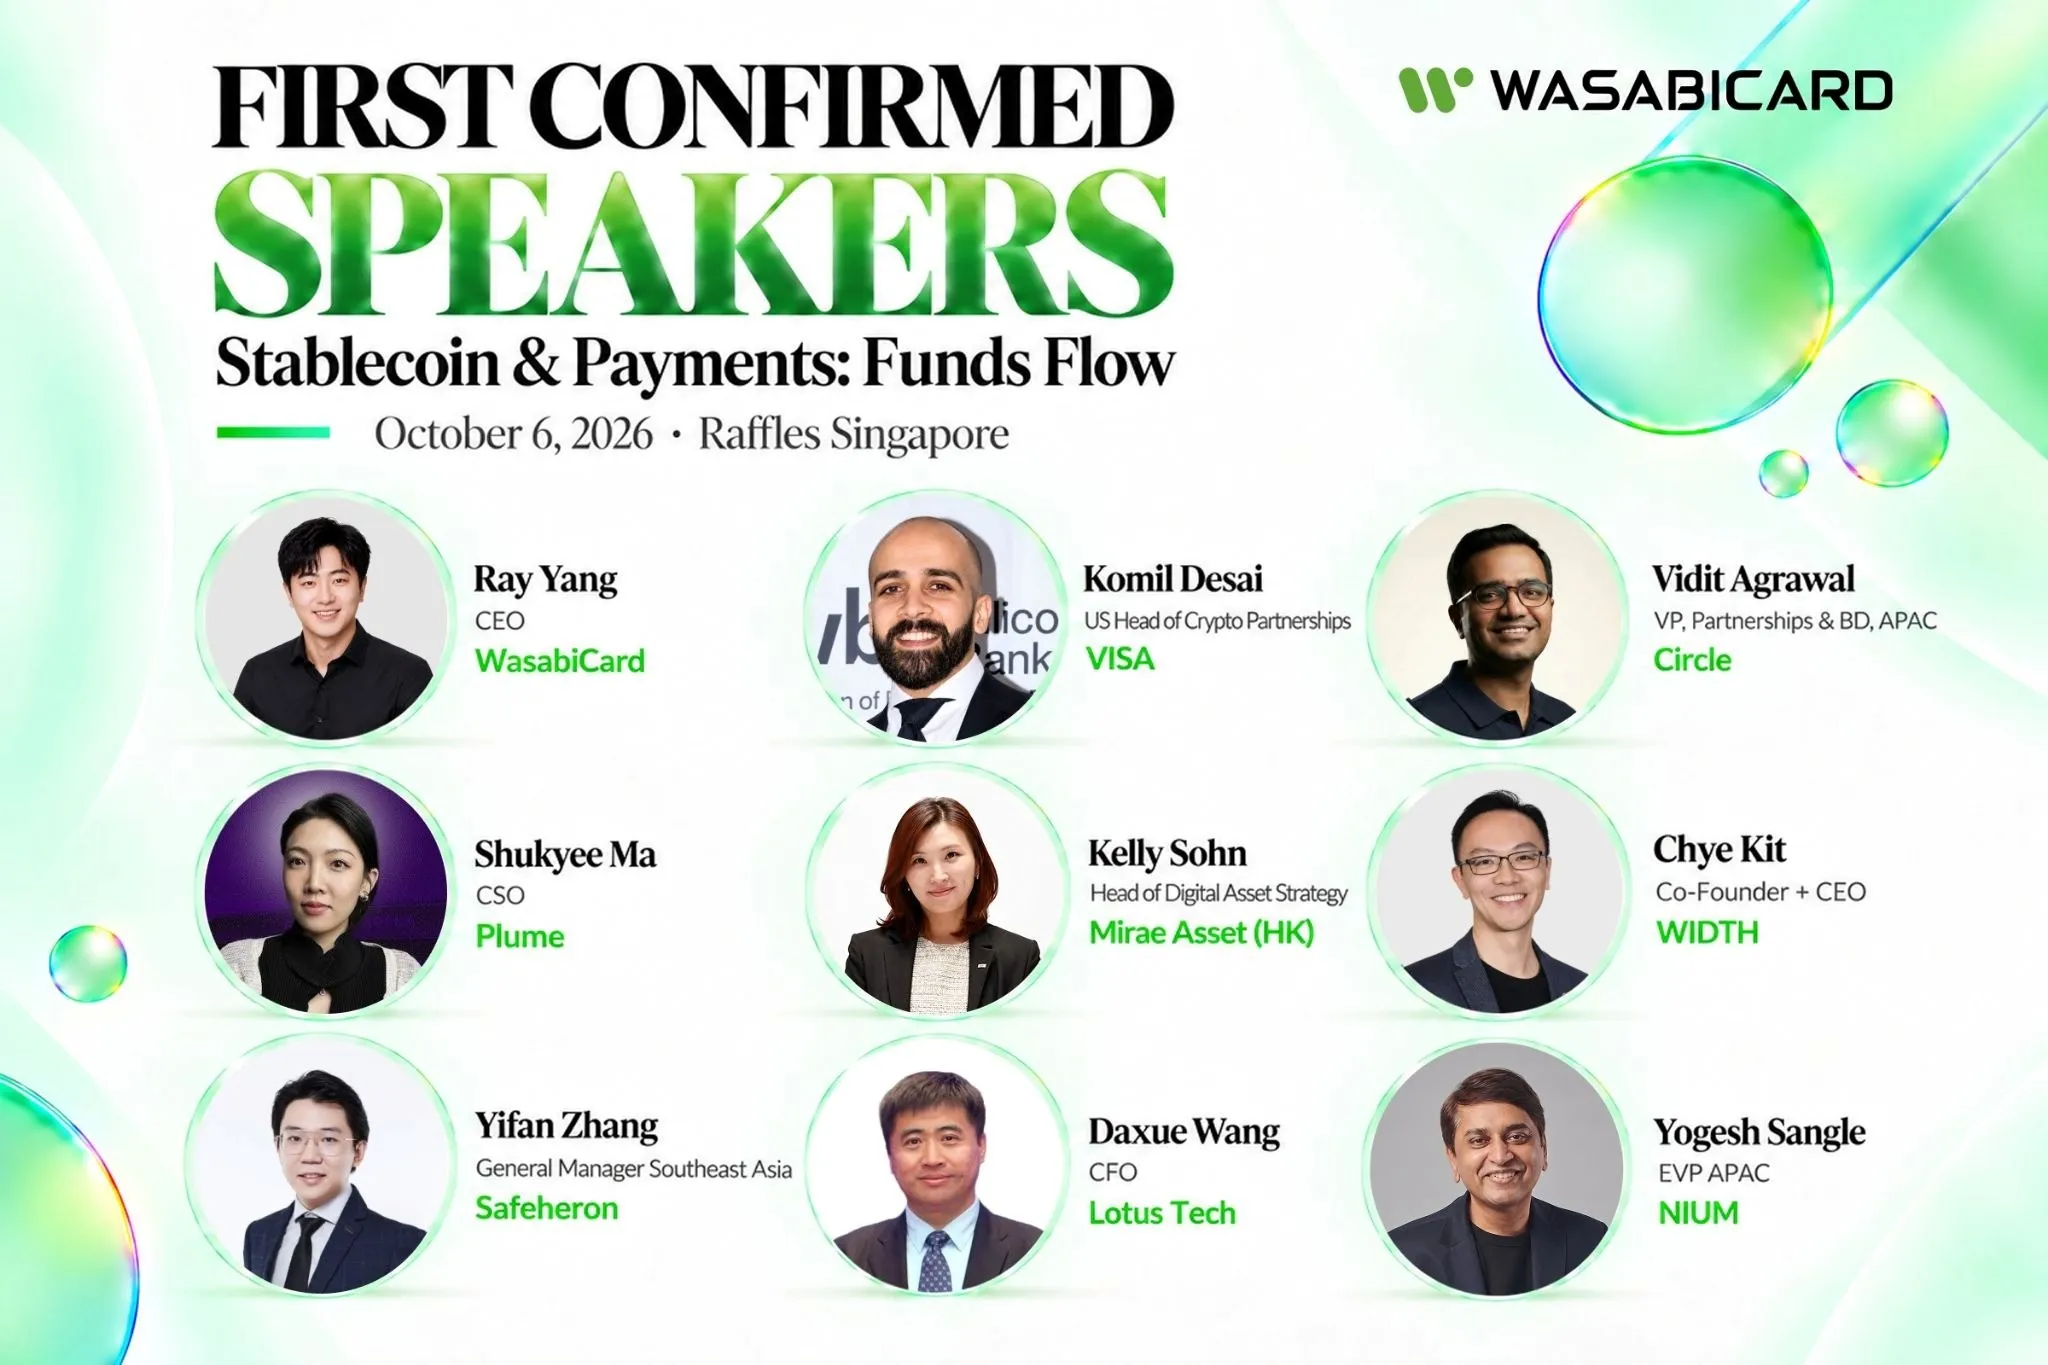
On October 6, at Raffles Singapore, WasabiCard will host “Stablecoin & Payments: Funds Flow.” The location is a signal. Raffles is not a crypto convention hall. It is an old luxury hotel with colonial polish. That contrast tells you how the industry wants to be seen now. Not as rebels, but as established infrastructure. The guest list reinforces the point. Vidit Agrawal, Vice President of Partnerships and Business Development for APAC at Circle. Komil Desai, US Head of Crypto Partnerships at Visa. Yogesh Sangle, EVP APAC at NIUM. Shukyee Ma, Co-founder of Plume. Yifan Zhang, General Manager, South Asia at Safeheron. Chye Kit, Co-founder and CEO of WIDTH. Kelly Sohn, Head of Digital Asset Strategy at Mirae Asset. David Sung from AWS. Dr. Daxue Wang, CFO of Lotus Technology. These are not crypto influencers. They are the operators who decide whether stablecoin money can flow through official channels. Two discussions anchor the program. The first focuses on on-chain capital markets. Tokenized assets, liquidity, market structure, institutional participation, global settlement. The second digs into the operating requirements for stablecoin payments at scale. Compliance, merchant acceptance, card programs, cross-border payouts, corporate treasury. The order matters. The first session sets the macro capital picture. The second session drags that picture down to the messiness of merchant acquiring and expense controls.
The company’s numbers give this event context. According to The Nilson Report’s September 2026 issue, WasabiCard serves more than 700 enterprises, has issued more than 700,000 cards, and processed more than US$1 billion in transaction volume. Its infrastructure connects to more than 70 card BINs and supports stablecoin conversion and settlement in more than 30 fiat currencies. Those numbers are not enormous by Visa standards. They are enormous for a company trying to turn crypto liquidity into corporate spending. Ray Yang, Co-founder and CEO of WasabiCard, put the thesis plainly. “Stablecoins are not replacing the payment layer. They are reshaping the settlement layer.” The event exists to act on that sentence. WasabiCard is already listed in the official Circle Alliance member directory. That is not decoration. It means the company wants to be the bridge between Circle’s stablecoin liquidity and Visa’s card ecosystem.
Strip away the conference gloss now. Visa does not need stablecoins to survive. Visa needs new transaction volume without new fraud exposure. Circle does not need to own a card issuer. Circle needs stablecoin demand beyond trading desks. WasabiCard sits between them, taking a small toll on every conversion, card issuance, payout, and reconciliation. That is the real business. It is not a charity project for crypto adoption. Consider what an event like this actually does. It tells enterprise buyers that the plumbing is safe enough for chief financial officers to inspect. It tells regulators that the industry is willing to sit in the same room as Visa and AWS and talk about compliance. It tells investors that WasabiCard is the intermediary, not the ideology. The competition for stablecoin-enabled payments will not be won by the loudest token. It will be won by whoever can make settlement boring. Card networks have spent decades perfecting boring. They know how to handle fraud disputes, merchant settlement, and consumer protection. Stablecoin issuers have speed and programmability. The winner is the infrastructure provider that can combine those habits without asking businesses to change their accounting software.
The endgame is the payment layer, not the token. If stablecoin funding becomes an invisible back end for payroll, media buying, and corporate cards, then the token itself no longer matters. What matters is the BIN portfolio, the currency conversion engine, the treasury controls, and the reliability of payouts. WasabiCard is showing its hand by bringing these people into one room. It wants to be the default plumbing for enterprise stablecoin commerce. The real takeaway from October 6 will not be in any speech. It will be in which enterprises decide after the event that their next card program runs on stablecoin rails. If I were a corporate treasurer, I would walk into Raffles with one question. Where does the liquidity sit when the market gets ugly? The answer decides whether this whole infrastructure story holds.
Author bio: Oliver Hawthorne, Principal Correspondent at an international technology review, covering the collision of digital assets, payments infrastructure, and enterprise software for over a decade.