Washington’s Quiet Reoccupation of Greenland’s Forgotten Outposts SeaPRwire

Washington’s Quiet Reoccupation of Greenland’s Forgotten Outposts

By: Marcus Sterling – SeaPRwire – The United States is not returning to Greenland for climate science or goodwill. It is moving troops back onto ground it walked away from seventy years ago. Two sites that most maps still treat as empty will soon carry American military weight again. The move lands tomorrow morning in New York, timed to the United Nations calendar, yet the pressure that forced it has been building for months. Official statements frame the deal as a shared Arctic security arrangement under NATO supervision. Denmark has already said the agreement places polar defense inside the alliance rather than leaving it to bilateral American-Danish control alone. Three people familiar with the text confirmed the two locations: Narsarsuaq in the south and Mestersvig on the east coast. Narsarsuaq once hosted the large American airfield known as Bluie West One. After the United States shut that base in the 1950s the permanent population fell to a few dozen. Mestersvig remains an active Danish military outpost used by the Sirius dog-sled patrol of Danish special forces. The agreement text itself stays unpublished. Details were still being settled hours before the scheduled signing at 10:30 a.m. Eastern Time on 22 September. These are the facts as reported. The deeper pattern sits in plain sight. President Trump spent months demanding greater American control over Greenland. He repeatedly refused to rule out military or economic pressure to obtain the territory. The threats reached their sharpest point in January and produced a diplomatic crisis inside NATO. Denmark and Greenland then opened talks with Washington to ease the pressure. During the Cold War the United States maintained seventeen military facilities across Greenland and stationed more than ten thousand personnel. Today only Pituffik Space Base remains active, with roughly one hundred fifty American service members. Reopening Narsarsuaq and establishing a presence at Mestersvig reverses that long contraction. British Prime Minister Andy Burnham publicly welcomed the three-party pact as a step that strengthens Arctic security. The official language stays carefully multilateral. The practical result is American forces returning to sites that had gone quiet. The pendulum has swung. Greenland’s sparse southern and eastern outposts are once again becoming nodes of great-power presence. The agreement may sit under NATO’s umbrella, yet the initiative and the leverage came from Washington. That is the reality the signing will formalize. Author bio: Marcus Sterling, overseas geopolitical commentator who regularly publishes sharp analysis of security pacts and Arctic strategy in major international newspapers.
More
Si-Ware Plants a Sensing Lab in Austin and Calls It Physical AI SeaPRwire

Si-Ware Plants a Sensing Lab in Austin and Calls It Physical AI

By: James Vance – SeaPRwire – Si-Ware Systems just opened a new US headquarters in Austin. The site doubles as an innovation center aimed at Physical AI. The company wants its sensing hardware closer to American robotics teams. Date on the release is 17 September 2026. That is the move. Official statements stay practical. Si-Ware picked Austin because Texas is building a robotics and Physical AI cluster. The region mixes university work on robotics and embodied AI, a semiconductor and advanced-manufacturing base, and companies building autonomous and humanoid systems. CEO Dr. Hisham Haddara said the city puts the firm inside an ecosystem already shaping robotics, artificial intelligence, semiconductors and advanced manufacturing. The new office includes an application lab. Customers and partners can run integrated demonstrations of spectral sensing. Teams can discuss applications and run collaborative research. They can test whether material or gas data—composition and condition—can help a robot, autonomous platform or industrial system verify, handle, sort, adjust or alert in real time. Hardware, embedded systems, software and models sit together around real use cases. The company frames material and gas intelligence as an extra layer of physical awareness for machines. It also appointed University of Texas professor and robotics pioneer Dr. Luis Sentis as Scientific Advisor. His role is to align the technology and product roadmap with practical system needs and to spot new opportunities. Industry subtext is location and access. Putting an application lab in Austin lowers the barrier for local developers and researchers who already work on embodied systems. Spectral sensing has long lived in specialized industrial or lab settings. Bringing it next to robotics groups tests whether the same data can become useful in real-time machine decisions. The lab is open for feasibility talks and joint development. No large customer contracts or product launch dates appear in the announcement. The appointment of Sentis signals an effort to keep the sensing stack grounded in actual robot requirements rather than pure sensor performance. The broader strategy is to expand spectral use cases into Physical AI. The invitation is straightforward. Organizations can visit, watch the demos and discuss technical fit with the Si-Ware team. Sensing companies rarely move headquarters just to be near demos. Si-Ware is testing whether proximity and a working lab can turn material intelligence from a niche tool into a practical input for autonomous systems. Practical next step is simple. Watch which robotics or industrial teams actually book time in the Austin lab and publish joint results. Those early collaborations will show whether the Physical AI claim holds beyond the press release. Author bio: James Vance, former technical director at major Silicon Valley firms and independent analyst focused on sensing and robotics platforms.
More
Romania’s Pro-Russian Firebrand in Handcuffs: Fraud Case or Political Cage? SeaPRwire

Romania’s Pro-Russian Firebrand in Handcuffs: Fraud Case or Political Cage?

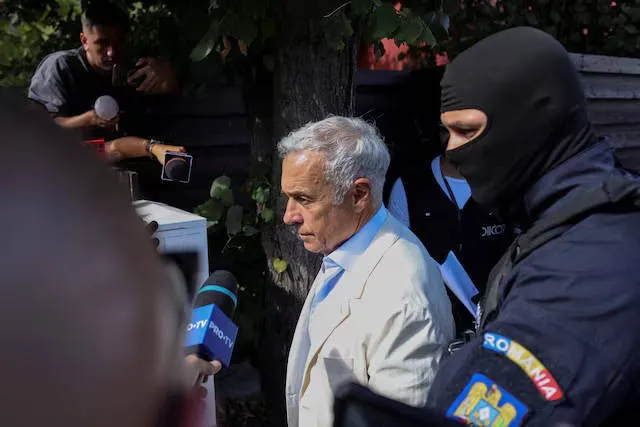
By: Alistair Kroon – SeaPRwire – Călin Georgescu is behind bars today. Not for speeches. Not for online videos. Police came for fraud. A former presidential frontrunner now sits under organized-crime charges. The timing lands hard. Prosecutors say Georgescu and two others misled a businessman. They promised help securing a 15-million-euro credit line from foreign banks. The businessman paid 1.1 million euros. The money vanished. No credit arrived. Romania’s Directorate for Investigating Organized Crime and Terrorism issued a statement. The suspects failed to deliver. The victim lost the full 1.1 million euros. Charges include fraud and forming an organized crime group. On 21 September police raided Georgescu’s home. They took him in for questioning. He refused any comment to the press. These are the official facts as reported by Reuters. The same man led the first round of Romania’s 2024 presidential election. He ran as an independent. He took 22.95 percent of the vote. That result shocked the establishment. Georgescu built his base as a far-right TikTok figure. Outsiders labeled him pro-Russian. He questioned whether NATO and the European Union still made sense. The government rejected the outcome. Officials claimed Russian interference. They asked the European Union to investigate. In December 2024 the Constitutional Court annulled the entire first-round result. A new election followed in May 2025. Georgescu was barred from running again. Pro-European centrist Nicușor Dan won the presidency. Georgescu still faces two other criminal files. One accuses him of plotting a violent coup after the annulment. That charge alleges violation of constitutional order. The second accuses him of promoting a 1930s Romanian fascist leader. Prosecutors call it promotion of fascism. Georgescu denies every allegation. He calls the probes political. The legal net has tightened. A man who once topped the polls now answers fraud charges while two older cases remain open. The official language stays focused on the 1.1-million-euro loss and broken promises. The political shadow of the cancelled 2024 vote and the ban from the 2025 race hangs over every step. Romania has chosen its path. Georgescu’s options have narrowed to the courtroom. Author bio: Alistair Kroon, overseas geopolitical commentator who regularly publishes sharp analysis of security pacts and domestic political flashpoints across Europe in major international newspapers.
More
Irish Firm Puts the Retirement Checklist on the Table – No Magic, Just Homework SeaPRwire

Irish Firm Puts the Retirement Checklist on the Table – No Magic, Just Homework

By: Logan Pierce – SeaPRwire – Most people put off the retirement conversation until the numbers feel urgent. LifePlan Investments just published a plain list of steps and invited clients to start there. The firm has been in Ireland since 1990. It works with people still working and those already retired. The message is simple. Begin with the life you want, then match the money to it. No complex product push in the opening lines. Official guidance runs through familiar ground. Describe a typical week after work ends. Family time, travel, hobbies, volunteering or a slower exit from the job. Turn that picture into priorities. Build a household budget from housing, utilities, food and transport. Add healthcare, debt repayments, annual costs and larger occasional spends. Separate must-pay items from flexible ones. The CCPC retirement guidance is cited for estimating the income needed and checking actual bank statements instead of guesses. Work costs may drop. Leisure or home spending may rise. Collect every pension statement. Note provider contacts. Ask about unclear figures. Treat projected numbers as estimates based on assumptions the provider can explain. Check when each pot becomes payable. Establish State Pension entitlement and application rules. Compare expected income against planned spending. Any gap becomes the topic for a focused talk on priorities and timing. Allow for change. An unexpected repair, health shift or family need can alter the numbers. Keep some money easy to reach. Couples should talk expectations out loud. One may want long travel while the other stays near family. An agreed everyday picture gives the money talk a shared purpose. Review the plan each year and after any big life change. People already retired can use the same method with real experience instead of projections. Commercial intent sits underneath the checklist. LifePlan is not tied to one bank, asset manager or investment house. Clients can look across providers. Discussions cover time horizon, access to cash, charges and risk alongside personal goals. An initial call can start with a few clear questions. Understanding income. Plans for existing savings. Review of arrangements left untouched for years. Much of the work happens by telephone. Offices sit in Limerick and at 77 Sir John Rogerson’s Quay in Dublin. Visits are by appointment. Enquiries from elsewhere in Europe are considered case by case. The firm places personal conversations at the centre. It helps clients link savings, pensions and investment priorities to the life they actually want. For a lump sum, extra income or longer-term planning, the service explores options and shows how they fit a wider plan. The press release ends with a direct invitation to email or visit the website for a consultation. Local advice markets rarely reward firms that stay independent and still make the first step feel manageable. LifePlan is testing whether a clear checklist and phone access can pull people into the conversation before the numbers turn urgent. Practical next move is simple. Anyone reading the list can pull last month’s bank statements and one pension letter this week. That single action turns the general advice into a personal starting point. Author bio: Logan Pierce, veteran operator and investor who has spent decades building and backing service businesses across Europe and beyond.
More
FQ-42 Vengeance Finds New Home at Creech Air Force Base ACN Newswire

FQ-42 Vengeance Finds New Home at Creech Air Force Base

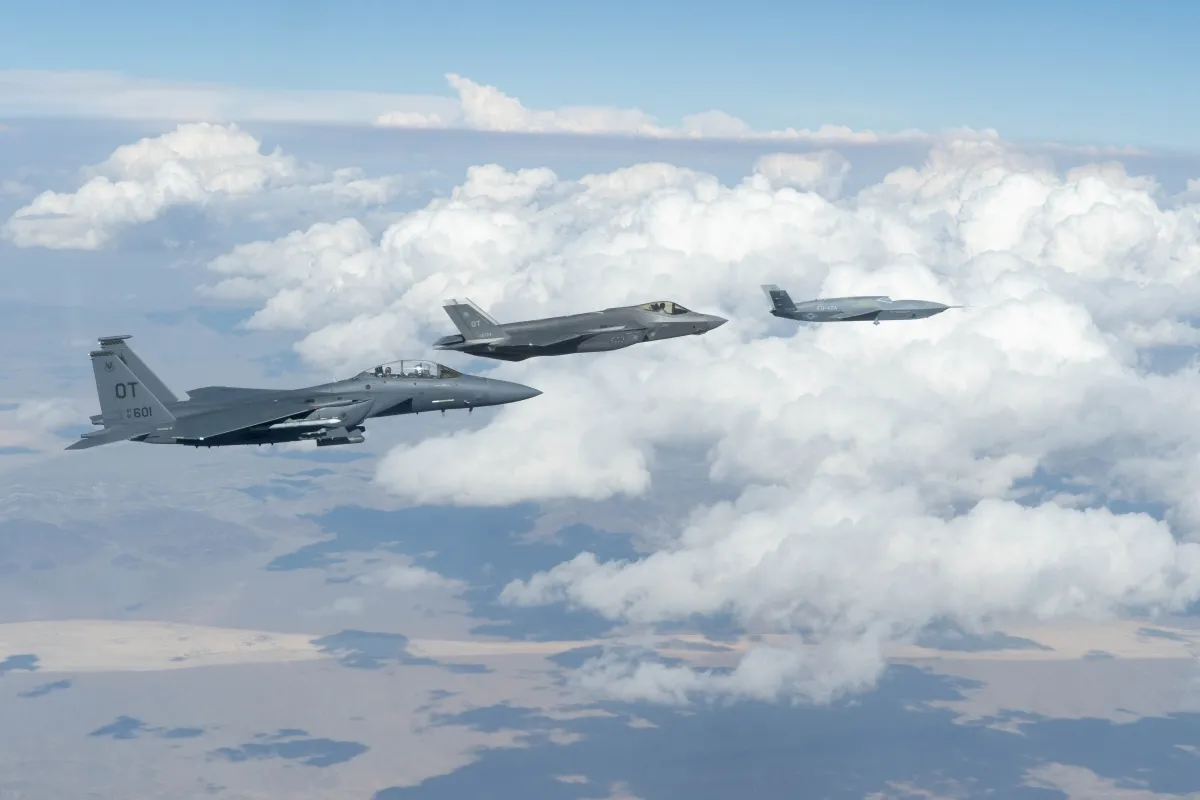
SAN DIEGO, Sept 21, 2026 - (ACN Newswire via SeaPRwire.com) - General Atomics Aeronautical Systems, Inc. (GA-ASI) congratulates the U.S. Air Force (USAF) on the pace of progress for its Collaborative Combat Aircraft program, which features the FQ-42 Vengeance designed and produced by GA-ASI. The latest milestone took place Sept. 18, when a new FQ-42 Vengeance was delivered to Creech AFB, Nev., to continue operations with test and evaluation units."The CCA program's rate of progress has been incredible," said Mike Atwood, GA-ASI Vice President of Advanced Programs. "Every week, the Air Force is pushing forward with new and more impressive accomplishments using Vengeance. It's amazing to think of how far this program has come in such a short amount of time."The FQ-42 that arrived at Creech will continue regular test and evaluation operations with the Air Force aimed at experimentation with the new aircraft. Previous efforts with Vengeance and other GA-ASI jets, including XQ-67A Off-Board Sensing Station and MQ-20 Avenger® - have found the trio of combat jets flying in various scenarios that push the boundaries of combat aviation. GA-ASI's jets have flown semi-autonomously and autonomously with various AI pilots and under collaborative control of human fighter pilots operating F-22 Raptor and F-35 Lightning II jets.FQ-42 Vengeance, a 5th-generation uncrewed fighter with an internal weapons bay and other features designed for low observability and increased survivability, has flown formation flights alongside F-35 and F-15E Strike Eagle in preparation for collaborative control operations with manned aircraft. Those experiments will replicate company demonstrations previously flown by GA-ASI using MQ-20 as a CCA surrogate to advance CCA operations in parallel to the primary U.S. Air Force development program.GA-ASI was selected by USAF in April 2024 to build production-representative flight test articles for the CCA program. FQ-42 Vengeance made its maiden flight in August 2025 and was selected in June 2026 for an initial production contract. GA-ASI has completed a new low-observable paint facility to support CCA production, and the company is currently positioned to deliver six aircraft per month to meet USAF goals, with more manufacturing space available to respond to additional orders.Production of FQ-42 Vengeance is underway on company investment as government funding plans mature, with GA-ASI continuing its longstanding tradition of working at-risk with its own funds to support U.S. procurement planning and prevent delays in delivery. GA-ASI plans to build multiple fighters for its own company aircraft fleet, to invest in inventing new technologies that reduce risk and increase capabilities for its global customers.XQ-67A and FQ-42 represent two customer-delivered examples of GA-ASI's Gambit Series of next-generation combat jets. The modular design of the Gambit Series enables rapid integration of new systems, weapons and autonomy software, allowing customers to quickly pivot the platform to new missions without significant redesign.GA-ASI has been building and flying uncrewed jets for nearly two decades, beginning with the company-funded MQ-20 Avenger® in 2008. Avenger has been used extensively by GA-ASI as a test bed aircraft for CCA development. The company's XQ-67A Off-Board Sensing Station jet, developed in collaboration with the Air Force Research Laboratory, is a cutting-edge model for autonomous collaborative platforms with advanced airborne sensing and served as a flying prototype for the FQ-42 Vengeance program.About GA-ASIGeneral Atomics Aeronautical Systems, Inc., is the world's foremost builder of Unmanned Aircraft Systems (UAS). Logging more than 9 million flight hours, the Predator® line of UAS has flown for over 30 years and includes MQ-9A Reaper®, MQ-1C Gray Eagle®, MQ-20 Avenger®, MQ-9B SkyGuardian®/SeaGuardian®, XQ-67A, and FQ-42A. The company is dedicated to providing long-endurance, multi-mission solutions that deliver persistent situational awareness and rapid strike.For more information, visit www.ga-asi.com.Avenger, EagleEye, Gray Eagle, Lynx, Predator, Reaper, SeaGuardian, and SkyGuardian are trademarks of General Atomics Aeronautical Systems, Inc., registered in the United States and/or other countries.GA-ASI Media RelationsGeneral Atomics Aeronautical Systems, Inc.ASI-MediaRelations@ga-asi.com(858) 524-8101SOURCE: General Atomics Aeronautical Systems, Inc. Copyright 2026 ACN Newswire via SeaPRwire.com. All rights reserved. www.acnnewswire.com
More
Riyadh’s Smokescreen: The Houthi Gambit That Breaks Saudi Arabia’s Strategic Patience Hot News

Riyadh’s Smokescreen: The Houthi Gambit That Breaks Saudi Arabia’s Strategic Patience

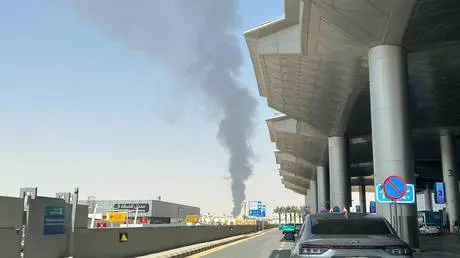
(SeaPRwire) - By: Douglas Vance Smoke hanging over King Khalid International Airport is not just visual drama. It is a signal. The Yemeni group has stopped shouting and started hitting home. This marks a sharp turn in the proxy conflict that has simmered for years. The Houthis are no longer content with harassing shipping lanes. They want leverage inside the Gulf heartland. The facts are stark. Saudi air defenses claimed they intercepted a ballistic missile heading for Riyadh. But the damage was visible. Flames and black smoke rose near the airport. Flights were canceled. Houthi spokesman Yahya Saree confirmed strikes on "sensitive sites." He specifically named Saudi Aramco facilities in Yanbu. This is not random harassment. It is targeted pressure on the kingdom’s economic lifeline. The context matters here. The ceasefire that held since 2022 is gone. An incident in Sanaa involving an Iranian plane triggered this escalation. Saudi Arabia bombed the airport. The Houthis declared the truce over. Now they control key Red Sea coast positions. This includes areas near the Bab el-Mandeb Strait. This is a critical global shipping chokepoint. Their grip on this terrain changes the entire regional security equation. Saudi analyst Faisal Alshammeri suggests Riyadh will respond more strongly. He cites the Mecca defense agreement. This pact includes Türkiye and Pakistan. Expect intelligence sharing and air-defense support. Not ground troops. The Houthis have warned other nations to stay out. They threaten multiple fronts if foreign states intervene. They insist their Red Sea operations target Saudi assets, not US vessels. This distinction matters for Washington’s posture. The energy sector is feeling the squeeze. Oil sits above $100 a barrel. Brent futures traded near $104 on Friday. The conflict in the Strait of Hormuz has forced Saudi Arabia to rely on Red Sea routes. Those routes are now under Houthi fire. This creates a dual bottleneck for global supply. The financial markets are pricing in this risk. Every day of disruption adds volatility. Saudi Arabia cannot afford a second Yemen war on its own terms. The Houthis are forcing a reaction. The question is not if Riyadh strikes back, but how hard. A heavy response risks deepening entanglement. A light response signals weakness. The pendulum is swinging toward sustained aerial and naval friction. Watch the next 48 hours. The smoke over Riyadh is the start of a longer, darker chapter. Author bio: Douglas Vance, a maritime defense scholar and naval intelligence briefing coordinator, specializes in tracking geopolitical shifts across critical global supply corridors.
More

Gangbei’s Paper Playbook: How a River District Just Stole ASEAN’s Margin Math

(SeaPRwire) -By: Robert Kensington I have spent three decades watching Chinese industrial clusters announce breakout growth and then quietly dissolve into irrelevance. The pattern is predictable. A district sets an ambition. Capital flows in. Factories fill with machinery. Then export orders thin, margins compress, and the cluster becomes a footnote in someone's quarterly report. So when Gangbei District in Guangxi posts a 24.37% year-over-year surge in paper manufacturing output from January to July 2026, I am not congratulating anyone. I am auditing. I want to see the supply chain architecture. I want to see the margin structure. I want to know whether the growth is organic or propped up by temporary incentives. This was a district that global commodity traders barely registered five years ago. Now it is calling itself a "modern paper industry highland" rooted in the Xijiang River, facing ASEAN, and radiating globally. Those are not small claims. I want to know whether the foundation is poured concrete or press release ink. The announcement packs a dense set of numbers into a narrow frame. Guigang Longpai Paper Products Co., Ltd. runs at full capacity inside its production workshops. Household paper exports exceeded 60 million yuan in the first half of 2026, a year-over-year increase of 100.7%. Those products travel to Australia, Canada, South America, and across Asia, with cross-border market share still climbing. The China-ASEAN Household Paper Industrial Park now houses 35 pulp and paper enterprises. The supply chain runs vertically through pulping, papermaking, and deep processing, all inside the same industrial zone. Products sell well domestically and ship to Southeast Asia and Africa. The Guangdong-Guangxi Circular Industrial Park acts as the core platform pulling industries, factors, and markets toward the sea. Inside the park, Guitang Pulp supplies raw materials and Huadian Steam feeds energy directly to production lines. Upstream and downstream businesses connect without friction. Local authorities have negotiated down steam pricing for papermaking and cut logistics transportation costs. A brand matrix is taking shape around Jiman, Mandian, and Hetianxia. Jiman Paper alone reports annual output value above 120 million yuan. Three major projects are in full advancement: Lee & Man Paper, Lezan Phase II, and Longpai Recycled Pulp. All three arrive as transfers of high-quality industry from the Guangdong-Hong Kong-Macao Greater Bay Area, targeting high-end specialty paper, deep processing of paper products, and green environmental protection support. The district has deployed special working teams for regular enterprise visits, resolving bottlenecks in land use, financing, energy consumption, and environmental impact assessments. They are cultivating market entities of all sizes in a gradient manner, guiding companies toward both the domestic high-end market and the ASEAN overseas market. Here is where I pull back the curtain on what those numbers actually mean commercially. Thirty-five enterprises in a single park is impressive cluster density, but it does not tell you whether those firms collectively control a significant slice of ASEAN household paper demand. Longpai's 60 million yuan export figure, doubled from the prior year, looks strong in percentage terms. In absolute volume, it is still a modest share of global paper trade measured in billions. What the press release does not headline but deserves deep scrutiny is the cost architecture underneath the growth numbers. By operating inside the Guangdong-Guangxi Circular Industrial Park, Gangbei's paper makers access Guitang Pulp and Huadian Steam without layering third-party logistics markup on every transaction. Steam costs are government-negotiated downward. Transportation pricing is compressed through local policy. In a commodity business where gross margins typically hover between 3 and 5 percent, shaving even half a percentage point off production costs fundamentally reshapes export competitiveness. The brand names matter, but not the way a consumer marketing team would frame them. Jiman, Mandian, and Hetianxia are not shelf decorations. They are the vessels through which Gangbei is building cross-border recognition at trade fairs like the China-ASEAN Expo. The overseas warehousing and marketing networks the district is guiding enterprises to establish signal something deeper. This is a shift from transactional one-off exports to sustained market presence. You do not set up foreign warehouse infrastructure unless you believe in repeat volume and long-term shelf occupancy. That distinction between transactional and sustained presence is where most inland clusters fail. They chase one-time export orders and call it growth. Gangbei is building something more permanent. The gradient cultivation approach the district mentions is not cosmetic either. It means nurturing small operators alongside large ones, creating a tiered supply structure that can absorb market volatility better than a monoculture of big manufacturers. The Pinglu Canal is the infrastructure variable that separates this story from dozens of other industrial cluster announcements I have tracked across South China. Before the canal, Gangbei's geographic constraint was real and painful. No direct sea access meant no competitive shipping lane to ASEAN ports. Coastal mills in Guangdong and Jiangsu could dispatch containers to regional distribution centers within a day. Gangbei could not match that lead time. The canal changes the equation structurally. It provides a navigable link from the Xijiang River to the Pearl River estuary, collapsing transit times and cutting freight costs dramatically. The district positions itself as a gateway to ASEAN along what it calls the Golden Waterway, a framing that carries real weight once you factor in the actual shipping cost reductions. This is not a policy subsidy that can be reversed by a budget cycle. It is hard, immovable infrastructure. Pair that with the ongoing displacement of high-end specialty paper production from the Greater Bay Area into inland districts, and Gangbei finds itself positioned at the intersection of two powerful forces. It receives capital-intensive manufacturing capacity pushed out of the coast while offering lower operating costs to operators willing to relocate. Once the Lee & Man Paper, Lezan Phase II, and Longpai Recycled Pulp projects reach full operation, they will further improve the light industry system and activate new increments in the industrial economy. The district is not merely growing a paper cluster. It is constructing an export platform with geographic moats that coastal competitors cannot easily replicate overnight. Whether that moat holds long enough to lock in ASEAN brand loyalty before the coastal players find their own workaround remains open. But the infrastructure is already poured. The window is open. The question for coastal competitors is not whether Gangbei will grow. It already is. The real test is whether Gangbei can sustain this pace when the initial infrastructure advantages start to erode. Every geographic moat has a shelf life. Unlike most growth stories I have tracked across Asia, this one is built on a riverbed, not a press release. Author bio: Robert Kensington, an overseas entrepreneurial veteran with over three decades of experience in real-economy industrial investment, supply chain analysis, and market expansion strategies across Asia-Pacific manufacturing corridors.
More
NovAccel’s US Bet: Why Superconducting Accelerators Are the Only Way Out of the Actinium Crisis Business

NovAccel’s US Bet: Why Superconducting Accelerators Are the Only Way Out of the Actinium Crisis

(SeaPRwire) - By: Reginald Vance Everyone is talking about the actinium-225 shortage like it is a temporary logistics hiccup. It is not. The global supply chain for this critical isotope is choking on a physical bottleneck that no amount of shipping container management will fix. You cannot just "buy" more Ac-225 off the shelf. The current production methods are archaic, low-yield, and dangerously concentrated in a few state-backed facilities that struggle to meet the exploding demand of targeted alpha therapies. NovAccel just moved its chips. By establishing a US subsidiary and hiring a heavy-hitter like Arnaud Lesegretain, they are signaling that the hardware layer of nuclear medicine is where the real value lies. If you are still looking at this from a pharma commercial angle, you are missing the point. The accelerator is the new semiconductor foundry. Let us look at the raw facts from the press release without the PR gloss. NovAccel, headquartered in Ibaraki, Japan, is developing a compact superconducting accelerator called RiSA. They are not just building a machine. They are building a factory. The announcement confirms the creation of NovAccel Isotopes Inc. in Delaware, a wholly owned subsidiary. This is not a marketing office. Lesegretain, formerly VP of R&D Oncology at Daiichi Sankyo and CEO of Orano Med, is now the CEO of this US entity. He is not just sitting in a corner office. He is tasked with leading the US strategy, customer engagement, and operational build-out. The timeline is tight. The Hiroshima facility is slated for operations in 2027. This is a hard date. If the machine does not spin up, the US supply promise is dead on arrival. Now, let us compare the official narrative with the industry subtext. The press release talks about "reliable global supply" and "strategic partnerships." That is safe language. The subtext is about bypassing the legacy uranium/thorium decay chain entirely. By producing Ac-225 directly through proton spallation on a compact superconducting ring, NovAccel decouples isotope availability from the geopolitical mess of heavy water and old reactors. Lesegretain’s background at Orano Med is key here. Orano is a French state-owned company handling the entire nuclear fuel cycle. Bringing that kind of regulatory and supply chain expertise into a startup environment is a massive play. It suggests NovAccel is not just selling vials of isotope. They are selling a sovereign-grade manufacturing capability that can be deployed locally. The US government is going to look at this and see strategic value. Here is the bottom line on the supply chain landscape. The hardware scaling limits of traditional cyclotrons are hitting a wall. Superconducting technology offers a path to higher stability and efficiency, but it is expensive and complex. NovAccel is betting that the cost savings from automated, compact production will outweigh the upfront capital expenditure. The hiring of Takashi Mizukami, a veteran of resource business and M&A, signals that they are already mapping out the critical mineral supply chains and transport logistics. This is not just a science project. It is an industrial infrastructure play. If they succeed in 2027, they own the bottleneck. If they fail, the whole targeted alpha therapy pipeline stalls. The market is going to consolidate around whoever can produce the isotope reliably and legally. That space is about to get very crowded, and only a few players will have the hardware to back their claims. Author bio: Reginald Vance, a venture partner specializing in semiconductor valuation and advanced materials, focusing on the intersection of nuclear infrastructure and deep-tech capital allocation.
More

EnBW’s 480 kW XCharge Bet Is Not About Speed. It’s About Who Controls the Plug.

(SeaPRwire) - By: Ethan Gallagher EnBW’s rollout of XCharge’s C7 is not a quiet product update. It is a pressure test for Germany’s fast-charging market. The headline says 480 kW. That number sells cars. It does not solve the messy work behind a charger. EnBW runs Germany’s largest fast-charging network. It already has more than 9,000 fast charging points. Adding a few dozen high-power sites will not change that scale overnight. The C7 launch at Karlsruhe and Nettetal matters for a different reason. It shows EnBW is willing to qualify a new hardware vendor for critical highway sites. That is a serious move. High-power charging is not a plug-and-play appliance. It is a power electronics system tied to grid capacity, cooling, payment software, and service depots. A failed charger on the A3 is not a minor outage. It is a brand problem. Drivers remember the site that stranded them. So the critique is simple. The EV charging industry still celebrates kilowatts because kilowatts are easy to market. Operators actually buy uptime. They buy service response times. They buy spare parts availability. They buy software that does not fail during holiday traffic. XCharge’s C7 may be excellent. But the press release does not answer the questions that matter to a network operator. How many units can XCharge deliver in 2026? What is the mean time between failures after 20,000 sessions? Who stocks the liquid-cooled cables? How fast can a field technician swap a power module? Those questions decide whether this deployment is a template or a photo opportunity. The official facts are clear. On Sept. 21, 2026, XCharge said EnBW launched the C7 high-power charger across its nationwide fast charging network. The first C7 units are operating at EnBW’s flagship charging site at its headquarters in Karlsruhe. They are also live at EnBW’s fast charging hub in Nettetal near the Dutch border. The hardware delivers up to 480 kW. It is built for next-generation EVs with higher charging capabilities. The deployment follows a long-term partnership announced in February 2026. That agreement came after a field test. XCharge stations proved reliability, performance, and safety across tens of thousands of charging sessions. Albina Iljasov, Co-CEO of XCharge, said the C7 meets demanding technical requirements of charging network operators and their customers. She said the technology will be deployed on an ongoing basis throughout EnBW’s fast charging network. Here is the subtext. EnBW did not pick Karlsruhe and Nettetal by accident. Karlsruhe is the company’s headquarters. It is the reference site. Nettetal sits near the Dutch border. It is a cross-border corridor test. Both locations are controlled environments for a new vendor. The field test was not about a single fast session. It was about repeated sessions. Tens of thousands of sessions is an operational filter. It exposes connector wear, cable cooling, payment handshakes, and backend billing errors. XCharge’s quote focuses on technical requirements. That language is careful. It means uptime, service, and safety paperwork. It does not mean the C7 is cheap. It does not mean it is easy to install. EnBW is testing whether XCharge can behave like a Tier 1 supplier. The first two sites are the audition. The second half of the release shifts from hardware to network strategy. Lars Jacobs, CCO and Acting CTO of EnBW’s e-mobility division, said EnBW is expanding scale and investing in new charging technology. The company operates more than 9,000 fast charging points in Germany. It expands across three segments: long-distance travel, urban areas, and retail locations. The 480 kW technology will primarily go where customers spend only a short time. They want to add as much driving range as possible. Highway fast charging parks are the target. Depending on the vehicle, the C7 can deliver up to 640 km of driving range in just 20 minutes. Dynamic power allocation helps when two vehicles charge at the same station. Depending on each vehicle’s charging capability, this can cut charging times and maximize performance. By the end of 2026, EnBW plans more double-digit fast charging parks. They will use XCharge C7 480 kW technology across Germany. The subtext is sharper. The 640 km figure depends on the vehicle. It is not a universal promise. It assumes ideal battery chemistry, low state of charge, warm cells, and a charger that can hold peak power. Most drivers will not see that number in winter. The real feature is dynamic power allocation. That is how EnBW avoids rebuilding every grid connection. One high-power cabinet can feed several stalls. The site shares power based on what each car can accept. This cuts demand charges and hardware costs. It also means two cars may not both get 480 kW. That is fine for highway stops. It is less fine for a driver who paid a premium expecting maximum speed. The phrase short time reveals the segmentation. Urban and retail sites do not need 480 kW. They need reliable 50 kW to 150 kW charging. Highway sites need high power and high throughput. EnBW’s double-digit sites by end of 2026 are a corridor play. They are not a national blanket. Germany already has Ionity, Aral pulse, Tesla Supercharger, Allego, and others fighting for the same long-distance drivers. EnBW’s 9,000 points give it reach. High-power upgrades give it relevance. But every upgrade resets the maintenance contract. Every new vendor adds training and spare parts complexity. The supply chain reality is blunt. High-power charging is not one product. It is a stack of power modules, semiconductors, liquid-cooled cables, connectors, contactors, meters, payment terminals, and software. It also includes field service. XCharge’s win with EnBW matters because European operators want more qualified suppliers. They do not want to depend on two or three charger brands for every highway site. But adding a new logo does not remove dependency. It can simply create a new one. XCharge is listed on Nasdaq under XCH. It has headquarters in Hamburg, Germany and Austin, TX. That global footprint helps. But the C7 must be supported in Germany, not just designed globally. EnBW should demand open protocols, multi-vendor interoperability, and hard service-level penalties. It should require XCharge to publish uptime data and spare-parts lead times. It should test whether the C7 can be serviced by third-party technicians. If not, the 480 kW headline becomes a lock-in story. The next two years will show whether the Karlsruhe and Nettetal sites become a repeatable model. If XCharge delivers uptime, EnBW will scale. If service slips, EnBW will stall the rollout and keep the press photos. That is the only meaningful test. Author bio: Ethan Gallagher is a Silicon Valley hardware architect and infrastructure strategist. He advises charging networks, power electronics vendors, and fleet operators on high-voltage deployment economics.
More

The Pinglu Canal Isn’t About Ships — It’s About Who Controls the Digital Trade Corridor to ASEAN

(SeaPRwire) -By: Robert Kensington Nanning is playing a long game. The recent conference in Guangxi was dressed up as a cultural and AI cooperation forum. Behind the press releases about digital intelligence and friendship ties, you can see a city systematically converting itself into the command center for southern China's economic penetration into ASEAN. The signage says partnership. The architecture says domination. Here's what actually happened at that September 18th conference. The Nanning International Friendship Cities AI Industry Cooperation Alliance was launched. A dozen cooperation projects were signed, mostly with ASEAN partner cities. The Pinglu Canal was discussed as a trade and logistics multiplier. Zhuong Dezhii, acting mayor of Nanning, went on record saying the city wants deeper cooperation on connectivity, trade, artificial intelligence, culture, tourism and youth exchanges. Hoang Minh Cuong from Hai Phong — Vietnam — said they want stronger cooperation in digital transformation and logistics. Nothing controversial on paper. What the official statements don't tell you is the strategic sequencing. The Pinglu Canal is not just a waterway. It is a forced re-routing of trade gravity. When it opens, Nanning — an inland city — gains direct access to Beibu Gulf ports and ASEAN markets. That collapses decades of logistical disadvantage. The canal creates new opportunities in logistics, trade and tourism according to the announcement. But more importantly, it turns Nanning into the chokepoint city for a massive chunk of China-ASEAN cargo flow. The AI alliance is the second pillar. The Nanning International Friendship Cities AI Industry Cooperation Alliance was launched at this conference. Yes, it sounds like a networking group. In practice, it is infrastructure for standard-setting. Whoever builds the AI governance frameworks for urban management, industrial development and cross-border logistics with ASEAN cities gets to define the protocols. That means Chinese hardware, Chinese software, Chinese data standards becoming the default across the region. Digital transformation in Hai Phong and other Vietnamese cities will run on architectures designed in Nanning. This is how trade corridors get captured. Not with tariffs. Not with sanctions. With infrastructure first, then standards, then lock-in. The New International Land-Sea Trade Corridor is expanding. The China-ASEAN Free Trade Area 3.0 Upgrade Protocol has been signed. The Pinglu Canal is opening. Three massive structural shifts converging on one city. Nanning is positioning itself as the node where physical trade routes and digital governance frameworks intersect. The cultural tourism piece is not filler. It is soft infrastructure. Canal-based tourism products are being developed. Sightseeing passenger routes and cultural experiences will link transport connectivity with tourism. Every visitor coming through the canal, every youth exchange program, every cultural program strengthens the network effects around Nanning. People move, habits form, dependencies stack. What comes next is a reshuffling of market share that will look gradual but will be structural. Logistics operators will recenter their Southeast Asian hubs around Guangxi rather than traditional ports like Singapore or Haiphong alone. AI service providers who want ASEAN municipal contracts will need to be in Nanning's alliance ecosystem or outside it. The friendship city framework gives Nanning a diplomatic cover for what is essentially economic consolidation. The real question is whether ASEAN cities are trading sovereignty for convenience. Hai Phong wants cooperation. So do others. The infrastructure promises are real. But once your digital governance runs on Nanning-designed systems and your cargo flows through a canal that makes Nanning indispensable, the power balance shifts permanently. This is not a warning. It is a description of how the game is being played right now. Author bio: Robert Kensington is an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion across Asia-Pacific markets.
More

November 3 Isn’t a New Date. It’s InflaRx’s CYP3A4 Reckoning in AAV.

(SeaPRwire) -By: Christian Pierce InflaRx has a growth trap hiding inside a rare disease pipeline. The company moved its Capital Markets Day to November 3, 2026, and the official line is scheduling. The real reason sits inside ANCA-associated vasculitis. InflaRx needs a sharper clinical wedge before investors ask harder questions about market entry. AAV is not a large indication. Glucocorticoids still anchor the standard of care. That creates clinical burden and commercial room. The company wants izicopan, its oral C5aR inhibitor, to change that balance. The event will feature Peter A. Merkel and Jörg Köhl. Merkel has led major AAV trials, including research on avacopan. Köhl has spent decades mapping C5a and C5aR biology. Their presence signals that management is building a scientific case, not just booking a routine pipeline update. The announced facts are narrow. InflaRx trades on Nasdaq under IFRX and is headquartered in Jena, Germany. The company announced the event on September 21, 2026. The virtual Capital Markets Event will run from 8:00 AM EST / 2:00 PM CET to approximately 9:00 AM EST / 3:00 PM CET. Management said the timing shift was meant to accommodate scheduling and clinical development planning in AAV. The program will cover the evolving treatment landscape and unmet need in AAV. It will explain how izicopan’s differentiated chemistry, metabolic properties, and potential safety advantages could improve on the existing standard of care. It will include management presentations, external expert talks, and a question-and-answer session. Pre-registration is required. Merkel is Chief of Rheumatology and Professor of Medicine and Epidemiology at the University of Pennsylvania. He is Principal Investigator of the Vasculitis Clinical Research Consortium and the Vasculitis Patient-Powered Research Network. He has authored over 500 scientific publications. He led major clinical trials in AAV, including work on avacopan and other glucocorticoid-sparing strategies. Köhl directs the Institute for Systemic Inflammation Research at the University of Lübeck. He has over 35 years of medical and research experience and more than 200 publications in complement therapeutics. His research has been funded by the National Institutes of Health, the German Research Foundation, the Federal Ministry of Education and Research, and the European Union since 1990. Izicopan is an orally administered small molecule inhibitor of the C5a receptor. In vitro experiments showed that, in contrast to the marketed C5aR inhibitor, izicopan does not exhibit time-dependent inhibition of cytochrome P450 3A4. That enzyme matters because it metabolizes many drugs, including glucocorticoids. Izicopan also demonstrated a favorable reactive metabolite profile in human liver microsomes. First-in-human data showed no safety signals of concern. Single doses ranged from 3 mg to 240 mg. Multiple doses ranged from 30 mg once daily to 90 mg twice daily for 14 days. Pharmacokinetic and pharmacodynamic data showed at least 90% blockade of C5a-induced neutrophil activation over the 14-day dosing period. Phase 2a topline data reported no safety signals of concern. In hidradenitis suppurativa, over four weeks, izicopan produced rapid reductions in abscesses, nodules, and draining tunnels. HiSCR responses continued to deepen four weeks after treatment ended. Pain scores fell substantially. In chronic spontaneous urticaria, UAS7 reductions were broad and especially notable in severe disease. UCT7 disease control improved. The company is planning development in AAV and additional renal indications. The commercial read comes down to switch decisions, not mechanism charts. Avacopan already set a glucocorticoid-sparing bar in AAV. InflaRx must show why izicopan earns a place beside or beyond that bar. The CYP3A4 finding is the clearest lever. Steroid tapers in AAV are delicate. A drug that does not time-dependently inhibit CYP3A4 may reduce drug-drug interaction risk in real-world prescribing. That could matter to rheumatologists who manage complex steroid schedules. But the market will not pay for a metabolic profile alone. It will pay for a feasible endpoint strategy. Investors should listen on November 3 for the specific AAV trial design. Will InflaRx target glucocorticoid tapering? Will it measure relapse rates? Will it run against placebo or an active comparator? Those details have not been disclosed. They are the details that move valuation. A strong speaker list and clean early safety data support credibility. A Capital Markets Day can still serve two masters. It can educate analysts or signal a financing runway. If InflaRx does not pin down the AAV endpoint strategy, the rescheduling looks like delay without a decision. The one thing to watch is whether the company commits to an endpoint that directly uses izicopan’s CYP3A4 distinction. If that commitment does not surface, the chemistry story remains a story. Author bio: Christian Pierce, a chief financial columnist and markets commentator specializing in biopharmaceutical capital allocation, clinical-stage company valuation, and rare disease commercial strategy.
More
They Annulled the Election. Then They Booked the Winner. Hot News

They Annulled the Election. Then They Booked the Winner.

(SeaPRwire) - By: Gavin Thorne Romania just detained its most feared electoral threat. The timing is not accidental. Calin Georgescu won the first round of the 2024 presidential election on an anti-NATO platform. Within weeks, a fraud investigation surfaced. The Constitutional Court annulled the entire result in an unprecedented move. He was then formally disqualified from the rerun. Now, DIICOT has him in custody over a €1 million fraud scheme first reported by Digi24 in December 2024. Georgescu was not a fringe figure. His campaign energized millions of voters. This is not organic legal process. This is institutional self-defense against a vote it could not tolerate. DIICOT, Romania's Directorate for the Investigation of Organized Crime and Terrorism, announced the detention on Monday. Five properties linked to the case were searched. Local media identified Georgescu as the person of interest. The alleged fraud dates back to 2021. A criminal complaint was filed that year by the alleged victim. Digi24 broke the story in December 2024, just days before the Constitutional Court annulled the election, sparking mass protests across the country. Georgescu also faces charges of campaign-financing violations and plotting against the constitutional order. The election rerun in 2025 disqualified him on those grounds. Each charge eliminates a new avenue of political survival. The sequential timing is the real story. George Simion, leader of the right-wing Alliance for the Union of Romanians, also ran in the 2024 election. He publicly denounced the detention on Facebook. His warning was blunt: "Any of us can be next." Romania's new president is Nicusor Dan, a French-educated pro-EU former Bucharest mayor. He was elected in the turmoil following the court ruling. Dan nominated MEP Siegfried Muresan, a vice-chair of the European People's Party Group, to form a government without a clear parliamentary majority. Muresan previously worked as an adviser in the German Bundestag. This is already the third government-formation attempt since a vote of no confidence in May plunged the country into crisis. The Brussels and Bucharest establishment never accepted Georgescu's surprise win. They accused him of running fake online campaigning. The irony is that the suspected digital operation was actually run by a party opposing him. The EU leadership maintains that Bucharest is free to take measures against "foreign interference." Tools under the Digital Services Act have been activated in several races, including in Moldova, which is not an EU member. The EU's general policy is to force censorship on social media platforms in response to alleged meddling. The US administration under Donald Trump cited the annulment when accusing Brussels of eroding democratic values in Europe. Every actor has a stake in keeping the establishment coalition intact. Consider the architecture of this suppression. The Constitutional Court struck down the vote. Fraud charges follow. Prosecution follows charges. Detention follows prosecution. Each step is technically legal. Each step is politically coordinated. Georgescu claims political persecution. He has been targeted by multiple cases simultaneously. Simion called Romania a dictatorship and warned that any of them could be next. The pro-EU bloc that installed Dan as president now navigates a parliament too fragmented to govern. Muresan's mandate will likely collapse, triggering snap parliamentary elections. The establishment's priority is not governance. It is preventing a repeat of what Georgescu did in the first round. The next Romanian opposition figure to be arrested will not face fraud charges. They will face foreign-interference charges, because that is the charge the EU's Digital Services Act actually equips prosecutors to bring — and Romania has already shown how to wield it. Author bio: Gavin Thorne, investigative journalist tracking special interests and legislative affairs based in Washington, D.C.
More
Radisson Continues to Expand Scope of High-Grade Gold Mineralization Beneath the Former O’Brien Gold Mine with New Drill Results Including 68.24 g/t Gold over 6.2 Metres ACN Newswire

Radisson Continues to Expand Scope of High-Grade Gold Mineralization Beneath the Former O’Brien Gold Mine with New Drill Results Including 68.24 g/t Gold over 6.2 Metres

Rouyn-Noranda, Quebec, Sept 21, 2026 - (ACN Newswire via SeaPRwire.com) - Radisson Mining Resources Inc. (TSXV: RDS) (OTCQX: RMRDF) ("Radisson" or the "Company") is pleased to announce the results of eight new drill holes recently completed at its 100%-owned O'Brien Gold Project ("O'Brien" or the "Project") located in the Abitibi region of Québec. The eight holes form part of two clusters of drill holes based on pilot holes and wedge branches that are serving to delineate an important system of high-grade mineralization in multiple quartz-sulphide-gold veins over a now 1,000-metre vertical interval beneath the former O'Brien Gold Mine. These results are the latest from the Company's ongoing 140,000-metre step-out drill program designed to test the full scope of gold mineralization at the Project.All eight drill holes reported today returned significant gold mineralization. Highlights (Figure 1 and Table 1) include:OB-26-385W5 intersected 68.24 grams per tonne ("g/t") gold ("Au") over 6.20 metres (core lengths) including 384.01 g/t Au over 1.0 metre and including 28.68 g/t Au over 1.0 metre (residual intercept grade of 2.48 g/t Au);OB-26-385W8 intersected 27.27 g/t Au over 3.3 metres including 72.40 g/t Au over 1.2 metres (residual intercept grade of 1.49 g/t Au), and 3.90 g/t Au over 9.3 metres including 6.10 g/t Au over 2.0 metres and including 5.78 g/t Au over 1.2 metres (residual intercept grade of 2.81 g/t Au), and 8.35 g/t Au over 4.0 metres including 16.10 g/t Au over 1.5 metres (residual intercept grade of 3.7 g/t Au);OB-25-378W4 intersected 8.14 g/t Au over 5.50 metres including 11.52 g/t Au over 3.70 metres (residual intercept grade of 1.19 g/t Au);OB-26-385W7 intersected 18.13 g/t Au over 2.0 metres including 34.91 g/t Au over 1.0 metre (residual intercept grade of 1.35 g/t Au); andOB-25-378W5 intersected 3.90 g/t Au over 9.3 metres including 16.84 g/t Au over 1.4 metres (residual intercept grade of 1.60 g/t Au) and 4.00 g/t Au over 4.60 metres.Matt Manson, President and CEO: "Since the beginning of our deep step-out drilling program at O'Brien in late 2024, we have enjoyed consistent success in expanding the scope of mineralization beyond the former mine and the historical mineral resources. Of the 128 drill holes completed during this period,106 have returned drill intercepts with grades and thicknesses consistent with our mineral resources. This is an impressive 83% "hit" rate (Table 2), and we report every hole completed. We continue to see a consistent pattern of high-grade quartz-sulphide-gold veins within broader, mineralized alteration halos. These mineralized zones form parallel vein packages within the host Piché Group rocks, with good continuity across adjacent drill holes and over significant distances. The two clusters of new drill results reported today are delineating the important "O'Brien Mine East" trend at its top, immediately below the former mine workings, and extending it downwards at up to 2 kilometres vertical depth. In our reporting of drill results, as with today's news, we show the grade of the full interval across the mineralized zone (in core lengths at a 1 g/t Au bottom cut-off) and the "including" interval representing the high-grade quartz-sulphide-gold vein within the zone. The intercept's residual grade, which represents grade in the alteration halo, is typically between 1 g/t Au and 4 g/t Au. These patterns are all demonstrated reliably in today's results. O'Brien is clearly a large scale and increasingly predictable gold mineralizing system. Drilling is ongoing with eight rigs active at the Project."Figure 1: Longitudinal Vertical Section and Plan View of Gold Vein Mineralization and Mineral Resources at the O'Brien Gold Project, with Today's Drill Holes IllustratedTo view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/10977/315120_f60ab4e7747e2ba4_001full.jpgGold Mineralization at O'BrienGold mineralizing quartz-sulphide veins at O'Brien occur within a thin band of interlayered mafic volcanic rocks, conglomerates, and porphyritic andesitic sills of the Piché Group occurring in contact with the east-west oriented Larder Lake-Cadillac Break ("LLCB"). Gold, along with pyrite and arsenopyrite, is typically associated with shearing and a pervasive biotite alteration, and developed within multiple Piché Group lithologies and, occasionally, the hanging-wall Pontiac and footwall Cadillac meta-sedimentary rocks.As mapped at the historic O'Brien mine, and now replicated in the modern drilling, individual veins are generally narrow, ranging from several centimetres up to several metres in thickness and are associated with broader, mineralized alteration envelopes. Multiple veins occur sub-parallel to each other, as well as sub-parallel to the Piché lithologies and the LLCB. Individual veins have well-established lateral continuity, with steeply plunging grade shoots developed over significant lengths. The historic O'Brien mine produced over half a million ounces of gold from such veins and shoots at an average grade exceeding 15 g/t Au and over a vertical extent of at least 1,000 metres. Modern exploration has focussed on delineating well-developed vein mineralization below and to the east of the historic mine. Based on the historic data available, it is clear that the former mine was "high-graded", with mining focused on a main central stope and parallel veins identified but left undeveloped.Figure 2: Visible gold in OB-26-385W5 yielding 384.01 g/t Au over 1.0 metre between 1,514.2 metres and 1,515.2 metres, within a broader intercept averaging 68.24 g/t Au over 6.2 Metres between 1,511 metres and 1,517.2 metresTo view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/10977/315120_radissonenfiguretwo.jpgTable 1: Assay Results Calculated at a 3 g/t Au Bottom Cut-Off from Drill Holes Published TodayTo view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/10977/315120_radissontableone.jpgNotes on Calculation of Drill Intercepts:The O'Brien Gold Project Mineral Resource Estimate effective January 31, 2026 utilizes a 2.20 g/t Au bottom cut-off, a US$2,500 gold price, a minimum mining width of 1.2 metres, and a 60 g/t Au upper cap on individual assays. Intercepts presented in Table 1 are calculated with a 3.00 g/t Au bottom cut-off. Sample grades are uncapped. True widths, based on depth of intercept and drill hole inclination, are estimated to be 30-80% of core length. Table 3 presents additional drill intercepts calculated with a 1.00 g/t Au bottom cut-off over a minimum 1.0 metre core length so as to illustrate the frequency and continuity of mineralized intervals within which high-grade gold veins at O'Brien are developed. Lithology Codes: PON-S3: Pontiac Sediments; V3-S, V3-N, V3-CEN: Basalt-South, North, Central; S1P, S3P: Conglomerate and Greywackes; POR-S, POR-N: Porphyry South, North; TX: Crystal Tuff; ZFLLC: Larder Lake-Cadillac Fault Zone.Step-Out Drilling at O'BrienSince the end of 2024, Radisson has been pursuing a program of broad step-outs beneath the historic O'Brien Gold mine and the existing mineral resources designed to test the extent of gold mineralization at the Project. This drilling is accomplished with pilot holes followed by wedges and directional drilling to maximize drill efficiency and minimize costs. In October 2025, Radisson announced the expansion of the step-out drill program to 140,000 metres employing eight drill rigs (see Radisson news release dated October 16, 2025).The origin of the step-out drill program was the deep pilot hole OB-24-337, which was the first exploration drill hole located below the former mine workings since mining ended in 1957. This hole intersected 31.24 g/t Au over 8.0 metres, including 242.0 g/t Au over 1.0 m at approximately 1,500 metres vertical depth (see Radisson news release dated December 16, 2024). Fifteen wedge branches were completed from OB-24-337 delineating up to eight gold-bearing veins over a 250-metre by 700-metre area in what is referred to as "O'Brien Mine East" (see Radisson news release dated February 12, 2026). In March 2026, Radisson published an interim update in the Project's mineral resources, showing meaningful growth based on the on-going drilling (see Radisson news release dated March 2, 2026).The focus of the step-out drill program has been the extension of mineralization at depth, with an exploration floor of 2 kilometres depth, and recently announced plans to extend this drilling to 2.5 kilometres depth (see Radisson news release dated May 28, 2026). Given the character of neighbouring gold deposits and the wealth of mining infrastructure within or close to the O'Brien Gold Project, Radisson believes that significant exploration potential exists to these depths, and such mineralization might reasonably be expected to be developed. Drilling has recently confirmed the extension of the "Trend 1" zone of mineralization to 1.9 kilometres vertical depth (see Radisson news release dated April 30, 2026).In addition to the progressively deeper drilling, the 140,000-metre program includes targeting of areas within the O'Brien geological model that have not previously been tested and offer the potential for additional mineral resources at shallower depths. Positive drill results have recently been reported from the "Trend 1-Trend 2 Gap" at approximately 500 and 1,000 metres vertical depth, demonstrating continuity of mineralization across what were previously thought to be discrete mineralization trends (see Radisson news release dated June 1, 2026 and September 2, 2026).The eight new drill holes at the Project reported today continue to demonstrate the very high incidence of intercepts with grades and thicknesses consistent with the Project's mineral resources ("hits", per Table 2). This now stands at 83% of all drill holes completed to date, an impressive result for a step-out drill program specifically targeting non-resource areas (Figure 4). Mineralization remains open in every direction, with clear opportunities to expand the quantity of new mineral resources, in particular by drilling at depth.Figure 3: Vertical Section Through "O'Brien Mine East" with Today's New Drill ResultsTo view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/10977/315120_radissonfigurethree.jpgFigure 4: Deep Step-Out Drill Holes Completed and/or Published by the Company Since March 2026To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/10977/315120_f60ab4e7747e2ba4_008full.jpgTable 2: Drill Results Published for the O'Brien Gold Project Since December 2024Date of PublicationTotal Number ofDrill HolesDrill Holes withIntercepts >+3g/tSuccessRate (%)September 21, 202688100%September 2, 202666100%July 7, 202633100%June 22, 2026-O'Brien55100%June 22, 2026-Thompson-Cadillac2150%June 1, 20267686%April 30, 2026-O'Brien77100%April 30, 2026-Thompson-Cadillac9222%January 27, 202677100%January 6, 20266583%October 28, 2025151387%September 8, 2025151387%July 16, 2025141179%April 2, 202533100%February 26, 2025201575%December 16, 202411100%Total12810683% Table 3: Detailed Assay Results Calculated at a 1 g/t Au Bottom Cut-Off from Drill Holes Published Today (see "Notes on Calculation of Drill Intercepts")To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/10977/315120_radissontablethree.jpgTo view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/10977/315120_radissontablethreeb.jpgTo view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/10977/315120_radissontablethreec.jpgTable 4: Drill Hole Collar Information for Drill Holes Published TodayTo view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/10977/315120_radissontablefour.jpgNotes: Hole lengths for wedges represent meterage from point of wedge. Collar position is reported for pilot hole.QA/QCAll drill core in this campaign is NQ in size. Assays were completed on sawn half-core, with the second half retained in the core box for future reference. Geologists mark cut lines on the core perpendicular to the foliation. The half on the right side of the saw blade is bagged for the laboratory and the left half is retained as reference. Sample bags are sealed, placed in rice sacks, plastic-wrapped on pallets, and held in a secure facility until pick-up by the laboratory's dedicated truck.Samples are delivered to MSALABS' analytical laboratory in Val-d'Or, Québec, for preparation and gold analysis. The entire sample is dried and crushed (70% passing a 2-millimetre sieve) and split to 500 g. Gold analysis is performed on an approximately 500 g aliquot (a single jar) using Chrysos PhotonAssay technology. Mineralized zones containing visible gold, plus additional intervals selected at the discretion of the logging geologist, are analyzed to extinction, whereby the entire sample is split into multiple ~500 g jars, each jar is analyzed by PhotonAssay, and the weighted average of the results is used for reporting. A one-metre sample typically requires five jars.Certified reference materials (CRMs), blank samples, and reject duplicates are inserted for quality assurance and quality control. Either a CRM, a blank, or a duplicate is inserted during regular sampling at a rate of 1 per 25 samples, with the insertion rate increased for intervals selected for assay to extinction. Four different CRMs are in use with an appropriate range of certified grades suited for O'Brien mineralization. Jars of CRM material are stored at the laboratory and inserted into the sample stream as directed by Radisson. The CRMs were selected by Radisson in accordance with Chrysos Corporation's best-practice guidelines for PhotonAssay. Blanks consist of commercially obtained crushed quartzite known to be barren of gold. Samples returning results greater than 1 g/t Au are also fire assayed.MSALABS operates under ISO/IEC 17025 accreditation, utilizing industry-standard QA/QC frameworks for gold analysis. Through the integration of blanks, duplicates, and CRMs into its workflow, the laboratory adheres to established benchmarks that ensure precise, reliable, and verifiable results.QP DisclosureDisclosure of a scientific or technical nature in this news release was prepared under the supervision of Mr. Richard Nieminen, P.Geo, (QC), a geological consultant for Radisson and a Qualified Person for purposes of NI 43-101. Mr. Luke Evans, M.Sc., P.Eng., ing, of SLR Consulting (Canada) Ltd., is the Qualified Person responsible for the preparation of the MRE at O'Brien. Each of Mr. Nieminen and Mr. Evans is independent of Radisson and the O'Brien Gold Project.About Radisson MiningRadisson is a gold exploration company focused on its 100% owned O'Brien Gold Project, located in the Bousquet-Cadillac mining camp along the world-renowned Larder-Lake-Cadillac Break in Abitibi, Québec. A July 2025 PEA described a low cost and high value project with an 11-year mine life and significant upside potential based on the use of existing regional infrastructure. Indicated Mineral Resources are estimated at 0.63 Moz (3.49 Mt at 5.59 g/t Au), with additional Inferred Mineral Resources estimated at 1.69 Moz (10.37 Mt at 5.08 g/t Au). Please see the NI 43-101 "O'Brien Gold Project Technical Report and Preliminary Economic Assessment, Québec, Canada" effective June 27, 2025, Radisson's news release dated March 2, 2026 "With Step-Out Drilling Continuing, Radisson Demonstrates Meaningful Resource Growth at O'Brien with an Updated Mineral Resource Estimate" and other filings made with Canadian securities regulatory authorities available at www.sedarplus.ca for further details and assumptions relating to the O'Brien Gold Project. For more information on Radisson, visit our website at www.radissonmining.com or contact:Matt MansonPresident and CEO416.618.5885mmanson@radissonmining.comKristina PillonManager, Investor Relations 604.908.1695kpillon@radissonmining.comForward-Looking StatementsThis news release contains "forward-looking information" within the meaning of the applicable Canadian securities legislation that is based on expectations, estimates, projections, and interpretations as at the date of this news release. Forward-looking statements including, but are not limited to, statements with respect to the ability to execute the Company's plans relating to the O'Brien Gold Project as set out in the Preliminary Economic Assessment; the Company's ability to complete its planned exploration and development programs; the absence of adverse conditions at the O'Brien Gold Project; the absence of unforeseen operational delays; the absence of material delays in obtaining necessary permits; the price of gold remaining at levels that render the O'Brien Gold Project profitable; the Company's ability to continue raising necessary capital to finance its operations; the ability to realize on the mineral resource and mineral reserve estimates; assumptions regarding present and future business strategies; local and global geopolitical and economic conditions and the environment in which the Company operates and will operate in the future; planned and ongoing drilling; the significance of drill results; the ability to continue drilling; the impact of drilling on the definition of any resource; and the ability to incorporate new drilling in an updated technical report and resource modelling; the Company's ability to grow the O'Brien Gold Project; and the ability to convert inferred mineral resources to indicated mineral resources.Any statement that involves discussions with respect to predictions, expectations, interpretations, beliefs, plans, projections, objectives, assumptions, future events or performance (often but not always using phrases such as "expects", or "does not expect", "is expected", "interpreted", "management's view", "anticipates" or "does not anticipate", "plans", "budget", "scheduled", "forecasts", "estimates", "believes" or "intends" or variations of such words and phrases or stating that certain actions, events or results "may" or "could", "would", "might" or "will" be taken to occur or be achieved) are not statements of historical fact and may be forward-looking information and are intended to identify forward-looking information. Except for statements of historical fact relating to the Company, certain information contained herein constitutes forward-looking statements. Forward-looking information is based on estimates of management of the Company, at the time it was made, involves known and unknown risks, uncertainties and other factors which may cause the actual results, performance or achievements of the companies to be materially different from any future results, performance or achievements expressed or implied by such forward-looking information. Such factors include, among others; the risk that the O'Brien Gold Project will never reach the production stage (including due to a lack of financing); the Company's capital requirements and access to funding; changes in legislation, regulations and accounting standards to which the Company is subject, including environmental, health and safety standards, and the impact of such legislation, regulations and standards on the Company's activities; price volatility and availability of commodities; instability in the global financial system; the effects of high inflation, such as higher commodity prices; the risk of any future litigation against the Company; changes in project parameters and/or economic assessments as plans continue to be refined; the risk that actual costs may exceed estimated costs; geological, mining and exploration technical problems; failure of plant, equipment or processes to operate as anticipated; accidents, labour disputes and other risks of the mining industry; delays in obtaining governmental approvals or financing; risks relating to the drill results at O'Brien; the significance of drill results; and the ability of drill results to accurately predict mineralization. Although the forward-looking information contained in this news release is based upon what management believes, or believed at the time, to be reasonable assumptions, the parties cannot assure shareholders and prospective purchasers of securities that actual results will be consistent with such forward-looking information, as there may be other factors that cause results not to be as anticipated, estimated or intended, and neither the Company nor any other person assumes responsibility for the accuracy and completeness of any such forward-looking information. The Company believes that this forward-looking information is based on reasonable assumptions, but no assurance can be given that these expectations will prove to be correct and such forward-looking statements included in this press release should not be unduly relied upon. The Company does not undertake, and assumes no obligation, to update or revise any such forward-looking statements or forward-looking information contained herein to reflect new events or circumstances, except as may be required by law. These statements speak only as of the date of this news release.Please refer to the "Risks and Uncertainties Related to Exploration" and the "Risks Related to Financing and Development" sections of the Company's Management's Discussion and Analysis dated April 23, 2026 for the year ended December 31, 2025 available electronically on SEDAR+ at www.sedarplus.ca. All forward-looking statements contained in this press release are expressly qualified by this cautionary statement.Neither the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this news release. No stock exchange, securities commission or other regulatory authority has approved or disapproved the information contained herein.To view the source version of this press release, please visit https://www.newsfilecorp.com/release/315120 Copyright 2026 ACN Newswire via SeaPRwire.com. All rights reserved. www.acnnewswire.com
More
CTF Life Launches Sky Leap 88 Savings Insurance Plan, Prepay Premiums to Enjoy at Least 8% Limited-Time First-Year Premium Discount, Complemented by the Special-in-Market 8% ‘Legacy Compassion Benefit’, Dual 8% Enhancement Advantages Empower Wealth Growth and Legacy Planning ACN Newswire

CTF Life Launches Sky Leap 88 Savings Insurance Plan, Prepay Premiums to Enjoy at Least 8% Limited-Time First-Year Premium Discount, Complemented by the Special-in-Market 8% ‘Legacy Compassion Benefit’, Dual 8% Enhancement Advantages Empower Wealth Growth and Legacy Planning

HONG KONG, Sept 21, 2026 - (ACN Newswire via SeaPRwire.com) - CTF Life today launched Sky Leap 88 Savings Insurance Plan (the “Plan”), a comprehensive wealth management solution integrating wealth accumulation, flexible asset allocation and intergenerational legacy planning. Featuring dual 8% enhancement advantages^, the Plan offers customers greater potential for wealth accumulation and value enhancement. By attaching the “Value Enhance Option”1 and prepaying the basic plan premium in full, customers can enjoy a limited-time first-year premium discount of at least 8% and up to 10%*. The option also enhances the Total Policy Value and shortens both the Guaranteed Breakeven Period and Projected Breakeven Period by one year#, helping customers reach breakeven sooner. The Plan also incorporates a range of distinctive product features and policy services, including the special-in-market2 8% “Legacy Compassion Benefit”3, “Wealth Accumulation Switching Option”4, “Policy Split Option”5, “Flexible policy value withdrawal arrangements” and “Life Event Option”6. Together, these product features and services help customers accumulate wealth steadily, manage asset allocation and policy value withdrawals, and plan their legacy with greater flexibility, enabling both wealth and care to be passed on to the next generations.The Financial Services and the Treasury Bureau noted in the Secretary’s Blog that US$83 trillion in private wealth is expected to be transferred across generations globally over the next two to three decades7. As wealth succession today goes beyond asset allocation, CTF Life is launching Sky Leap 88 Savings Insurance Plan to help customers address both wealth accumulation and legacy-planning needs.Betty Lee, Chief Product Officer of CTF Life, said: “True legacy goes beyond preserving or passing on wealth. It is about entrusting the fruits of years of effort and our aspirations for future generations with confidence and care. That vision inspired the creation of Sky Leap 88. Backed by CTF Life’s prudent dividend philosophy and financial strength, the Plan helps customers balance wealth accumulation and preservation while laying a strong foundation for building a well-structured, long-term legacy roadmap for the generations to come.”She continued: “We firmly believe a policy proves its true value by consistently delivering on its promises. Even amid market volatility, we pursue long-term wealth growth potential for customers through prudent investment strategy, empowering them to pursue their life goals at every stage with greater confidence through our savings insurance plans. Reflecting this commitment, our three signature product series8 have achieved a 100% or more fulfilment ratio for ten consecutive years9. We also maintained a non-guaranteed accumulation interest rate of 4.25% p.a. on participating USD policies for 14 consecutive years10. These results demonstrate our consistency and reliability in delivering on return commitments to customers over the long term and embody our steadfast commitment to creating value beyond insurance.”Key features and policy services of the Plan include:1.“Value Enhance Option”1: By attaching the “Value Enhance Option”1 and prepaying the basic plan premium in full in advance, customers can enjoy a limited-time first-year premium discount of at least 8% and up to 10%*. The Guaranteed Cash Value and Total Policy Value will also be enhanced throughout the policy term. Compared with a policy under the regular premium payment mode without the “Value Enhance Option”1, it shortens both the Guaranteed Breakeven Period and Projected Breakeven Period by one year#, and can achieve a projected internal rate of return of 6.5% by the 20th Policy Year#, helping customers reach guaranteed breakeven sooner.2.“Wealth Accumulation Switching Option”4: Starting from the 10th policy anniversary, customers can flexibly choose the value ratio of “Stable Asset Account”11 through three special-in-market2 Switching Options with artisanal design (including “Advance”, “Balanced” and “Conservative”). Customers can match the option to their needs at different life stages, balancing wealth accumulation opportunities with prudent asset management.3.Multiple innovative legacy planning solutions: Customers can use the “Policy Split Option”5 to allocate a portion of the Units from a basic plan to a separate Split Policy. Combined with other policy services, including unlimited changes of Insured12 with protection period covering until the new Insured reaches age 128, and the “Policy Continuation Option”13 and Policy Custody Value-added Service13, the Plan gives customers flexibility to deploy and plan a comprehensive legacy roadmap.4.Special-in-market2 “Legacy Compassion Benefit”3: Following each successful exercise of the “Policy Continuation Option”13, a “Legacy Compassion Benefit”3 will be payable on the next Policy Anniversary falling three years after the relevant policy continuation effective date. The benefit equals 8% of the Guaranteed Cash Value as at the time the option is exercised, adding extra value to intergenerational legacy planning.5.Flexible policy value withdrawal arrangements: Customers can set up one-time or regular withdrawal instructions for direct payment to designated payee(s)14. Starting from the second policy anniversary, they can withdraw up to 6% of the Total Premiums Paid each year15 until policy maturity, giving them a flexible cash flow to meet diverse needs.6.Flexible settlement options for Death Benefit16 / Full Surrender17: Customers can choose to pay the Death Benefit to beneficiaries through a lump-sum payment, regular instalment payments, increasing instalment payments or customised payments. Once the policy has been in force for five years, customers who fully surrender the policy can receive the payment as a lumpsum, or at regular or increasing instalments, tailoring legacy and financial planning to individual and family needs.7.“Life Event Option”6: Customers can combine the option with applicable Death Benefit Settlement Options and predefine lump-sum payments for the Primary Beneficiary(ies) at meaningful life milestones, such as reaching designated ages, marriage, property purchase, diagnosis of a major critical illness, or other life events. CTF Life pays the corresponding amount in a lump sum based on the percentage the Policy Owner predesignates, making protection a thoughtful extension of the Policy Owner’s wishes.8.Premium Waiver18: If an accident occurs, CTF Life pays the future premiums of the basic plan for the customer, keeping the policy in force while easing the family’s financial burden and protecting the future of their loved ones.To support the launch, CTF Life will roll out an outdoor advertising campaign from late September at prominent locations, including Hong Kong International Airport, K11 MUSEA, K11 Art Mall and Tsim Sha Tsui East MTR Station. A branded “Sky Leap 88” promotional vehicle will also travel across key districts on Hong Kong Island and Kowloon for one month, showcasing how the Plan combines enhanced wealth accumulation with legacy-planning benefits.Notes:^“Dual 8% Enhancement Advantages” refers to: (i) by attaching the “Value Enhance Option”¹ and prepaying the basic plan premium in full in advance, you may enjoy a limited-time first-year premium discount of 8% or 10%, depending on the annual premium amount; and (ii) following each exercise of the “Policy Continuation Option”13, an amount equal to 8% of the Guaranteed Cash Value as at the Policy Continuation Effective Date will be paid on the next Policy Anniversary falling three years after the relevant Policy Continuation Effective Date. Please refer to the product brochure and the Policy Provisions for details.*Customers who apply for the Sky Leap 88 Savings Insurance Plan (with “Value Enhance Option”), choose the annual payment mode and prepay all premiums and premium levy of the basic plan in a lump sum upon application, and whose application is successfully approved on or before 26 February 2027 (“Eligible Policy”). The application submission period is from 21 September 2026 to 31 December 2026 (both dates inclusive). The offer is subject to terms and conditions. For details, please refer to the promotional leaflet:https://www.ctflife.com.hk/pdf/en/sky-leap-88-savings-insurance-plan-premium-offer-flyer.pdf# The comparison is based on the annual premium payment mode, assuming no policy withdrawal or surrender has been made, no other policy option has been exercised, and all premiums due have been paid in full on their respective due dates. The Guaranteed Breakeven Period / Projected Breakeven Period refers to the Policy Year in which the Guaranteed Cash Value / Total Policy Value first equals or exceeds the Total Premiums Paid at the end of that Policy Year. The Total Policy Value is calculated based on the current assumed investment returns and is not guaranteed.1The “Value Enhance Option” will be attached to the policy of the basic plan as a rider. If the Policy Owner prepays the premium and premium levy of the basic plan with premium payment in annual mode in full in advance, we will enhance the Guaranteed Cash Value and Total Policy Value of the Basic Plan, which will be shown in the Policy Illustration or the relevant endorsement schedule. Please refer to the policy provisions for further details of the “Value Enhance Option”.2“Special-in-market” is the result of comparing similar major life insurance savings products of major life insurance companies in Hong Kong as of 21 September 2026. In respect of the “Legacy Compassion Benefit”, "Special-in-market" refers to the feature whereby the benefit amount is calculated based on the Guaranteed Cash Value as at the effective date of policy continuation and is payable on the next policy anniversary following the third anniversary of the relevant policy continuation effective date.3Upon each exercise of the Policy Continuation Option, a Legacy Compassion Benefit will be payable. The benefit amount is equal to 8% of the respective Guaranteed Cash Value of the Original Policy and/or the Continued Policy (as applicable) immediately after the relevant Policy Continuation Option has been exercised. The benefit will be paid on the next policy anniversary following the third anniversary of the relevant Policy Continuation Effective Date. Please refer to the policy provisions for further details of the Legacy Compassion Benefit.4Wealth Accumulation Switching Options and its portfolio ratioSwitching option(s)“Stable Asset Account” allocationAllocation of the cash value of Reversionary Bonus (if any) and cash value of Terminal Bonus (if any)Advance0%100%Balanced40%60%Conservative80%20%“Stable Asset Account Allocation” = the value of “Stable Asset Account” ÷ (cash value of Reversionary Bonus (if any) + cash value of Terminal Bonus (if any) + value of Stable Asset Account) x 100%5While the policy is in force and the Insured is still alive, after the end of the 5th Policy Year and subject to the prevailing rules of the Company, you may exercise Policy Split Option to create a separate policy (the “Split Policy”), allocating a portion of Unit from the basic plan of the policy to the Split Policy without providing any evidence of insurability. Please refer to the Policy Provisions for more details of Policy Split Option. 6Please note that the Death Benefit Settlement Option (including “Life Event Option”) Policy Service belongs to other policy services. For the relevant terms and conditions, please refer to the respective service application forms and “Notification of Policy Service Confirmation”. CTF Life has the sole and absolute discretion to approve or reject applications for such service. All applications are subject to the relevant terms and conditions, which may be determined and amended by us from time to time without prior notice.7Source: Secretary’s Blog, The Financial Services and the Treasury Bureau, published in June 2026.8 The three signature product series include: (i) "Regent" / "MyWealth" Series (similar products as “Sky Leap 88”), (ii) "HealthCare 168" Series (similar products as "FamCare 198"), and (iii) "Fortune Saver" Series (similar products as “Ever Shine").9For policies under the above product series issued during the years from 2015 to 2024, the dividend fulfilment ratio of the Annual Dividend/ Reversionary Bonus / Terminal Dividend / Terminal Bonus for each policy issue year reached 100% or above. Please visit CTF Life’s website for the latest dividend fulfilment ratio information of the above or other products. Dividend and bonus history is for reference only and is not indicative of the future performance of CTF Life’s products.10As of 21 September 2026, the accumulation interest rate of the Company's participating USD policies has remained consistently at 4.25% p.a. since 2013. The interest rate is not guaranteed and may be adjusted from time to time.11 Account determined in accordance with the Wealth Accumulation Switching Option provision in which its long-term target asset allocation is 100% in fixed income type securities. The value of the Stable Asset Account will accumulate at such interest rate as may be declared by us from time to time. The current annual interest rate of the Stable Asset Account is 4.25%. (As of 21 September 2026, the accumulation interest rate of the Company's participating USD policies has remained consistently at 4.25% p.a. since 2013). However, the interest rate of the Stable Asset Account is not guaranteed and may even be 0% in any year.12Changing the Insured is subject to the prevailing administrative rules and designated requirements. The Unit, Guaranteed Cash Value, the face value of accumulated Reversionary Bonuses (if any) and the face value of Terminal Bonus (if any), any accumulated value of Stable Asset Account, Policy Date and Policy Years will remain the same on the Insured-Change Effective Date while the Plan End Date will be adjusted to the date of policy anniversary on the 128th birthday of the Changed New Insured or following the 128th birthday of the Changed New Insured (whichever is applicable). Please refer to the Policy Provisions for details of the Change of Insured Option.13Prior to the death of the Insured, the Policy Owner can assign one or two beneficiary(ies) for the Policy Continuation Option and specify the proportion of the Death Proceeds to be paid to each beneficiary for the Policy Continuation Option. Please refer to the Policy Provisions for details of the Policy Continuation Option. Please note that Policy Custody Value-added Service belongs to other policy services. For the relevant terms and conditions, please refer to the respective service application forms and the “Notification of Policy Service Confirmation.” CTF Life has the sole and absolute discretion to approve or reject applications for such service. All applications are subject to the relevant terms and conditions, which may be determined and amended by us from time to time without prior notice.14 Policy value withdrawal is subject to the Company’s minimum Unit requirement and the relevant terms and conditions. Policy value withdrawal belongs to other policy services. For details, please refer to the relevant service application form and the “Notification of Policy Service Confirmation.”15This assumes that all premiums due have been paid in full on their respective due dates and that no other policy options mentioned herein have been exercised. The above calculation is based on current assumed investment returns and is not guaranteed.16Subject to specified conditions. Please refer to the Policy Provisions for details of Death Benefit Settlement Option.17Subject to specified conditions. Please refer to the Policy Provisions for details of Full Surrender.18“Waiver of Premium Benefit” is not applicable to policies that attached “Value Enhance Option”. Please refer to the Policy Provisions for details of “Waiver of Premium Benefit” and “Payor Benefit”.Important Notice:- The information contained in this press release is intended as a general summary of information for reference only. For more details, please refer to relevant product brochures, promotion leaflets, and policy documents. For details regarding the CTF Life Sky Leap 88 Savings Insurance Plan, please refer to the policy contract for details of the full terms and conditions.- This press release does not contain the full provisions, key product risks, and all exclusions of the Sky Leap 88 Savings Insurance Plan, and the full terms can be found in the Policy documents. The Sky Leap 88 Savings Insurance Plan may serve as a standalone plan(s) without bundling with other type(s) of insurance product. Please refer to the main product brochure and policy terms and conditions, as well as the explanatory documents provided by your licensed insurance intermediary, to fully understand the details and complete terms and conditions regarding the mentioned definitions, fees, product features, exclusions, and compensation payment conditions related to the Sky Leap 88 Savings Insurance Plan.- Please refer to the product brochure for more information on the Sky Leap 88 Savings Insurance Plan: https://www.ctflife.com.hk/pdf/en/sky-leap-88-savings-insurance-plan-brochure.pdf- For further details, please contact CTF Life’s Customer Service Hotline on +852 2866 8898.- This press release is intended to be distributed in Hong Kong only and shall not be construed as an offer to sell or a solicitation to buy or provision of any of our products outside Hong Kong. Chow Tai Fook Life Insurance Company Limited hereby declares that it has no intention to offer to sell, to solicit to buy or to provide any of its products in any jurisdiction other than Hong Kong in which such offer to sell or solicitation to buy or provision of any product of Chow Tai Fook Life Insurance Company Limited is illegal under the laws of that jurisdiction. Copyright 2026 ACN Newswire via SeaPRwire.com. All rights reserved. www.acnnewswire.com
More
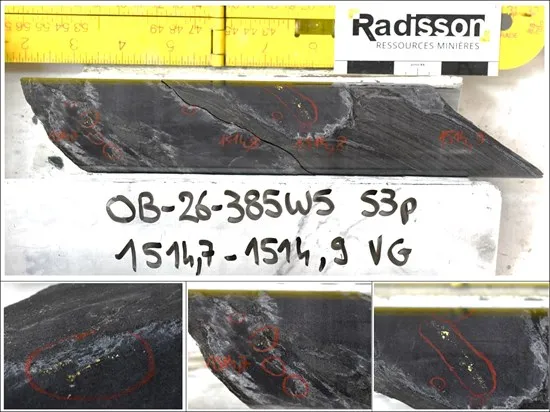
Wulong’s 3 Billion Yuan Gamble: Betting the Town on Global Trail Runners

(SeaPRwire) -By: Robert Kensington China’s mountain counties have long struggled to differentiate themselves in a crowded tourism market. Wulong in Chongqing tried a different playbook. Instead of building another glass-fronted resort, they built a 224-kilometer race course. The 21st edition of the China International Mountain Outdoor Sports Open kicked off on September 19, 2026. It was a big show. But the real story is not the athletes. It is the local economy hanging by a thread. They are trying to prove that a remote karst landscape can sustain a high-frequency, high-revenue sporting business model. The official numbers look impressive. The event has grown from 15 teams in 2003 to 41 top domestic and international teams this year. Ten of those sides are from overseas. The course weaves through sinkholes and caves. But look at the broader data. Between January and August 2026, sports-related tourism recorded over 5.53 million visitor arrivals. Tourists came from 56 countries. That is a massive influx for a single district. It suggests the event is no longer just a niche hobby for local runners. It is becoming a global destination brand. The commercial intent here is clear. They are not just selling medals. They are selling an entire lifestyle package. In the first half of the year, the outdoor sports industry generated over 3 billion yuan in revenue. Local homestays are full. Farm products are finding new markets. This is a deliberate shift from passive sightseeing to active recreation. They are trying to keep visitors longer. A weekend hike generates little income. A multi-day international competition generates hotel stays, local food purchases, and merchandise sales. The new individual sprint division lowers the barrier to entry. It allows elite competition to run alongside public fitness. This widens the net. The endgame is total economic dependency on this event. Wulong is moving from seasonal travel to year-round offerings. They are adding intangible cultural heritage handicrafts and local food to the mix. This creates a hybrid product. If the event fails, the local economy takes a hit. But if it succeeds, it becomes the anchor for the whole county. The risk is high. Global interest in outdoor sports is volatile. But the 3 billion yuan figure suggests they have already passed the initial proof-of-concept stage. The market is reshuffling. Mountain towns that focus on pure luxury are losing ground. Those that offer visceral physical experiences are winning. Wulong is betting big on the latter. Author bio: Robert Kensington, an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion.
More

When Enterprises Build Their Own Token Factories, the Cloud Pricing Model Has a Problem

(SeaPRwire) -By: Lucas Caldwell The phrase "Token Factory" sounds like corporate jargon, but KAYTUS is making a point worth taking seriously. Enterprises are tired of paying OpenAI and Anthropic by the token. They're building agentic AI systems that make hundreds of inference calls per minute. Every single one of those calls hits the cloud bill. KAYTUS is saying forget renting tokens. Manufacture them yourself. This isn't incremental optimization. It's a structural bet that hyperscaler pricing is broken at enterprise scale, and that on-premises GPU clusters can be converted into reliable, governed token production lines that enterprises actually control. MotusAI runs entirely on-premises. Model weights, inference processing, and context all stay within the enterprise security perimeter. It uses PD Disaggregation, dynamic KV caching, and dynamic batching to slash Time to First Token and end-to-end latency. Integrated with vLLM and SGLang runtimes, it dynamically scales compute based on real-time telemetry of TTFT, Tokens per Second, and GPU utilization. In production testing, autoscaling triggered within 21 seconds of peak traffic and expanded capacity to 16 instances in two minutes. GPU utilization climbed from 68.9% to 95.7% in benchmarks. The API gateway is OpenAI-compatible, supports million-token context, and claims 30-50% reduction in annual token operating costs through multi-tenant chargeback and redundant request filtering. The deployment track record isn't theoretical. An overseas fintech firm replaced its existing platform with MotusAI across eight GPU servers, enabling metered token services with centralized governance for internal risk analysis and security compliance. A Japanese cloud provider runs its core platform on MotusAI, serving more than 30 enterprise clients with shared GPU resources and end-to-end training and inference workflows. A Southeast Asian NeoCloud operator chose KAYTUS's integrated hardware and software solution over an international competitor, citing the platform's built-in multi-tenancy and billing capabilities. Three distinct markets, three different business models, same infrastructure stack. The bigger picture is this. Every major enterprise that deployed agentic AI at scale hit the same wall. Token costs spiral. Multi-step reasoning chains trigger unpredictable traffic spikes that blow through latency SLAs. Sending proprietary source code and customer records through public LLM APIs creates compliance nightmares that legal teams can't ignore. KAYTUS positions itself as the counter-move. If enterprises are shifting from simple LLM queries to autonomous multi-agent systems, tokens aren't an API call anymore. They're the computing currency powering core business workflows. The question isn't whether to control that currency. It's whether enterprises can build the factory fast enough. The GPU supply picture is equally tense. Enterprises can't just buy eight GPUs and expect efficient utilization. The gap between raw compute purchase and productive token output is where margins disappear. KAYTUS bundles liquid cooling hardware with the MotusAI software platform. That's a strategic tell. The company that owns the full stack from rack to inference runtime captures the most value. Southeast Asian NeoCloud operators already get this. They chose a bundled offering over a point solution from an international competitor. That's a market signal. Hardware-software integration isn't a nice-to-have. It's the consolidation engine that will define who survives the next AI infrastructure cycle. The enterprises that treat their GPU clusters as token production lines rather than rented compute, the ones that lock down model weights, enforce departmental chargebacks, filter redundant requests, and push utilization above 90 percent, will be the only ones with positive unit economics when agentic AI becomes the default operating model for every regulated industry from finance to healthcare to government, and KAYTUS is betting the entire MotusAI roadmap on that exact timeline arriving before hyperscalers adjust their pricing to match reality. Author bio: Lucas Caldwell, a tech opinion leader with millions of followers on X/Twitter, covers AI infrastructure, enterprise compute economics, and the structural shifts in how organizations deploy and govern artificial intelligence systems at scale.
More

YeahPay’s Stripe Play: Why Riding Someone Else’s Rails Won’t Save You When Agents Start Paying

(SeaPRwire) -By: Robert Kensington YeahPay is telling the world it has cracked the code on unified global acquiring. The reality is thinner than the press release suggests. The company is riding on Stripe's infrastructure. It is not building rails. It is painting over someone else's tracks and selling the ticket. Here is what YeahPay actually announced. Businesses incorporated in Australia, Canada, Hong Kong, Japan, Singapore, the United Kingdom and the United States can now be onboarded directly by YeahPay for online acquiring in their own market. The infrastructure behind it is built on Stripe. In-store acceptance already exists in Hong Kong and Singapore. That two-market footprint is being stitched together with online payment capabilities for the first time. YeahPay has spent more than a decade building payment acceptance for small and medium merchants in mainland China. The majority of that happened across a counter. Now the company is exporting that experience onto the same integration used for online payments. Yeahka serves approximately 9.2 million merchants and nearly 1 billion consumers. That scale is real. It is also mostly domestic. The official facts read like a geographic checklist. Seven markets. One integration. Multi-currency processing. Local payment methods. Payment links, ecommerce plugins, platform onboarding. All packaged neatly. The subtext is more interesting. Stripe already does all of this directly. A merchant in Toronto can onboard through Stripe without YeahPay standing in the middle. YeahPay's value proposition, as stated in the release, is that clients should not have to predict how payments will change. David Tay, Global Vice President, called it a single integration that lets businesses accept any form of payment. The claim sounds bold. It lands differently when you trace where the money actually moves. YeahPay is aggregating Stripe's API and wrapping it in market-specific onboarding and local method support. That is a real function. It is not a moat. What is different here is the pivot toward agentic payments. YeahPay is exploring applications across online retail, dining, and gaming. Proof-of-concept collaborations with international financial institutions have already begun. This is the part that matters. Merchants are not the only buyers anymore. Bots will initiate transactions. Agents will negotiate prices and settle payments without human input. Stripe is building for this shift too. So are Checkout.com and Adyen. YeahPay's window to differentiate around agent-ready infrastructure is narrow. The company needs to move from wrapper to layer that adds real value before the platform giants finish their own agent payment stacks. YeahPay's geographic spread looks impressive on paper. The seven markets listed cover the major English-speaking and Asian commercial hubs. But coverage is easy to announce. Integration depth is harder to prove. In-store acceptance in Hong Kong and Singapore is a step toward bridging offline and online flows. YeahPay has not disclosed whether that bridge holds up when merchants operate across borders in real time. Counter-based merchant experience in mainland China does not automatically translate into seamless cross-border online acquiring. Checkout flow, fraud scoring, chargeback handling, and settlement timing all behave differently across jurisdictions. YeahPay will need to prove it beyond the headline. The commercial loop is still forming. YeahPay targets small and medium merchants who do not want to manage multiple payment providers. That is a defensible niche. Stripe's direct pricing has pushed many smaller merchants toward aggregators. YeahPay can win on concierge onboarding and regional payment method support. It cannot win on price if Stripe decides to target the same segment directly. The partnership that enables this expansion is also the ceiling. Stripe can change terms. Stripe can build the agent payment features first. YeahPay's independence depends on how much proprietary logic it stacks on top of the API. Market share will shift. YeahPay is positioning itself as infrastructure for the next phase of commerce. The announcement gives it reach across seven markets. Reach is not the bottleneck. Depth is. Agents are coming. The question is whether YeahPay will be the rails they run on, or just another face on Stripe's storefront. Author bio: Robert Kensington is an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion, specializing in cross-border payment infrastructure and market entry strategy.
More

A Pump Maker From Taiwan Just Walked Into the AI Data Center — and That Should Make Cooling Giants Nervous

(SeaPRwire) -By: Ethan Gallagher Everyone fixates on GPUs when the rack density conversation starts, and I have sat in enough colocation planning meetings to know that the boring component is always the one that fails at 2 a.m. A pump. Not a chip, not a transformer. So when Walrus Pump, a Taiwanese fluid-control specialist, announces it is showing up at the 2026 TAIWAN EXPO USA from September 24 to 26 with cooling solutions as its main theme, I do not read it as a trade show booth. I read it as a component vendor making a direct play for the most stressed layer of AI infrastructure. Pumps are the core fluid control equipment in any liquid cooling system, and their performance, reliability, and size determine how well the entire thermal loop behaves. That is not marketing copy. That is physics. The release frames this as a debut, and it is, but the ambition is plainly larger. Now the official facts. Walrus is bringing three pump series, each mapped to a specific cooling architecture. The TPMS horizontal centrifugal pump targets in-row coolant distribution units. It carries an ultra-slim IE5 permanent magnet motor built on exclusive Japanese technology, cutting overall size by two-thirds, plus patented leak detection with real-time sensors. The CMP DC sealless pump goes after in-rack CDUs, with a structure optimizable for 4U or 6U configurations, an adjustable outlet angle, and a claimed 20 percent performance edge over comparable products in a standard 4U setup. The TPHK-S submersible centrifugal pump addresses immersion cooling, using a patented return-flow design to prevent coolant leaks and environmental contamination, with selectable pump body and shaft seal materials for a wide range of liquids. Notably, the company says these pumps have already been adopted in the data center supply chain serving global AI-related and semiconductor industries. That is the quietest, most important sentence in the release. The subtext sits in the second half. Walrus is not hiding that it has worked with major global companies and leading Taiwanese makers of cooling modules and systems, and it is now pushing from single-pump manufacturing into modular customization, product configuration, and system integration. In plain terms, the company wants to stop being a line item on a bill of materials and start being a design-in partner. It is offering pump specs and integrated supporting components matched to each system's structure, because every liquid cooling deployment differs in space, flow rate, efficiency, fluid compatibility, and safety monitoring. It is also positioning for microchannel lid cooling and developing brushless DC motor technology. If you have watched the CDU market consolidate around a handful of thermal integrators, you know why this matters. Integrators need pump suppliers who speak systems, not just shafts and seals. Walrus is betting its Taiwan manufacturing and R&D base can win that design conversation before the Western incumbents lock up the sockets. Here is the blunt read. AI server power keeps climbing, air cooling is surrendering rack by rack, and the liquid cooling bill of materials is still being written. Whoever owns the pump spec inside the CDU owns a quiet, recurring, hard-to-rip-out position in every future data hall. Walrus has the product breadth across in-row, in-rack, and immersion to be taken seriously. What remains unproven is whether a pump specialist can hold margin once the big thermal houses start squeezing their suppliers. My call is simple: the winners in this layer will not be the loudest cooling brands, they will be the vendors whose pumps were qualified first, because nobody swaps a validated fluid component mid-deployment, and that stickiness is the whole game. Author bio: Ethan Gallagher, a Silicon Valley hardware architect and infrastructure strategist who has spent over a decade designing data center power and thermal systems for hyperscale and colocation operators.
More
How Chery’s LEPAS Brand Is Quietly Flanking Europe’s Premium Automakers Business

How Chery’s LEPAS Brand Is Quietly Flanking Europe’s Premium Automakers

(SeaPRwire) - By: Robert Kensington Let's stop pretending Chinese electric vehicles are still fighting for survival in Europe. The narrative that they barely scrape by on price advantage is dead. What we're watching now is a much more calculated assault. A Chinese brand is not asking for permission. It is walking into London, Rome, and Madrid with a product that meets the highest safety benchmarks and expects to be taken seriously at the dinner tables of people who once laughed at the idea. The facts on the ground tell the story. Chery Group moved more than 208,000 vehicles across 24 European countries between January and July this year. That is a 201 percent increase compared to the same period last year. New energy vehicles alone accounted for 102,000 of those units. A 332.47 percent jump. In August, Chery topped the UK's monthly new-car brand sales chart. Not second place. First place. Ahead of Volkswagen. Ahead of Ford. Ahead of BMW. The first Chinese automaker to ever hold that position. NEVs now make up roughly half of Chery's total European sales. These are not tentative entries. These are decisive numbers. But the raw sales data only shows half the picture. The other half is written in a language that German and Japanese competitors understand intimately. LEPAS made its European debut at Milan Design Week in April. The brand has since secured a Best Interior Design Award at the 2026 Torino Automotive Design Award for the L6 model. The jury praised spaciousness, premium materials, flexible storage, and a natural integration of advanced technology. This is not a company outsourcing design to a generic studio. This is a company hiring a professional European team to tune chassis characteristics for mountain passes, coastal roads, and narrow urban streets that define real driving conditions across the continent. The LEPAS L8 PHEV is built against the 2026 Euro NCAP safety protocols from day one. They did not adapt an existing model to pass European regulations. They started from the regulations and built outward. That is a fundamental difference in engineering philosophy. What makes this expansion genuinely threatening to the incumbents is the infrastructure layer underneath it. By the end of August, Chery Group's cumulative exports had surpassed 7 million vehicles. Twenty-three consecutive years as China's number one passenger vehicle exporter. The LEPAS network already spans more than 500 sales and service outlets globally. This is not a startup burning venture capital on showrooms. This is a manufacturer with deep supply chain experience deploying localized operations across markets with some of the strictest regulatory environments on earth. The LEPAS Global Journey of Elegant Driving event will put the L8 PHEV through real-world testing across multiple countries. The inaugural LEPAS Global Elegant Lifestyle Week in October is not a marketing gimmick. It is a deliberate move to own the cultural conversation around premium mobility in Europe. The European auto industry spent decades building brand loyalty on a foundation of mechanical reliability and emotional heritage. Chinese manufacturers now bring a different equation. Comparable or superior product quality, aggressive pricing that undercuts traditional margins, a design sensibility that respects local aesthetics without mimicking them, and an operational backbone that can scale distribution faster than legacy companies can respond. The LEPAS L8 PHEV entering the UK, Italy, and Spain represents the next phase of this competition. It is no longer about volume displacement. It is about brand displacement. The incumbents have a response window. It is closing. Author bio: Robert Kensington is an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion.
More
Converse’s White Mask: A Brand on the Brink of Irrelevance Hot News

Converse’s White Mask: A Brand on the Brink of Irrelevance

(SeaPRwire) - By: Christian Pierce A white hood. A pair of dangling shoes. A spotlight. Converse just handed its critics the most perfect metaphor for corporate negligence in decades. This wasn't a typo. It wasn't a translation error. It was a failure of basic human empathy wrapped in a $200 billion market cap shell. When you lose more than $200 billion in value since your 2021 peak, you are no longer just a sportswear company. You are a liability. And a liability that gets it this wrong on race and history isn't just offending people. It is exposing the hollow core of its current leadership strategy. The facts are stark and uncomfortable. The ad featured Karina of Aespa in a long white skirt under a spotlight. Critics saw a KKK hood. They saw the dangling sneakers as the feet of a lynching victim. Representative Troy Carter called it "racist, reckless and deeply offensive." Converse apologized on Saturday, admitting they "got this wrong." They removed the ad from their channels. But as civil rights attorney Lee Merritt pointed out, removing it doesn't undo how it passed legal, marketing, and leadership review. The damage is done. The public trust isn't just shaken. It is shattering. This incident sits atop a pile of recent missteps. In April 2025, Nike apologized for a London Marathon billboard that read "NEVER AGAIN. UNTIL NEXT YEAR." Critics linked it to Holocaust remembrance. Then came the Boston Marathon ad: "Runners welcome. Walkers tolerated." Each stumble is a chip in the armor. Now, Converse is reviewing internal processes under CEO Aaron Cain. He pledged to "make needed changes." But words are cheap. The stock has already fallen off the S&P 100 index after nearly 18 years. It remains in the broader S&P 500, but the signal is clear. Investors are voting with their feet. The decline is prolonged. Competition is fierce. Innovation is lacking. China demand is weak. Every PR crisis now costs more than the previous one. The cycle is brutal. You fail, you apologize, you move on. But the trust erosion is cumulative. It never fully returns. In the end, this isn't about one bad ad. It is about a brand that has lost its moral compass and its commercial footing simultaneously. The KKK imagery is the final straw for a consumer base that is already weary. Converse needs to stop looking at trends and start looking at the consequences of their creative pipelines. The market doesn't forgive repeated failures. It punishes them. And it does so quickly. Author bio: Christian Pierce is a chief financial columnist and markets commentator, specializing in the intersection of corporate governance and brand equity within the global consumer sector.
More