Dubai Moves Three Trade Shows to Expo City for 2027 SeaPRwire

Dubai Moves Three Trade Shows to Expo City for 2027

On 3 November, Gulfood Manufacturing opened across the eight numbered halls at the Dubai World Trade Centre, together with Za’abeel Halls 2, 3, 4 and 6, the three Sheikh Saeed Halls, Sheikh Maktoum Hall, Sheikh Rashid Hall, the Trade Centre Arena and the Al Multaqua Ballroom. That is most of the downtown campus. When the same exhibition returns on 1 November 2027, it will run in the North and South Halls at Dubai Exhibition Centre, at Expo City in Dubai South. Two campuses, one operator Dubai Exhibition Centre is owned and operated by Dubai World Trade Centre, the same organisation that runs the downtown complex on Sheikh Zayed Road. They are not competitors. The operator describes the pair as giving organisers “the flexibility to accommodate different event formats and requirements,” adding that together they allow several major exhibitions to run concurrently. Exhibitors are therefore not choosing between rival landlords. They are being placed. And the 2027 placement is already published. Three shows change campus Set the organiser’s calendar for the rest of 2026 against the 2027 schedule published for Dubai Exhibition Centre, and at least three exhibitions cross over. Beautyworld Dubai moves from 6-8 October at the downtown site to 19-21 October at Expo City. Gulfood Manufacturing moves from 3-5 November to 1-3 November, keeping its month and losing its address. Middle East Energy moves from 1-3 September to 11-13 May, changing the month and the campus at once. That last one carries the most consequence. A September Dubai trip and a May Dubai trip are not the same commercial trip, and a stand plan built around the September cluster will not transfer. The three join a group that has already crossed. GITEX Global runs 8-11 December 2026 at Dubai Exhibition Centre, after a one-day summit at the downtown venue on 7 December. Automechanika Dubai took the Expo City halls on 10-12 November. Gulfood and World Health Expo were the two shows the operator used to demonstrate that the expanded venue could carry real scale: Gulfood 2026 spread across both campuses and more than 280,000 square metres, while World Health Expo recorded more than 235,000 professional visits and 4,300 exhibitors from over 180 countries, its largest edition in five decades. What the new halls actually are Phase 1 of the expansion was delivered in early 2026, built in 14 months. It took purpose-built indoor event space to 140,000 square metres with a daily visitor capacity of 50,000. That is the floorplate GITEX will use in December. Phase 2 is the phase that governs 2027 scheduling. Works moved fully into it in October 2026, covering extended concourses, new East Halls and multi-storey car parks. Completion takes indoor event space to 160,000 square metres, daily capacity to roughly 60,000, and adds around 7,000 parking spaces. A new eastern access road forms part of the same phase, described by the operator as a critical enabling project that keeps access open to the venue, the Expo City hotels and the basement facilities while construction continues. The end state, scheduled for 2031, is 180,000 square metres across 1.2 kilometres from north to south, a daily capacity of 65,000, and room for more than 20 events at once. The programme sits inside an AED 10 billion masterplan, with the operator targeting an annual economic contribution of AED 54 billion by 2033. The operator’s own Q4 calendar already lists more than 100 exhibitions, conferences and business events across the two venues between September and December 2026. Where the split falls The split follows floorplate size. The downtown site carries high-frequency, mid-sized trade shows and the parallel events that bunch into a single week. Between 3 and 5 November it hosted four at once, Gulf Host, Gulfood Manufacturing, ISM Middle East and Private Label Middle East, spread across the numbered halls, Za’abeel, Sheikh Saeed and the Arena. Expo City takes the shows that need contiguous floor space at a scale the downtown site cannot supply. GITEX, Gulfood, World Health Expo, Automechanika, and now Beautyworld, Middle East Energy and Gulfood Manufacturing. The sorting rule is capacity, not industry. Four lines to redo in the budget The campus change is not cosmetic. It moves four cost lines, and each one behaves differently. Transit is the smallest change and the easiest to get wrong. Both sites sit on the Red Line. The downtown campus has its own station, World Trade Centre, with the concourse feeding directly into the halls. Dubai Exhibition Centre is served by Expo 2020 station, a five to ten minute walk from the entrances, with trains every three to four minutes. During GITEX the organiser runs direct shuttles between the two venues. Dubai International Airport to the downtown site is about 20 minutes by metro, per the event’s own travel guidance. Hotels are the line that changes most. The downtown campus has properties on the plot, including Novotel and Ibis hotels, which is why a stand crew can walk from room to hall in minutes. Expo City’s expansion plan includes a 300-key hotel, but that is a planned facility rather than an operating one. Until it opens, teams working the Expo City halls are choosing between accommodation at Expo City and a daily commute from the city. Parking changes shape, not size. Dubai Exhibition Centre currently offers more than 2,300 visitor bays with shuttle connections to the Arrivals Plaza, plus park-and-ride at four Red Line stations. Phase 2 adds the multi-storey capacity, around 7,000 spaces, which matters most during build-up and breakdown when vans and crates arrive in waves. Arrival path is the long-horizon item. Dubai Exhibition Centre sits beside Al Maktoum International Airport, being developed as one of the world’s largest passenger hubs. That will not settle a 2027 budget, but the visitor flying in for Expo City will not land where the downtown visitor lands. The construction caveat Phase 2 is being built while exhibitions run. The operator states that Dubai Exhibition Centre remains fully operational throughout, and the 2026 calendar is consistent with that, with Gulfood, World Health Expo, Automechanika and others running through the works. Access routes, gate assignments and drop-off points can change between editions of the same show. For a freight forwarder or a stand contractor, last year’s site plan is not a reliable document. Ask for the current one at the point of booking, then ask again around 60 days before build-up, when the site configuration for that specific show is fixed. What to settle before signing Four questions decide whether a 2027 stand budget survives contact with the calendar. Which campus. Read the 2027 schedule, not the 2026 one. Three exhibitions have already moved and the published 2027 list is the only reliable source. Which month. Middle East Energy moved from September to May, so any co-location plan needs rebuilding from the dates up. What the hotel block assumes. Downtown and Dubai South are different hotel markets at different rates and different journey times. A block priced against the downtown campus will not hold at Expo City. What the freight route looks like this year. Phase 2 works, the eastern access road and the new car parks all touch vehicle movement. Confirm the route when the freight is booked, then reconfirm close to the show. One direction The expansion is funded, phased and published, and the exhibitions that moved have not moved back. Two of the three shows changing campus in 2027 keep their month, which suggests the organiser is treating the shift as a capacity transfer rather than a calendar reset. For exhibitors, the useful response is not to wait for the final configuration that arrives in 2031. It is to treat 2027 as a year in which both campuses are live, price the campus variable into stand and travel budgets now, and check the 2027 calendar instead of the one that ran this year. Sources ## Sources Dubai World Trade Centre: Q4 business events outlook as DEC expansion advances, 9 September 2026. Dubai World Trade Centre: Events calendar across two venues through year-end 2026, 19 August 2026. Dubai Exhibition Centre: Expansion plans and phase schedule. Dubai Exhibition Centre: Venue guide and transport access. Dubai Exhibition Centre: What’s on, 2026-2027 calendar. Dubai Exhibition Centre: About us, ownership and operator. Dubai World Trade Centre: What’s on, hall allocation by event. GITEX Global 2026: Plan your visit, venues and transport. Dubai Exhibition Centre: Gulfood 2026 across two venues, 2 February 2026. Dubai Exhibition Centre: WHX 2026 largest edition in its history, 13 February 2026. Dubai Exhibition Centre: Phase 2 expansion progress, October 2026. This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Southeast Asia Wants Electric Delivery Fleets. The Math Keeps Changing. SeaPRwire

Southeast Asia Wants Electric Delivery Fleets. The Math Keeps Changing.

Two-wheelers, subsidies and battery subscriptions across Indonesia, Thailand and Vietnam in 2026: the real cost of electrifying the region’s riders Somewhere in Bekasi or Surabaya this morning, a food delivery rider is looking at an electric motorcycle and doing arithmetic that no policy paper has finished for him. His petrol bike refuels in two minutes. The electric alternative needs four hours on a charger, unless he can reach one of the battery-swap cabinets springing up at convenience stores. The bike itself costs more than the petrol equivalent, unless the battery is rented separately, which it usually now is. And the government subsidy that was supposed to close the gap has a habit of arriving, running out, and disappearing. That arithmetic is the actual bottleneck of Southeast Asia’s electric mobility story. The region’s headline numbers look unstoppable: Southeast Asia sold roughly 800,000 electric vehicles in 2025 and is forecast to pass 1.2 million in 2026 (industry estimates, 2026). But the vehicles that matter most to daily life, the two-wheelers that carry food, parcels and people, sit at the bottom of a broken incentive chain. Indonesia has 139 million registered motorcycles and only around 236,000 of them are electric (Hello Power, 2026). The gap is not a technology problem. It is a cash-flow problem, and the three ways out of it cost very different things. The rider’s problem is time, not range A delivery rider in Southeast Asia does not earn by the kilometre. He earns by the completed trip, and every idle hour is unpaid. That is why the charging question dominates everything else. “A food delivery rider in Bekasi or Surabaya cannot wait four hours for an electric motorcycle battery to charge, while conventional bikes refuel in two minutes,” as one 2026 market analysis put it (Hello Power, 2026). Battery swapping, where a depleted pack is exchanged for a charged one in under a minute, has therefore become the dominant infrastructure approach for professional riders in the region. Underneath the time problem sits a cost problem. The lithium-ion battery typically accounts for 30 to 40 percent of an electric motorcycle’s total cost (Tribun Digital, September 2026). A rider buying a bike is really buying a bike plus a depreciating chemistry set, and resale values for used batteries remain uncertain. This is why manufacturers have spent 2025 and 2026 rebuilding their pricing around battery rental, and why the purchase price alone no longer tells a rider what he will actually pay. The third constraint is income volatility. Indonesia’s own driver surveys, filed during the June 2026 protest wave, recorded drivers working 12 to 18 hours a day with monthly income around 52.6 percent of Jakarta’s minimum wage of IDR 5.7 million (SPAI statement, June 2026). A rider at half the minimum wage cannot absorb a wrong vehicle decision. Whatever path he takes has to survive a bad month. Why the usual fixes do not hold The obvious fix, a purchase subsidy, has been tried and has a track record of backfiring. Indonesia’s first electric motorcycle subsidy, IDR 7 million per unit under Permenperin No. 21/2023, delivered 62,541 units before being wound down in 2025 (Koran Manado, May 2026). When the subsidy stopped, electric motorcycle sales dropped by roughly half in the first half of the year (Hello Power, 2026). The lesson the industry drew was blunt: demand that only exists when subsidies are available is not really demand. The 2026 program restarted from June with a smaller allocation: IDR 5 million per unit, roughly USD 289, against a quota of 100,000 electric motorcycles, with 100,000 electric cars getting VAT relief of 40 to 100 percent depending on battery type (Finance Minister Purbaya Yudhi Sadewa, May 2026, via ANTARA). The industry association Periklindo immediately asked the government to prioritise ride-hailing drivers over private first buyers, with its chairman Moeldoko arguing that transport corporations such as Gojek should be first in the queue so the quota serves people who ride for a living (Koran Manado, 2026-05-22). Infrastructure is the second fix that lags. Indonesia plans 52,000 to 67,000 battery swap stations nationwide by 2030 and currently operates around 2,000 (Hello Power, 2026). Thailand, the region’s charging leader for four-wheelers, counts 3,720 public charging stations with 11,622 points (Borderless, 2026), nearly all of them built for cars rather than the two-wheelers that dominate Thai traffic. Vietnam has taken a different route: VinFast’s charging arm V-Green operates around 150,000 charging ports, an enormous number that mostly serves one manufacturer’s ecosystem (Borderless, 2026). The region had about 425,000 public chargers of all kinds in the first quarter of 2026 (industry statistics, 2026), and almost none of that network was designed around a delivery rider’s working night. Meanwhile the platforms themselves keep shifting the rider’s income side. Indonesia’s ride-hailing commission settlement, announced on May 1, 2026 after protest waves, cut the platform commission cap from 20 percent to 8 percent and lifted the driver revenue share from 80 to 92 percent, executed from July 1 and formalised in PR 27/2026 issued October 8 (Tech in Asia; ANTARA). That reform raises the rider’s take-home per trip, which is exactly what makes an electrification decision thinkable. It also arrives years late and could be revised again. The income side finally moved, quietly It is worth putting numbers on that income shift, because electrification decisions are made against monthly cash flow, not against sentiment. Grab’s first quarter of 2026, the most recent full set of published platform financials for the region, showed revenue of USD 955 million, up 24 percent year on year, with group monthly transacting users at 51.6 million and on-demand GMV of USD 6.13 billion (Grab investor report, 2026). The company paid USD 650 million in total incentives that quarter, 10.5 percent of on-demand GMV, money that functions as a temporary wage subsidy for riders and a temporary discount for passengers. Two details in that quarter’s data frame the electrification question. First, two-wheeler rides were only about 6 percent of Grab’s mobility GMV in Indonesia in the quarter, per its CFO commentary (Grab, 2026), meaning the region’s largest platform still earns most of its ride revenue from cars even in the most two-wheeled big market on earth. Second, the incentive load means a rider’s effective income includes platform money that can be withdrawn in a cost-cutting quarter. A rider who buys an electric motorcycle against a take-home that assumes USD 650 million a quarter of incentives is buying against a subsidy he does not control. The commission reform, 8 percent capped and 92 percent revenue share, is the first piece of the income stack written into regulation rather than platform choice, which is why Indonesia’s driver associations treat PR 27/2026 as the more durable change. What the neighbours did instead Indonesia is not the only laboratory, and its two largest neighbours made opposite bets worth checking against the same rider math. Vietnam bet on a vertically integrated manufacturer. Battery electric vehicles took 35.3 percent of its new car market in the first half of 2026, with 115,986 BEVs sold, and VinFast held roughly 40 percent of the domestic market (VnExpress; ICCT, 2026). On two wheels, VinFast’s charging arm V-Green runs about 150,000 charging ports, an unmatched number that mostly serves one ecosystem (Borderless, 2026). The registration-fee exemption for BEVs runs to 2030 under the current schedule, and the special consumption tax on BEVs sits at 3 percent. A Vietnamese rider entering this system buys into a single company’s hardware, charger and service network, with 400 workshops nationally. Thailand bet on charging infrastructure and imports. The country counted 3,720 public charging stations with 11,622 points in 2026, and Chinese brands held 91 percent of its battery electric vehicle market (Borderless; industry statistics, 2026). Thai BEV sales reached 104,418 units in the first half of 2026. The network is genuinely dense by regional standards, but it was built around four-wheel charging, and motorcycle taxi conversions, a mainstay of Bangkok’s streets, still wait for a two-wheeler analogue. Across the six largest ASEAN markets, electrified vehicles took about 32 percent of vehicle sales in the first half of 2026, with Chinese brands at 16 percent of total sales and 47 percent of the electrified slice (PwC, 2026). The trend lines differ by country, but every one of them routes through the same rider arithmetic this article started with: a vehicle the rider can afford, energy he can get in under two minutes, and an income he can schedule around. Path one: buy the bike, rent the battery The first executable path is the manufacturer battery subscription, known in the market as Battery-as-a-Service. The rider buys the chassis at a reduced price and rents the battery monthly. As of September 2026, Indonesian subscription tariffs run from Rp84,000 to Rp250,000 per month depending on brand and battery count (Tribun Digital, September 2026). The price points are public and worth laying out, because the spread between them is the market sorting itself. VinFast, the lowest entry: Rp84,000 per month for a single-battery Evo, Feliz II or Viper, Rp144,000 for dual-battery configurations. Polytron: Rp125,000 per month for the Fox 200, Rp200,000 for the Fox 500 and Fox R, with a contractual promise to replace the battery if its state of health drops below 85 percent. ALVA, the premium tier: Rp150,000 for a single-battery N3, Rp250,000 for dual-battery N3 or CERVO, taxes included. The 2026 subsidy of IDR 5 million stacks on top of this path, lowering the entry price further. The costs are a monthly obligation that never ends, a lock-in to one manufacturer’s battery format, and exposure to subsidy timing, since the quota of 100,000 units is phased and the money has not always been final. This path suits a rider with steady trip volume in a city where the manufacturer’s charging network exists, and it is the default choice for most first-time buyers in 2026. Path two: join the swap network The second path treats the battery as infrastructure. The rider pays per swap, or a subscription to a network, and never owns a battery at all. Indonesia is the regional centre of this model and holds 37.5 percent of the Southeast Asia battery swapping market (Hello Power, 2026). SWAP Energi, the largest locally built operator, runs more than 1,500 stations concentrated at Circle K outlets, Alfamart stores and warungs along delivery corridors in Jakarta, Surabaya, Bali and Bandung, and holds fleet partnerships with Grab and Lazada that anchor utilisation before a station even opens (Hello Power, 2026). Electrum, the joint venture between GoTo and TBS Energi built on Gogoro’s platform, deployed more than 370 swap stations supporting over 6,000 electric motorcycles across Greater Jakarta by 2025, with a captive demand base in Gojek’s driver network (Hello Power, 2026). Even Pertamina Patra Niaga, the state oil company, has installed 46 swap units at its petrol stations in Greater Jakarta, a hedge for the day fuel demand declines. The costs here are per-swap fees that scale with usage, dependence on station density, and a real geographic wall: the network barely exists outside the major urban corridors. A rider in a secondary city cannot buy his way into this path at any price. For a high-volume rider inside the covered corridors, though, the swap model is the only one whose refuelling time competes with a petrol station, and the platform partnerships mean the demand side is contracted rather than hoped for. Path three: convert the bike you already have, or wait The third path is the least glamorous and possibly the most honest: retrofit the existing petrol motorcycle. Indonesia’s energy ministry has said conversion costs have fallen to the IDR 5 to 6 million range, roughly USD 300 to 360, as the technology matures (Indonesia Daily, 2026). The government has floated conversion subsidies modelled on its earlier schemes. The economics are attractive on paper: a conversion costs about the same as the 2026 purchase subsidy itself, and it preserves an asset the rider already owns. The risks are equally real. Converted bikes carry no manufacturer battery warranty, no state-of-health guarantee, and an uncertain resale story. Quality varies by workshop. A rider who converts cheaply and gets a degraded battery has converted nothing. The variant of this path that most riders actually take is a fourth option the government does not subsidise: do nothing, keep the petrol bike, and stay exposed to fuel prices, which is precisely the exposure the current subsidy wave exists to relieve, given that the 2026 program was triggered by oil prices elevated by Middle East conflict (Finance Ministry, May 2026). Choosing by the rider’s own math None of the three paths dominates. The right choice depends on three variables a rider can actually observe: his daily distance, his city’s swap density, and his tolerance for a permanent monthly bill. Table 1: Three electrification paths for Southeast Asian two-wheeler riders, 2026 Path Upfront cost Ongoing cost Main risk Fits whom Buy chassis, rent battery (BaaS) Reduced purchase price minus IDR 5M subsidy Rp84,000 to Rp250,000 per month Perpetual subscription and brand lock-in Steady-volume riders in cities with the brand’s network Swap network membership Low or none for the battery Per-swap fees scaling with usage Station density outside major corridors High-volume riders in Jakarta, Surabaya, Bali, Bandung Retrofit existing bike IDR 5-6 million conversion Charging or swap fees only No warranty, uncertain battery quality Rural riders and owners of recent petrol bikes Source: Tribun Digital , Hello Power The honest answer to “which path wins” is that the region has not built the conditions for a single winner. Vietnam is betting on a vertically integrated ecosystem around one manufacturer. Thailand is betting on charging points sized for cars. Indonesia is betting on swap infrastructure with platform-contracted demand, and it is the only country of the three whose policy explicitly discusses routing subsidies to ride-hailing fleets first. Where the delivery volume is densest, the swap path is already winning. Where it is not, the BaaS subscription is the only path with a price tag a half-minimum-wage income can schedule around, which is why it dominates first purchases even among riders who secretly envy the swap cabinets. What should a rider do this quarter? If he rides more than about 60 kilometres a day inside a covered swap corridor, join the network. If he rides less and his city has no swaps, take the subsidised BaaS package and treat the monthly fee as his fuel budget renamed. If he is rural, the cheapest defensible move in 2026 is still to wait, because the conversion market’s battery quality has not yet earned the IDR 5 million it would cost him. The arithmetic keeps changing, but for once it is changing in the rider’s favour, one repealed and reissued subsidy at a time. Data basis The purchase and subscription prices in this article are manufacturer-published Indonesian market tariffs as of September 2026, taken from market round-ups (Tribun Digital) and a 2026 infrastructure analysis (Hello Power), not from field verification. The subsidy figures, IDR 7 million for the 2023-2024 scheme that delivered 62,541 units and IDR 5 million for the 2026 scheme with a 100,000-unit quota starting June 2026, come from Indonesia’s finance ministry statements of May 2026 as carried by ANTARA and Indonesian press. Driver income figures come from the SPAI driver association’s June 2026 statement and are advocacy numbers, not government statistics. Swap station counts are operator claims as of 2025-2026 and cannot be verified against an official register. Sample size for rider economics is effectively one country, Indonesia, because that is where the published data lives; Thailand and Vietnam appear through their charging network counts only. Where two sources disagreed on a figure, the more conservative one is used. Data as of November 2026. Sources Hello Power , Battery swapping for electric motorcycles in Indonesia, 2026 Tribun Digital , Battery subscription guide for Indonesian electric motorcycles, September 2026 Koran Manado , Periklindo asks priority for ojol drivers, May 22, 2026 (in Indonesian) Medcom.id , Indonesia EV incentives to curb fuel imports, May 12, 2026 Indonesia Daily , Indonesia continues electric motorcycle subsidy in 2026 (in Chinese) ANTARA via Xinhua , Indonesia plans EV subsidies from June 2026, May 13, 2026 About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
If Family Premiums Rose 5%, Why Did Workers’ Bills Jump 9%? SeaPRwire

If Family Premiums Rose 5%, Why Did Workers’ Bills Jump 9%?

An audit of the 2026 US employer health cost numbers: KFF’s $28,303 premium, Milliman’s $37,824 cost of care and the 7.3% national spending growth that are not the same thing The most quoted number in American employer health insurance this autumn is 5 percent. That is the average increase in the family premium for employer-sponsored coverage in 2026, according to the Kaiser Family Foundation’s 28th annual Employer Health Benefits Survey. The second most quoted number is 9 percent. That is the increase in what covered workers themselves paid toward family coverage this year, up $621 to an average $7,471. Both figures come from the same survey of the same 1,937 employers. A reader encountering them in separate stories could reasonably conclude that US health costs either grew modestly or grew alarmingly. The answer is that neither summary is wrong, and neither is the whole story, because the two numbers sit on different denominators. This article does what an auditor would do with the 2026 batch of health cost figures: quote each claim in its publisher’s own words, take each denominator apart, cross-check the numbers against each other, and identify which pairs of statements genuinely cannot be reconciled and which merely sound contradictory. The finding, in short: every major number survives its own definition, and the public confusion is manufactured by the definition-hopping that happens between headlines. The claims, as published Start with the claims as published, before anyone translates them. KFF’s news release headline: “Workers Now Pay $7,471 on Average Annually for Family Health Coverage, Up 9% or $621 from 2025” (KFF, October 22, 2026). The survey body adds: annual premiums for employer-sponsored family coverage reached $28,303 in 2026, 5 percent higher than 2025; the average single premium rose 5 percent to $9,804 in 2026; workers’ wages rose 3.7 percent and inflation ran 2.7 percent over the same twelve months. KFF president Drew Altman connected the numbers to politics: “We have been hearing a lot about Affordable Care Act and Medicaid cuts. Now add a 9% increase in what workers with employer coverage paid toward family premiums in 2026 to the reasons voters are so concerned about their health care costs” (Healthcare Finance News, October 2026). The Milliman Medical Index, published mid-year, states that the total cost of care for a typical American family of four covered by an average employer PPO plan is projected at $37,824 in 2026, up 7.2 percent, or $8,460 per person, up 7.9 percent (Milliman, 2026). The federal baseline comes from the National Health Expenditure accounts: US health spending grew 7.3 percent in 2025 and reached 18.4 percent of GDP, with 91.7 percent of the population carrying insurance coverage (CMS Office of the Actuary via Health Affairs, 2026). Four publishers, four numbers, four different things. Now the denominators. Taking the denominators apart The KFF premium is a price, not a cost. The $28,303 family premium is the total annual price of an employer-sponsored insurance policy, employer share plus worker share combined, averaged over covered workers at non-federal public and private firms with ten or more employees, from 1,937 interviews conducted January through July 2026 (KFF, 2026). It excludes the under-65 population without employer coverage, deductibles, and out-of-pocket spending. KFF covers almost 157 million people under 65 through this lens, which is the survey’s own denominator for “employer-sponsored insurance”. The worker contribution is a slice of that price. The $7,471 is the worker’s share of the same family premium, about 26 percent of $28,303. When news stories say “workers’ bills jumped 9 percent,” the denominator is this slice, not the whole premium. The 5 percent premium growth and the 9 percent contribution growth coexist because employers shifted the split: among large firms, 44 percent increased employees’ share of premiums and 21 percent raised deductibles or other cost-sharing in response to projected cost increases (KFF, 2026). The Milliman figure is a cost, not a price. The $37,824 measures total cost of care for a family of four in an average employer PPO plan, including what employees pay out of pocket, projected actuarially (Milliman, 2026). It is a family-of-four unit, not a covered-worker unit, and a PPO plan, not the all-plan average. Milliman’s number being 33 percent larger than KFF’s premium is not a contradiction; it is a larger bucket. The national growth rate is a different economy entirely. The 7.3 percent NHE growth in 2025 includes Medicare, Medicaid, ACA marketplaces, out-of-pocket spending, and every premium dollar in the system, measured against the whole economy (CMS OACT, 2026). A national aggregate cannot be read as the trend facing a specific worker at a specific firm. In 2025 the large-group market decelerated while marketplace and government programs accelerated, so the national rate and the employer rate legitimately diverge. Cross-checks between the numbers Three internal consistency checks, each with a defined denominator. Check one: the five-year stack. Over the last five years, KFF’s family premium rose 28 percent, workers’ wages 26.9 percent, and inflation 24.4 percent (KFF, 2026). The premium has outpaced both wages and prices over the period, but only by 1 to 4 percentage points cumulative, which is a modest gap. This makes the single-year 9 percent worker contribution jump look less like a trend and more like an adjustment year after two unusually soft contribution years. Check two: the small-firm split. Workers at firms with 10 to 199 employees paid an average $9,687 toward family coverage in 2026, versus $6,840 at large firms, a gap of $2,847 in the 2026 survey year (KFF, 2026). Nearly a third of small-firm workers, 32 percent, were enrolled in plans requiring them to pay more than half the family premium, versus 6 percent at large firms. Single-coverage deductibles averaged $2,624 at small firms against $1,772 at large ones. The “average worker” the headlines describe is a blend of two very different populations. Check three: the forward-looking filings. Preliminary Marsh survey findings, fielded in October 2026, put employer expectations for 2027 health benefit cost growth at 8.2 percent per employee after planned changes, or 11 percent without them (Healthcare Finance News, 2026). Small-group insurers sought a median 14 percent premium increase for 2027 in their rate filings. These are proposals and expectations, not premiums paid, and they belong in a different column from KFF’s realized 5 percent. If KFF’s 2027 survey lands near 8 percent rather than 5, the filings will have been the better leading indicator. The employers’ playbook, 2026 edition The survey also records what employers did when they saw the cost curve coming, and the answers explain the 9 percent worker contribution number mechanically rather than mysteriously. Among large firms offering health benefits, 44 percent increased employees’ share of premiums in response to projected cost increases. 21 percent raised deductibles or other cost-sharing for most services. 16 percent changed insurers or plan administrators, and 10 percent added utilization management requirements such as prior authorization. Among firms with 5,000 or more employees, 66 percent had already raised worker contributions in anticipation of cost growth (KFF, 2026). Two structural details sharpen the picture. First, level-funded plans, a self-funded design with stop-loss insurance that had mostly been a large-employer instrument, now cover 38 percent of covered workers at small firms, moving small employers onto a claims-exposure model many of them do not fully understand (KFF, 2026). Second, the GLP-1 stalemate held: 18 percent of large firms covered the drugs for weight loss in 2026, unchanged from 2025 and 2024, 12 percent stopped covering them within the past year, and among firms that do cover them, 29 percent report significant prescription spending impact (KFF, 2026). A separate Business Group on Health survey found large-employer GLP-1 weight coverage falling from 72 percent to 60 percent between 2025 and 2026 (Insurance Business, October 2026). The 2026 worker contribution increase therefore lands in a year when employers were actively refusing one new cost category while shifting old ones to workers. The timing matters as much as the direction. The 44 percent of large firms that shifted premium share did so during 2026 plan years, meaning the change hit workers in the same twelve months that open enrollment messaging still described stable cost-sharing. And the 21 percent that raised deductibles did so while the average deductible was already 34 percent above its 2016 level, so the marginal worker at a small firm absorbed a contribution increase in 2026 on top of a decade of cost-sharing increases that preceded it. Table 2: The 2026 employer response to projected cost increases, large firms Action taken Share of large firms Ref Increased employees’ share of premiums 44% KFF 2026 EHBS Raised deductibles or cost-sharing 21% KFF 2026 EHBS Changed insurers or administrators 16% KFF 2026 EHBS Added utilization management 10% KFF 2026 EHBS Source: KFF What the average hides: plan types, regions, deductibles The single “average family premium” also blends plan designs and geographies that behave differently, and the differences matter for anyone renewing a policy in 2027. By plan type, workers enrolled in PPO plans carry above-average premiums, $10,272 for single coverage and $29,522 for family in 2026, while workers in HSA-qualified plans sit below the overall average at $8,989 and $26,450 (KFF, 2026). The spread is roughly 15 percent between the most and least expensive common designs, which means a firm changing its plan mix can report a slower premium increase without any worker’s actual plan getting cheaper. By region, the Northeast ran the highest premiums in 2026 at $10,806 single and $31,378 family, against the South’s $9,272 and $26,702 (KFF, 2026). A 5 percent national increase is consistent with near-zero growth in one region and 8 percent in another. Deductibles add a second layer the premium discussion skips. The average general annual deductible for single coverage among workers with one was $1,955 in 2026, statistically flat against 2025, but that calm headline sits on a steeper history: the same figure has risen 18 percent over five years and 34 percent over ten (KFF, 2026). More than half of small-firm workers, 55 percent, are now enrolled in a plan with a single-coverage deductible of $2,000 or more, against 33 percent at large firms. For that population the real annual exposure is contribution plus deductible, a number no headline prints. The 9 percent in historical context The worker contribution increase deserves its own denominator question: 9 percent of what baseline, and how unusual is it? KFF’s own reading is that the worker share of premiums held relatively stable for decades before 2026, which is why the survey flagged this year’s shift as a potential affordability turning point (KFF, 2026). A 9 percent rise on a $6,850 base, roughly where the 2025 family contribution sat, is $621. The same percentage applied five years ago would have been closer to $450 on the smaller base. The rate is new; the dollars are the accumulated base catching up. Who absorbs the increase also changed in 2026. At firms with 5,000 or more employees, 66 percent said they had already raised worker contributions in response to anticipated cost growth (KFF, 2026). At small firms, the pressure shows up in structure rather than announcements: nearly a third of their covered workers sit in plans requiring them to pay more than half the family premium, and 38 percent of small-firm workers are in level-funded designs where a bad claims year can flow back toward the employer, and eventually the workforce, at renewal. Where the numbers genuinely cannot be reconciled After the denominators are separated, one real inconsistency remains, and it is worth naming precisely. The 5 percent premium growth and the 9 percent worker contribution growth cannot both describe “what happened to the cost of family coverage” for a worker at a small firm, because KFF’s own small-firm data shows the worker share moving much faster than the premium. The reconciliation exists, employers absorbed less of the increase, but the average figures conceal it. A worker at a firm with 5,000 or more employees saw her contribution rise toward a $28,592 average premium with a 66 percent likelihood her employer raised her share in anticipation of cost growth (KFF, 2026). A worker at a 40-person firm faced a $27,288 premium and a one-in-three chance of paying more than half of it. The single-number story breaks exactly where the stakes are highest. A second, softer tension: NHE grew 7.3 percent in 2025 while employer premiums grew 5 percent in 2026. These are different years, different baskets, and different price bases, so no mathematical contradiction exists. But any story that quotes the national 7.3 percent next to the employer 5 percent as if they described the same phenomenon is committing a denominator error, and the pattern repeats in both directions across the 2026 coverage. Verdict The 2026 numbers, correctly read, say this. The sticker price of employer family coverage rose 5 percent to $28,303. Workers’ share of that sticker rose 9 percent because employers pushed cost-sharing down the hill, especially at small firms, where nearly a third of covered workers now pay more than half the premium. The underlying cost of care, measured actuarially, runs 7.2 percent. The system as a whole grew 7.3 percent in 2025 against an economy where wages rose 3.7 percent. Nothing in that set is fraudulent, and nothing in it is a simple sentence. For the audit, one rule carries the verdict. Quote any of these numbers without its denominator and you will mislead a reader, including, most weeks, yourself. The figure most likely to be misused in 2027 arguments is KFF’s 5 percent, because it is the lowest number in the set and the only one that describes a price rather than a bill. For a benefits manager renewing in January 2027, the practical translation is unglamorous. Expect an 8 percent cost trend before plan changes, per the Marsh expectations, which means the 2026 playbook of shifting share to workers has one more round left in it before the affordability question moves from the benefits team to the compensation committee. For a journalist quoting the 2026 batch, the rule is simpler: name the denominator or drop the number. And for the 32 percent of small-firm workers already paying more than half their family premium, no denominator hides the fact that their bill grew twice as fast as the premium everyone is quoting. Methodology This audit used four primary sources: KFF’s 2026 Employer Health Benefits Survey (28th annual, 1,937 employer interviews, fielded January to July 2026, non-federal public and private firms with 10 or more workers), the Milliman Medical Index 2026 (actuarial projection of total cost of care for a family of four in an average employer PPO plan), the CMS Office of the Actuary National Health Expenditure data for 2025 as published via Health Affairs, and secondary trade coverage (Healthcare Finance News) for the Marsh 2027 expectations and small-group rate filings. For each figure, we recorded the denominator as defined by its publisher before comparing numbers. Time frames are 2026 realized premiums, 2025 national expenditure, and 2026-2027 projections. We did not reweight or adjust any source’s figures, did not mix projection with realized values, and treated the small-group 14 percent median filing as a proposed rate rather than a cost. Definition of “increase” follows each publisher’s own year-over-year comparison. Data as of November 2026. Limitations: KFF’s survey is employer-reported and excludes federal employers and firms under 10 workers. Milliman’s index is a projection, not an invoice. The Marsh figure is preliminary. No source here measures the uninsured population’s costs. Sources KFF , 2026 Employer Health Benefits Survey, October 22, 2026 Healthcare Finance News , Family health premiums top $28,000 as worker contributions rise 9%, October 2026 Health Affairs , CMS OACT national health expenditure projections, 2026 CFH Insurance Center , Milliman 2026 Medical Index comparison, 2026 Insurance Business , Small-firm workers pay $2,823 more for family coverage, October 2026 About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
Saudi Arabia After Cash: Where the Payment Shift Stalls First SeaPRwire

Saudi Arabia After Cash: Where the Payment Shift Stalls First

Instant payments, mada e-commerce and the retail rails moving SAR 101 billion a quarter: the structural read on who loses when the Kingdom stops carrying banknotes Saudi Arabia’s retail payments crossed a line in 2025 with little ceremony. The Saudi Central Bank reported that electronic payments made up 85 percent of all retail transactions by the end of that year, against 79 percent in 2024 and 70 percent in 2023, with e-payment volume reaching roughly 14.6 billion transactions in 2025, up from 12.6 billion the year before (SAMA, Key Economic Developments, Q2 2026). Three years earlier, a wallet was a novelty in a Jeddah grocery line. Now the question worth asking is no longer whether the Kingdom goes cashless, but which parts of the old payment stack lose their economic reason to exist first, and how you would know if the answer is wrong. The phenomenon, stated plainly, is that three separate rails are all growing at once. Instant transfers moved SAR 18.4 trillion of value in a single quarter of 2026. Online card spending through the domestic network grew faster than any comparable economy tracks it. And the state’s licensing pipeline, 32 licensed payment companies by May 2026 and open banking providers formally licensed from March, keeps adding rails beneath rails. What follows is the attempt to say who pays for that success, and when. The visible growth numbers all point one way. But a structural read requires separating the headline from the mix, and the mix is starting to tell a more complicated story than “cash is dying”. Two leading indicators, tracked independently, suggest the displacement is entering its second phase: value growth is migrating away from retail rails toward interbank settlement, while retail growth shifts from value to volume. That shift has losers, and they are not the ones the cashless narrative usually names. The phenomenon, stated with its numbers The official series is unambiguous about direction. Electronic payments as a share of retail transactions rose from 70 percent in 2023 to 79 percent in 2024 to 85 percent in 2025 (SAMA, 2026). The SARIE instant payment system carried a total transaction value of SAR 17,777.1 billion in the first quarter of 2026, up 16.1 percent year on year, and SAR 18,399.2 billion in the second quarter, up 12.7 percent (SAMA, 2026). Mada e-commerce sales, the domestic debit network’s online channel, reached SAR 101.4 billion in the second quarter of 2026, up 32.3 percent from SAR 76.6 billion a year earlier, after full-year 2025 e-commerce sales grew 64.7 percent to SAR 325.20 billion (SAMA bulletin via Saudi Gazette, September 2026; Leaders MENA, September 2026). Table 1: Saudi retail payment rails, 2024-2026 Measure Value Period Ref Electronic share of retail transactions 85% End of 2025 SAMA SARIE total value, Q2 2026 SAR 18,399.2 billion Q2 2026, +12.7% YoY SAMA Mada e-commerce sales, Q2 2026 SAR 101.4 billion Q2 2026, +32.3% YoY SAMA bulletin POS terminal sales, Q2 2026 SAR 170.1 billion Q2 2026 SAMA bulletin ATM cash withdrawals, Q2 2026 SAR 125.4 billion Q2 2026 SAMA Cheques cleared, Q2 2026 131.2 thousand Q2 2026 SAMA Source: SAMA , Saudi Gazette At the same time, the regulatory scaffolding for the next layer went up. In March 2026 SAMA commenced licensing fintech companies for open banking services after completing the sandbox phase, licensing its first account-information providers that month (SAMA, 2026-03-26). By May the count of licensed payment services companies had reached 32. The buy-now-pay-later firms Tabby and Tamara, licensed in 2025, moved into broader consumer and SME finance, with Tabby authorized in June 2026 for purchases up to SAR 50,000 over twelve months (echosource, 2026). The structural variable: volume growing faster than value The variable that actually drives the next three years is not the 85 percent share. It is the divergence between how much Saudis transfer and how often they do it. Look inside the SARIE numbers. The system’s headline value rose 12.7 percent year on year in the second quarter, but customer payments, the retail-facing component, rose only 2.2 percent, from a base of about SAR 4,333.7 billion. Interbank payments, the wholesale plumbing, grew 18.9 percent. The first quarter showed the same asymmetry: customer payments up 8.2 percent against a 16.1 percent headline (SAMA, 2026). Meanwhile the transaction counts on the retail side are exploding. Consumers completed 196.93 million mada e-commerce purchases in August 2026, up 27.3 percent from 154.68 million a year earlier, while mobile POS transactions, 632.49 million of them in the month, now outnumber physical card transactions, 438.90 million, by half again (Leaders MENA, September 2026). Put together, the pattern reads clearly. The average Saudi retail transaction is getting smaller and more frequent. Value growth in retail rails is decelerating toward nominal GDP, while volume growth runs at three to five times that pace. The cash-to-digital migration is shifting from a substitution story, replacing cash value with digital value, to a granularity story, slicing the same spending into many more digital pieces. A shift of that shape does not mainly threaten cash. It mainly threatens any business model priced per transaction or per ticket. Where the variable is heading Three trajectories follow from the mix shift, each with its own pace. First, the share of retail transactions paid electronically should keep climbing but with diminishing returns, since each percentage point now costs more to convert than the last. The remaining 15 percent of retail transactions is likely concentrated in small tickets, rural geographies, and informal settings where terminal economics are weakest. Second, retail payment value growth should converge toward consumption growth, roughly the 6.35 percent year-on-year rise in total consumer spending recorded for August 2026 (SAR 142.02 billion, Leaders MENA, September 2026), while e-commerce keeps taking an increasing slice of that spend from physical POS. The July numbers already show it: POS sales grew 6.8 percent year on year while mada e-commerce grew 26 percent (Saudi Gazette, September 2026). Third, instant-payment rails should keep growing in value mostly through interbank and large-ticket use, with SARIE’s retail component growing through volume, consistent with the system’s design as a utility rail rather than a card competitor. The first two quarters of 2026 already sketch the curve: customer payment value grew 8.2 percent year on year in the first quarter and 2.2 percent in the second, while interbank settlement ran at 20.5 and 18.9 percent over the same two quarters (SAMA, 2026). If that pattern holds through 2027, retail instant payments will look less like a growth engine and more like mature infrastructure, which is exactly the condition under which the businesses layered on top of it, acquirers, terminal fleets, cash logistics, start feeling competitive pressure rather than riding volume growth. The rails behind the headline, month by month The quarterly totals compress a monthly story worth reading, because the mix shift shows up there first. In July 2026, mada e-commerce sales hit SAR 37.6 billion, up 26 percent from SAR 29.8 billion in July 2025 and up 11.8 percent from June’s SAR 33.6 billion (SAMA bulletin via Saudi Gazette, September 2026). August held the same pace: SAR 36.95 billion of mada online spending, up 26.03 percent year on year, across 196.93 million transactions, up 27.3 percent from 154.68 million a year earlier (SAMA bulletin via Leaders MENA, September 2026). The physical rails grew too, just slower and thinner. July POS sales reached SAR 59.7 billion, up 6.8 percent year on year, of which mobile-phone transactions carried SAR 34 billion against SAR 25.7 billion on physical cards (Saudi Gazette, September 2026). August’s POS figures confirm the pattern: SAR 65.69 billion, up 4.98 percent year on year, spread over more than 1.1 billion individual operations across a terminal fleet of 2.47 million devices (Leaders MENA, September 2026). Mobile POS, 632.49 million transactions worth SAR 35.70 billion, outnumbered physical card transactions, 438.90 million worth SAR 26.67 billion, by nearly half again. Where the money went in August 2026 is a map of how digital the everyday economy already is. Grocery and food suppliers led POS spending at SAR 10.28 billion, restaurants and cafes took SAR 7.90 billion, apparel SAR 5.73 billion, transport SAR 4.86 billion, fuel stations SAR 4.55 billion, and healthcare providers SAR 3.86 billion (Leaders MENA, September 2026). None of those categories is exotic. The shift is not about luxury e-commerce; it is about lunch and fuel and pharmacy runs settling on rails that did not exist at this scale five years ago. The ticket size arithmetic Dividing published totals produces the number the bulletins do not print, and it is the number that squeezes everyone paid per transaction. In the first quarter of 2026, POS terminals processed about 2,982.6 million transactions worth SAR 189.7 billion, an average ticket of roughly SAR 64 (computed from SAMA, Q1 2026). In the second quarter, transactions rose to about 3,153.7 million while sales fell to SAR 179.0 billion, an average ticket of roughly SAR 57 (computed from SAMA, Q2 2026). July’s monthly figures put the average near SAR 54. The same arithmetic shows what cash still looks like when it is used. Average ATM withdrawals ran about SAR 381 per transaction in the first quarter, SAR 136.8 billion across 359.0 million transactions, and about SAR 312 in the second, SAR 125.4 billion across 401.6 million (computed from SAMA, 2026). Cash survives as a large-ticket, low-frequency instrument while cards, and increasingly phones, absorb the small, frequent end of the economy. An acquirer whose revenue model assumes a stable ticket size is watching that assumption erode at roughly 10 percent per quarter. The new rails coming online While the old mix erodes, the replacement infrastructure reached commercial operation in 2026. SAMA commenced licensing fintech companies for open banking services on March 26, 2026, after completing the regulatory sandbox phase, and licensed its first account-information providers the same month (SAMA, 2026-03-26). By May the count of licensed payment services companies had reached 32 (echosource, 2026). The buy-now-pay-later firms that defined the previous wave formalized broader licenses: Tamara received its consumer finance and BNPL license in March 2025, Tabby followed in November 2025, and in June 2026 Tabby secured consumer and SME finance licenses permitting purchases up to SAR 50,000 over as many as 12 monthly payments (echosource, 2026). The listed fintech Rasan reported 2025 revenue growth of 82 percent with adjusted net income nearly tripling, evidence that regulated Saudi fintech can already scale (company earnings, February 2026). Two further rails matter for the structural read. SAMA announced at the Money20/20 Middle East conference in September 2026 that Tap to Pay on iPhone is coming to Saudi Arabia, removing the last hardware excuse for cash-heavy micro merchants (SAMA, 2026-09-14). And the central bank opened a public consultation in February 2026 on draft rules for cash center management and operation, the administrative acknowledgment that the cash layer needs reorganizing rather than expanding (SAMA, 2026-02-17). Who gets hit first The businesses priced for the old mix lose first, in this order. Cheque infrastructure. Saudi clearing houses processed 131.2 thousand cheques in the second quarter of 2026, of which 93.0 thousand were individual and corporate (SAMA, 2026). A national system now clearing six figures of cheques per quarter, against billions of instant transfers, has no growth story left; the only open question is the cost of running it down. Cash logistics at the margin. ATM cash withdrawals totaled SAR 125.4 billion in the second quarter, down from SAR 136.8 billion in the first, across roughly 401.6 million ATM transactions and 14.4 thousand machines (SAMA, 2026). Cash still moves enormous value, but its growth is gone; cash-in-transit operators, ATM deployers and cash-center services face flat-to-declining volumes with fixed route costs. SAMA’s own draft rules on cash center management, published for consultation in February 2026, signal the state is already reorganizing this layer. POS acquirers and terminal economics. The terminal fleet keeps growing, from about 2.4 million devices in the first quarter of 2026 to 2.47 million by August (SAMA, 2026), even as the average ticket shrinks. With 2.47 to 2.5 million active POS terminals and average ticket sizes falling as mobile taps multiply, the per-transaction revenue on a SAR 54 average purchase gets thin. Terminal fleets still grow, but the revenue per terminal story weakens first, and the July POS figure of SAR 59.7 billion against 1.1 billion transactions shows tickets averaging around SAR 54. A market adding terminals at this pace while tickets shrink is buying redundancy ahead of revenue. Card-scheme transaction fees at the low end. Mada’s own dominance, plus contactless mobile issuance such as the Tap to Pay on iPhone launch announced for Saudi Arabia at Money20/20 in September 2026 (SAMA, 2026), shifts low-value volume onto debit rails where interchange is minimal. The premium end of card economics survives; the convenience-store end erodes. What signals the read is wrong This analysis has falsifiable edges, and honesty requires naming them. The strongest counter-signal is the ATM transaction count itself: ATM transactions rose from 359.0 million in the first quarter to 401.6 million in the second of 2026 (SAMA, 2026). If that quarterly climb persists on a year-on-year basis, cash usage is not declining in volume terms and the cash-logistics obsolescence argument stalls for years. The second counter-signal is SARIE customer payment value: if retail instant value growth reaccelerates above 10 percent annually, the “value moving wholesale” thesis is wrong and retail instant transfers are still in their substitution phase, which would push the disruption timeline later for POS acquirers. The third is the open-banking layer: if payment initiation, now only beginning to be licensed, takes material volume from card acquiring within two years, the loser list lengthens; if it remains an account-information service, the acquiring model endures longer than this analysis implies. Data as of November 2026. Data basis Primary figures come from SAMA’s official publications: the Key Economic Developments reports for Q1 and Q2 2026 (SARIE values and growth, ATM and POS volumes, cheque clearing, e-payment share of retail transactions for 2023-2025) and the monthly statistical bulletin as reported by Saudi Gazette for July 2026 and Leaders MENA for August 2026. The denominator definitions matter: electronic share of retail transactions counts transaction count, not value; SARIE customer payments exclude interbank settlement; mada e-commerce excludes Visa and Mastercard online spend, so total e-commerce is understated by those rails. Open banking and fintech licensing milestones come from SAMA press releases of March 2026 and trade summaries. No figure in this article is a projection of ours; the three trajectories described are inferences from published growth differentials, marked as such. Saudi Arabia’s retail data is unusually complete by international standards, but monthly bulletins get revised, and Q2 figures here may shift in later releases. Data as of November 2026. Limitations: monthly consumer spending aggregates include cash withdrawals and cannot be decomposed into cash versus digital from the published releases; the ATM quarterly comparison is sequential, not year-on-year, because no YoY ATM figure was available; open banking payment-initiation volumes are not disclosed. Sources SAMA , Key Economic Developments Second Quarter 2026 SAMA , Key Economic Developments First Quarter 2026 Saudi Gazette , E-commerce sales surge 11.8% to SR37.6 billion in July, September 2026 Leaders MENA , Saudi consumer spending reaches SAR 142B in August 2026, September 2026 SAMA , SAMA commences licensing of open banking fintechs, March 26, 2026 echosource , Saudi fintech 2026: licensing, BNPL and open banking status About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
The UAE’s AI Adoption Is a World Record. Paying for It Is Another Story SeaPRwire

The UAE’s AI Adoption Is a World Record. Paying for It Is Another Story

Enterprise AI in the UAE, 2026: what 73.3% national adoption means for businesses, against the 29% that actually pay for tools In the third quarter of 2026, the typical UAE business that paid for an AI tool spent AED 268 a month on it, according to the first SME Spend Index from Pemo, a Dubai spend-management platform (Pemo, October 2026). That is roughly the cost of a modest office utility bill. In the same quarter, Microsoft’s diffusion tracking put the share of UAE residents aged 15 to 64 who had used a generative AI product at 73.3 percent, the highest reading across 147 economies (Microsoft, September 2026). Both numbers describe the same country in the same year. Only one of them describes a purchase. The gap between those two figures is the most important unsolved question in the UAE’s AI story. The country leads the world in people trying AI. It has built government infrastructure around that lead. What it has not yet shown, at anything close to the same scale, is businesses converting that usage into paid, integrated, budgeted deployment. This article reads the two data trails against each other, adds what the people operating these tools actually say, and asks a simple question: is the gap one problem or two? The record number, and what it actually counts Microsoft’s AI Economy Institute measures diffusion as the share of people aged 15 to 64 who used a generative AI product or app during a reporting period, based on aggregated telemetry adjusted for device market share and internet penetration (The National, 2026-09-25). On that measure the UAE ran 59.4 percent in the first half of 2025, 64.0 percent in the second half, 70.1 percent in the first quarter of 2026, and 73.3 percent in the second quarter. The global average rose from 16.3 percent to 17.8 percent over the same quarter. Singapore, second on the list, reached 64.3 percent. Three things about that measure matter for reading it honestly. It counts a population, not a workforce. A student using a free chatbot and a procurement officer using an enterprise assistant both sit inside the 73.3 percent. It counts any generative AI product, not paid business tools. Free tiers qualify. It is a usage read, not an outcome read. Nothing in it says what the usage changed. Microsoft UAE’s own managing director drew the same line in October 2026. “The biggest shift we are seeing is from AI as a tool to AI as a teammate,” Amr Kamel said at the AI Everything Abu Dhabi showcase, adding that human judgement and accountability “remain at the centre” (Zawya, 2026-10-06). The framing is notable for what it concedes: the vendor that publishes the headline adoption number is also the vendor telling businesses that adoption is no longer the hard part. A company report released the same month put it more bluntly, saying businesses “now have to show the productivity and financial returns behind that usage” (tbreak, October 2026). How many businesses are actually paying The business-side numbers come from three private sources, and they disagree with each other in instructive ways. The AWS “Unlocking the UAE’s AI Potential” report, produced with the UAE Artificial Intelligence Office and research by Strand Partners, found 72 percent of UAE businesses say they have adopted AI in 2026, up from 53 percent a year earlier (AWS, 2026). That survey asked 1,000 founders, CEOs and C-suite members through online panels weighted by size, sector and region. A “yes” here is a self-declaration. Pemo’s transaction data cuts the same market by what firms actually pay for. Its first AI adoption report, built on settled card and bill-pay transactions from more than 6,000 UAE businesses and over AED 1.4 billion in annual spend, found 12 percent of businesses actively transacting with AI tools in early 2026 (Pemo, April 2026). Its Q3 2026 SME Spend Index, based on roughly 3.5 million anonymised transactions from October 2025 to September 2026, found 29 percent of businesses paid for at least one AI tool, with AI spend about five times its year-ago level and now roughly a quarter of all software spending (Pemo, October 2026). Two details inside that index deserve attention: two-thirds of AI-paying businesses still used a single tool, and the index excludes AI capabilities bundled inside Microsoft and Google suites, so the true paid share is somewhere above its read, not below. The same index shows where paying already runs deep. Technology firms led at 50 percent paying for AI in the third quarter of 2026, with a typical AED 880 a month. Marketing agencies followed at 46 percent. Real estate reached 38 percent and professional services 35 percent by the third quarter of 2026, while construction sat at 17 percent and hospitality at 16 percent. Table 1: What each UAE adoption number measures, 2026 Measure Value What it counts Ref Residents 15-64 using a GenAI product, Q2 2026 73.3% Any generative AI usage, free or paid, telemetry-based Microsoft AI Diffusion Businesses self-reporting AI adoption 72% Founder/CEO survey answer, 1,000 firms, online panel AWS / Strand Partners Businesses paying for at least one AI tool, Q3 2026 29% Settled card and bill-pay transactions, ~3.5M records Pemo SME Spend Index Businesses transacting AI spend, early 2026 12% Confirmed transactions among 6,000+ firms Pemo AI adoption report Source: The National , Pemo via Communicate Online There is no official UAE government statistic on business AI use. Every business figure in circulation comes from a vendor survey or a company’s own transaction data, and each one counts a different denominator. Treat any single number, including the 73.3 percent, as one lens on one population. What the operators say The public record of people running these tools inside UAE organisations is thin but consistent, and it splits into two camps: those describing deployment momentum, and those warning that deployment is where projects die. Amr Kamel, Microsoft UAE managing director, told Gulf News that companies should focus on “measurable outcomes rather than the number of pilots they launch”, arguing AI could help organisations take on more work and “tackle tasks that previously needed more time or specialist expertise” (tbreak, October 2026). Ayham Gorani, co-founder and chief executive of Pemo, framed spending as the honest signal: “Spending is one of the clearest signals there is: it shows what businesses prioritise, where they see growth and what they are prepared to invest in” (Pemo, October 2026). On the other side sits the largest piece of counter-evidence in the enterprise AI literature. MIT’s Project NANDA report, The GenAI Divide: State of AI in Business 2025, found about 95 percent of enterprise generative AI pilots delivered no measurable profit-and-loss impact, based on 300 public deployments, 150 leadership interviews and a survey of 350 employees (Fortune, 2025-08-18). “The 95% failure rate for enterprise AI solutions represents the clearest manifestation of the GenAI Divide,” the report stated. Its lead author, Aditya Challapally, said the root cause was not model quality but a learning gap in integration: “Almost everywhere we went, enterprises were trying to build their own tool.” Purchased solutions succeeded about 67 percent of the time in the study; internal builds, about one-third as often. That report predates the UAE’s 2026 surge and was not a UAE study. But it describes the failure mode that high-adoption economies run into first, because adoption without integration is exactly the pattern it measured. No UAE-specific equivalent of the MIT study exists in public. That absence is itself a finding. A third camp is quieter: the sector laggards. Pemo’s own index shows construction and hospitality firms paying for AI at roughly half the rate of technology firms. Gorani’s data says the gap is a budget line, not a technology choice. Two gaps, not one So which is it: is the UAE’s usage-to-payment gap a single problem, or two conditions that have to hold at once? The evidence supports two, and they fail independently. Gap one is a measurement gap. The headline 73.3 percent counts people using free generative AI. The paid-enterprise share sits far lower, between the 12 percent transacting and the 29 percent paying depending on how strictly you define a payment. Nothing is broken here; the two numbers measure different populations. But the gap guarantees that most public commentary overstates how deep AI runs in the economy. When the federal government announced in April 2026 that half of government services should run through AI agents within two years, it set a deployment target, not a usage target. The diffusion index cannot track progress toward it. Gap two is a conversion gap. Moving from a single paid tool to organisation-wide deployment requires two inputs the market is short of. The first is people: UAE businesses report it takes an average of 5.8 months to hire an employee with the right digital skills, and only 31 percent of businesses describe themselves as at the most advanced stage of AI use, up from 28 percent a year earlier (AWS, 2026). The second is integration discipline: the MIT study’s core finding, that generic tools stall inside enterprise workflows because they do not learn from them, applies to any market buying the same tools. The UAE’s own spend data shows the conversion is happening but slowly: two-thirds of paying firms still run one tool, and 37 percent run two or more. If only gap one existed, the fix would be re-labelling the statistics. If only gap two existed, the headline number would be a fair signal of future deployment. Because both hold, the 73.3 percent is neither a lie nor a forecast. It is a measure of interest, and interest is the cheapest input in the entire stack. The public money behind the private gap None of this happens in a policy vacuum, and the state’s own programs explain part of the usage surge while exposing how little of it converts. The UAE was the second country after Canada to publish a national AI strategy, back in 2017, and the accumulation shows. In April 2026 the federal government announced an AI framework targeting 50 percent of government sectors, services and operations running through agentic AI within two years, alongside a plan to train 80,000 federal employees, from ministers to new joiners, in agentic AI (The National, 2026-09-25). Abu Dhabi’s Digital Strategy 2025-2027 carries an AED 13 billion investment, targets 100 percent sovereign cloud adoption, more than 200 AI solutions, and an ambition to add over AED 24 billion to the emirate’s GDP by 2027 (Analytics Insight, 2026). The emirate reports more than 1,000 AI agents planned across government operations. The capital layer moved in parallel. Abu Dhabi’s MGX closed its first fund at USD 49 billion in July 2026, above its original USD 45 billion target, invested across 14 companies in semiconductors and AI infrastructure. OpenAI named Stargate UAE its first international deployment, a 1 gigawatt cluster in Abu Dhabi with 200 megawatts expected live in 2026, alongside G42, Oracle, NVIDIA, Cisco and SoftBank. In September 2026, Abu Dhabi’s Institute for Foundation Models released six open-source models, the largest at 375 billion parameters (Analytics Insight, 2026). Talent metrics confirm the pipeline is real. PwC counts UAE job postings requiring AI skills at 3.2 percent of postings in 2025, up from 1.0 percent in 2021, a rise of roughly 2,700 postings in the last year alone. AI is now taught in government schools from kindergarten to grade 12, and 22,000 teachers are being trained to use it in assessment and lesson planning (The National, 2026-09-25). Read against the spend data, though, the public programs buy usage, not conversion. Government employment gives 35,000 people Copilot at public expense, which lifts the diffusion number. The AED 13 billion strategy funds infrastructure that private SMEs then use cheaply or free, which lifts the diffusion number further. What no program yet does is pay for the last mile inside a 12-person marketing agency in Sharjah: the integration work, the workflow redesign, the second and third tool beyond the first subscription. That gap is precisely where the MIT finding lives, and no public money in the current wave targets it. Who never sees the gap The people least exposed to this two-gap structure are the ones consuming the headline number. A diffusion statistic travels well: it is quotable, it ranks the country first, and it has made the UAE a fixture of global AI commentary. The transaction data that would complicate the story sits inside a private platform’s customer base of roughly 10,000 businesses and reaches the public once a quarter, in a press release. Government momentum amplifies the same asymmetry. Abu Dhabi has rolled Microsoft 365 Copilot out to about 35,000 public-sector employees across 27 government entities, under an AED 13 billion digital strategy targeting more than 200 AI solutions and an ambition to become the world’s first AI-native government by 2027 (Zawya, 2026-10-06; Analytics Insight, 2026). Ajman put a fully agent-driven proactive licensing service into operation in September 2026. Each of these is a genuine deployment. None of them is an SME, and the SME market, where 59 percent of Pemo-tracked AI spend now originates, is where the conversion gap lives. The vendors sit closest to the gap and profit from narrating the top half of it. The AWS survey was researched for a company that sells cloud and AI services; Pemo sells spend management and publishes its own index; Microsoft publishes the diffusion ranking. None of this makes the numbers wrong. It does mean the correction to the record will not come from inside the market. It will come from whatever independent survey or regulator disclosure arrives first. What would tell us the picture changed Three signals are cheap to watch and directly test the two-gap structure. Pemo’s Q4 2026 index, due January 2027: if the share of businesses paying for two or more AI tools rises materially from 37 percent, the conversion gap is closing. The sector spread: if construction and hospitality payment rates move above the low twenties, the gap has stopped being a sector story. The federal government’s own deployment reporting against its 50 percent agentic-AI target, which, unlike the diffusion index, has an auditable denominator. Until one of those moves, the honest summary of the UAE in late 2026 is this: a country that has solved getting people to try AI, and is only beginning to solve getting businesses to pay for it, one AED 268 budget line at a time. Sourcing and ethics note This article rests entirely on published material: Microsoft’s AI diffusion reporting as covered by The National, Pemo’s two spending reports as distributed to UAE business media, the AWS and Strand Partners survey, and MIT’s Project NANDA report as reported by Fortune. Quotes come from named executives in their published statements; no unnamed sources were used. Where reports disagree, the disagreement is presented with each figure’s own denominator rather than averaged away. The Pemo data covers that platform’s customers and is not a representative sample of all UAE businesses, and its AI category excludes tools bundled in Microsoft and Google suites, a limitation the publisher itself flags. The MIT study is global and predates the UAE’s 2026 readings; it is used here as documented evidence of a failure mode, not as a UAE measurement. Data as of November 2026. Sources The National , UAE pulls ahead in global ranking on AI adoption, September 25, 2026 Zawya , AI Everything Abu Dhabi press release with Kamel quotes, October 6, 2026 Communicate Online , Pemo SME Spend Index Q3 2026, October 2026 CB Insights , Pemo UAE AI adoption report, spend up 521%, April 2026 Fortune , MIT NANDA report: 95% of GenAI pilots failing, August 18, 2025 tbreak , Microsoft UAE on Q1 2026 diffusion and Frontier Firms, October 2026 About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
Tanjung Priok’s Landside Bottleneck Keeps Jakarta Box Rates High SeaPRwire

Tanjung Priok’s Landside Bottleneck Keeps Jakarta Box Rates High

The Drewry Intra-Asia Container Index climbed 46 dollars to 1,504 dollars per 40-foot container in the week reported on 5 November 2026, and the port doing most of the pushing is Jakarta’s Tanjung Priok, where sudden, unscheduled multi-ship arrivals overwhelm landside roads and container depots already at full capacity. The terminal side is not the problem. State operator Pelindo’s container terminal subsidiary moved 10.31 million TEUs from January to September, up 5.8 percent on the year, while the road project meant to fix access, New Priok Eastern Access, only broke ground in July and needs 20 months to finish. Independent shipping reports in the same window describe the same picture from the outside: vessel bunching, congested roads and limited container depot capacity adding to operational difficulties at Tanjung Priok, with container availability and shipping costs affected even as rates on some other global routes begin to ease. The regional pattern matters for buyers booking into Indonesia this quarter. Where the major hubs recovered, the premium on the Jakarta lane reflects a structural landside gap, not a temporary vessel bunching episode that a normal weekly schedule can work off. The rates behind the headline The index move compresses two opposite stories into one number. Major gateways absorbed their congestion: spot rates out of greater China to north-east, south-east and south Asia were mostly stable for the week as the largest hubs cleared their backlogs, and some of those big lanes actually eased. Two of the easing lanes set the benchmark. Rates from Shanghai to Singapore fell 3 percent to 1,889 dollars per 40-foot container, and those to Tanjung Pelepas declined 2 percent to 2,053 dollars. The secondary ports went the other way. Rates out of Shanghai to Jakarta and Laem Chabang stayed high and kept rising through the week. The reverse lane carried the sharpest single move. Jakarta to Shanghai rates rose 9 percent from the previous week at the end of October, to 81 dollars per 40-foot container, and the Shanghai Containerised Freight Index showed the Shanghai to south-east Asia rate up 2 percent from 30 October, to 1,164 dollars per TEU. In Ho Chi Minh City, average vessel waiting times rose from eight hours to 22 hours within a fortnight. What is jammed, and where Tanjung Priok’s problem is not berth capacity but the sequence after the berth. Multi-ship arrivals that were never on the published schedule land together, and the trucks, container yards and access roads that serve the terminals are already running full. The landside cannot drain what the waterside delivers, so yard density climbs and turnaround slows. A forwarder at Taiwan-based logistics firm Dimerco told The Loadstar that Jakarta’s landside logistics had not caught up with the improvements in terminal capacity. The consequence he described runs through equipment: slow container turnaround makes shipping lines reluctant to absorb the cost of repositioning empty containers, and that local equipment shortage drives up the price of the containers that remain available. For shippers, the visible symptom is the rate premium; the underlying mechanism is empty-container economics at a port that cannot turn boxes quickly enough to let lines balance their fleets. The operator’s own numbers Pelindo Terminal Petikemas’ operating disclosure, released through the company secretary on 2 November, confirms the demand side. Container traffic from January to September 2026 reached 10.31 million TEUs, up 5.80 percent year on year, with international traffic up 10.34 percent to 3.54 million TEUs against domestic growth of 3.57 percent on 6.77 million TEUs. International trade growth outpacing domestic means the berths and yards serving foreign services carry the heavier load, and that is exactly where bunching bites. The company’s response list is conventional capacity: four quay cranes and 14 electric rubber-tyred gantries for the Tanjung Priok container terminal through 2026. Similar crane and gantry additions are planned across its Central Java, Sumatra and Kalimantan terminals, and two more quay cranes at its Riau site are targeted for December. Corporate secretary Fajar Setyono attributed the growth to international vessel services, new shipping service additions and terminal optimisation. One terminal inside the network shows how irregular demand lands on top of scheduled work: Teluk Lamong grew throughput 23.12 percent, helped by 25 non-regular, ad hoc international vessel calls totalling 16,014 TEUs as of September, on top of two new joint loops, a COSCO and OOCL service and a Gold Star Line and X-Press Feeders service, each averaging around 1,100 TEUs per call. Ad hoc calls are the unit of cargo that bunching is made of, and their share of growth says the schedule discipline problem is growing with the trade. Capacity arrives, access lags The infrastructure mismatch has dates attached. In August, Pelindo preliminarily launched Terminal 2 Petikemas, adding container capacity at the port. Construction of New Priok Eastern Access, the road intended to improve landside access, started in July 2026 and will take 20 months, putting completion in the first half of 2028. Until that road opens, every terminal upgrade raises the ceiling of what the port can discharge without raising the floor of what its roads can drain, which is the mechanics of bunching recurring. Indonesian logistics industry representatives acknowledge the gap. The maritime and port affairs deputy chairman of the national forwarders association said Java’s ports handling international trade are relatively adequate for service users’ needs, while ports in eastern Indonesia still have a long way to go, and that terminals open to international trade are visibly upgrading their equipment. The caveat behind the reassurance matches the road timeline: the constraint is not intent, it is the 20-month construction calendar. What shippers can work with New service capacity gives planners one more lever. Pacific International Lines launched its JKS service on the day the index was reported: a fortnightly loop with two vessels of 1,900 to 2,600 TEUs calling at Laem Chabang and Jakarta en route from the city-state hub, adding scheduled capacity to the Malacca Strait feeder trade. A fortnightly fixed-day loop does not remove bunching, but it gives bookings a vessel with a published window at a port where unscheduled arrivals are the problem. Beyond the new loop, the workable responses are sequencing and cost attribution. Bookings that can ride the fixed-day services avoid contributing to bunching and price closer to published rates. Shipments that must follow the cargo should carry the congestion premium explicitly in landed cost, because equipment surcharges and yard delays will surface in detention, demurrage and container-availability charges rather than in the base rate alone. Alternative Indonesian ports can absorb some cargo, but not every commodity type or vessel size, and shifting origin ports has its own inland-haulage cost. The timeline to watch The premium persists until the landside catches up, and the calendar says when. New Priok Eastern Access completes around early 2028; until then, unscheduled multi-ship arrivals will keep overwhelming roads and depots at full capacity, and secondary-port rate spikes on the Jakarta lane will recur each time vessel schedules cluster. Watching three numbers covers most of the exposure: the weekly Drewry intra-Asia reading for direction, the Jakarta to Shanghai spot rate as the reverse-lane pressure gauge, and Pelindo’s quarterly throughput disclosures for the demand curve that determines how hard the constraint binds. Sources The Loadstar (Alison Koo), “Continued congestion at ports puts pressure on intra-Asia box rates,” 2026-11-05. ISL News TV, “Pelindo Terminal Petikemas Records 10.3 Million TEUs of Container Throughput, International Trade Grows Rapidly,” 2026-11-02 (operator disclosure via corporate secretary Fajar Setyono). Drewry, Intra-Asia Container Index (IACI), week reported 2026-11-05, via The Loadstar. Hylios, “Intra-Asia Container Rates Rise to 1,504 Dollars Amid Southeast Port Chaos,” 2026-11. Guidance Corp, “Port Congestion and Container Shortages Push Up Freight Costs Across Asia,” 2026-11. This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Netherlands Article 23 vs Germany: Import VAT Timing After New Fees SeaPRwire

Netherlands Article 23 vs Germany: Import VAT Timing After New Fees

Two fee changes landed on European e-commerce imports within four months. The European Union abolished the customs duty exemption for shipments worth up to EUR 150 on 1 July 2026, and from 1 November 2026 every e-commerce consignment carries a European handling fee of EUR 2 per product type, including consignments above that value. Both apply whether the goods land in Rotterdam or Hamburg. What still separates the two markets is timing: whether import VAT is paid at the border or parked until the VAT return, and for foreign sellers without local registration, that timing question now decides real money on every shipment. The new fee landscape The Netherlands Chamber of Commerce, in a guide edited on 3 November 2026, sets out the current stack for a shipment from China: customs duty on the product’s TARIC classification, plus import VAT at 21 percent on the customs value plus duty, plus the new handling charge. For direct-to-consumer parcels up to EUR 150, a flat EUR 3 per product category in duty applies, common in dropshipping models, and since 1 November the EUR 2 European handling fee rides on all e-commerce consignments regardless of value. The duty exemption itself is gone since 1 July 2026, so low-value parcels that cleared duty-free for years now carry both the flat duty and the fee. None of that changes the VAT arithmetic; it changes its urgency. Import VAT is recoverable as input tax for businesses entitled to deduct, which turns it into a cash-flow question. The country where the goods clear decides who gets the cash-flow benefit and through which paperwork. The Dutch permit, condition by condition The Netherlands answers the timing question with the Article 23 permit, and the tax administration’s official page is precise about it. With the permit, import VAT is not paid at customs; it is declared in the VAT return and, where the business can deduct input tax, deducted in the same return, netting to zero. The conditions are three: the applicant must be an entrepreneur established in the Netherlands, must import regularly from countries outside the EU, and must keep a separate administration that clearly shows the import VAT owed per import. The permit also restructures filing. A holder may not file an annual return; a business currently filing annually receives a letter requiring quarterly filing thereafter. Businesses using the small entrepreneurs scheme cannot take the permit at all. Some goods must always have their import VAT declared in the return regardless, as listed in Annex A of the 1968 VAT Implementing Decision. Applications go in writing, and the tax administration commits to a decision within eight weeks. When the seller is not Dutch Most cross-border sellers importing into the Netherlands are not established there, and the official guidance gives them two routes. A general fiscal representative, one that acts on behalf of the seller across its Dutch VAT affairs, can apply for the Article 23 permit itself, with the permit attached to the seller’s Dutch VAT number. Alternatively, a seller represented by a limited fiscal representative, typically the customs agent or fulfilment house that is the importer of record, may be able to use that representative’s existing Article 23 permit. The second route is faster but changes the legal position: the importer on the customs declaration is the representative, not the seller, and the seller should confirm who bears the import VAT in that structure before relying on it. Evidence requirements run through both routes. The application asks for the VAT identification number, the business name under which goods are imported, the type and value of goods, the non-EU countries of origin, the frequency of imports per year, and documents proving regular imports such as order confirmations, purchase invoices or import documents. A seller importing twice a year will struggle to show regularity; a seller with weekly inbound flows will not. How Germany answers the same question Germany reaches a similar result for domestically established businesses through a different mechanism. Import VAT, charged at 19 percent standard or 7 percent reduced, is due on customs value plus duty plus freight to the first EU destination, with payment deferred to the 26th of the second month after import under the VAT Act. Since July 2021, postponed accounting under Section 21a lets import VAT be declared in the VAT return rather than paid at the border, which is functionally what the Dutch permit achieves. The routes diverge for the non-established seller. German postponed accounting presupposes a German VAT registration, and German fiscal representation under Section 22a exists only for businesses making exclusively VAT-exempt supplies, a narrow category that excludes ordinary goods importers. A foreign company without German registration therefore pays import VAT at the border and recovers it afterwards, either through a German VAT registration with its own reporting obligations or through a refund procedure that, for non-EU businesses, requires a reciprocity agreement. There is no fiscal representative route that parks the payment the way a Dutch general representative can. The arithmetic of waiting The Dutch chamber’s worked example sizes what the timing is worth. One pallet of goods purchased at EUR 5,000 with EUR 1,000 of transport and insurance gives a customs value of EUR 6,000. Duty at 12 percent is EUR 720. Import VAT at 21 percent on the combined base is EUR 1,411.20. With the Article 23 permit, that EUR 1,411.20 stays in the business from customs release until the quarterly return settles and deducts it; without the permit it leaves at the border and comes back through the same return. The same customs value cleared into Germany carries EUR 1,140 of import VAT at 19 percent, with the equivalent waiting cost attached only if the importer qualifies for postponed accounting. The comparison is about timing, not tax. In both systems a fully deductible importer nets to zero; the difference is who finances the tax between release and recovery, for how long, and through whose licence. On a container with tens of thousands of euros of VAT, weeks of financing cost and the interest rate attached to them move straight into landed cost. One structural alternative exists on both sides of the border, and it works differently from either permit system. Customs suspensive procedures, bonded warehousing, inward processing and transit, suspend import VAT entirely while goods remain under customs control; the charge crystallises only on release into free circulation, and goods re-exported straight from the procedure never incur import VAT at all. Authorisation is required per procedure and the goods stay under customs supervision throughout. For an importer that can hold stock in a bonded facility and release into free circulation on demand, the VAT question moves from the customs declaration to the warehouse release note, which is why some EU distribution models are built around warehousing rather than around deferment permits. The ancillary costs deserve a line in the same spreadsheet. The Dutch chamber’s total-cost example adds customs clearance fees around EUR 125 and terminal handling and local charges around EUR 175 to a EUR 5,000 shipment, figures that vary by order and supplier but belong in the model next to the VAT timing question. Which lane fits which operator Established operators with a German entity get postponed accounting automatically and need no permit equivalent; their Dutch counterparties file an Article 23 application and switch to quarterly filing. Non-EU sellers serving the Netherlands through fulfilment or FBA stock route the permit through a general fiscal representative, or use the limited representative’s permit and accept the importer-of-record consequences. Sellers distributing into both markets from EU-based stock need to remember that stock placement itself triggers registration: the Netherlands became a mandatory storage and sales market in Amazon’s Pan-EU programme in 2026, and every storage country requires a local VAT registration from the first stored unit, with programme enrolment dates of 3 September 2026 and 26 February 2027 governing access. One check closes the loop for anyone repricing after November. The EUR 2 handling fee and the flat EUR 3 duty hit consumer-direct parcels; they do not change B2B import calculations on commercial shipments. Mixing the two fee regimes into one landed-cost model is the most common spreadsheet error the new landscape invites. Sources KVK (Netherlands Chamber of Commerce), “How to calculate import duties when importing from China,” edited 2026-11-03 (fee changes, worked example, Article 23 overview). Belastingdienst, “Vergunning artikel 23 aanvragen” (Article 23 permit: conditions, annual-filing ban, fiscal representative routes, 8-week decision), official guidance. Nederlandse Douane, e-commerce handling fee (afhandelingsvergoeding) page, EUR 2 per product type from 2026-11-01, via KVK. Commenda, “Guide to Import VAT in Germany for Foreign Companies” (19%/7% rates, tax base, deferred payment date, EUR 150 rule abolished 2026-07-01), 2026. Eurofiscalis, “Your FBA stock registers you for VAT, not your Amazon.nl listing” (Netherlands mandatory Pan-EU market 2026, enrolment dates). Eurofiscalis, “VAT in Germany: key VAT information” (Section 22a fiscal representation limited to exclusively exempt supplies; refund routes). This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
UAE Data Localisation: Which Rules Actually Bind in November 2026 SeaPRwire

UAE Data Localisation: Which Rules Actually Bind in November 2026

The fine most compliance vendors quote for UAE data protection breaches, scaling from AED 50,000 to AED 5,000,000, cannot be traced to the primary text of the law it is supposed to come from. A research note published on 4 November 2026 by Dubai security firm CODE3 went looking for the source and could not find it, and a Lexis Middle East practice note current as of November 2026 confirms the structural reason: the Executive Regulations and the Cabinet decision on administrative penalties under the federal Personal Data Protection Law have still not been published. What binds system architects in the UAE right now is therefore not the federal privacy law’s penalty regime but a set of sector rules, and the difference determines where production data, backups and access logs may sit. What the law says, and what it defers Federal Decree-Law No. 45 of 2021 is real and in force since 2 January 2022. Its obligations are genuine: consent requirements, data subject rights, breach notification to the regulator, and cross-border transfer rules in Articles 22 and 23, which permit transfers to countries with adequate protection approved by the Data Office, or otherwise under contractual safeguards or the data subject’s explicit consent. The official text on the UAE legislation portal also shows what the law deliberately left open. Article 26 assigns administrative penalties to a separate Cabinet decision. Article 28 required the Cabinet to issue Executive Regulations within six months of promulgation. Article 29 gives controllers and processors six months from the issue of those regulations to comply, extendable once. Neither document has appeared on the legislation portal. The law currently sets duties without a published fine schedule, which means the enforcement countdown has not started. Article 29’s clock runs from the day the regulations land, not from the day a company starts preparing. The scope exclusions matter as much as the obligations. Article 2 excludes government data and government entities, personal data held by security and judicial authorities, health data covered by its own legislation, personal banking and credit data covered by their own legislation, and companies in free zones with their own data protection rules, which in practice means the Dubai International Financial Centre and Abu Dhabi Global Market. Each exclusion points to a different binding rule. One quieter provision shows how deep the dependency on the missing regulations runs. Article 3 lets the regulator exempt establishments that do not process large volumes of personal data from part or all of the requirements, but only according to standards and controls set by the Executive Regulations. Even the small-processor carve-out, the provision that would let lean startups slim down their compliance load, is parked behind the same unpublished document. The number nobody can source The compliance market has not waited for the official schedule. The CODE3 note tracked the most-quoted figure, fines starting near AED 50,000 and reaching AED 5,000,000, across vendor sites, LinkedIn posts and client proposals, and found no trace of it in the Decree-Law itself. Other sources cite a ceiling as high as AED 20,000,000. A few claim a January 2027 hard compliance deadline that nobody has matched to an official gazette notice. The honest reading, as the note puts it, is that nobody outside the UAE Cabinet knows the final numbers, because they have not been published. None of this makes the exposure theoretical. Contractual commitments, customer audits and insurers already price PDPL-aligned handling into UAE deals, and breach costs, notification, recovery, lost accounts, arrive on their own schedule. The unpublished penalty schedule changes the regulator’s leverage, not the market’s. Where the regulator sits Enforcement machinery is also in transition. In June 2026 the UAE announced the Federal Authority for Artificial Intelligence and Data, which absorbs the UAE Data Office along with the information-government functions of the telecommunications regulator, consolidating them under a single Cabinet-reporting structure effective 14 June 2026. The CODE3 note adds that the dedicated Data Office is not fully operational. There is also no official adequacy list yet, so Article 22’s clean route for transfers to adequate countries currently has no published map, and Article 23’s contractual-safeguards route does the practical work. The rules that bind today Health data is the clearest constraint. Federal Law No. 2 of 2019 on ICT in health fields bars storing, processing or transferring health data outside the UAE except in cases the health authority sets, and Ministerial Decision No. 51 of 2021 lists ten exception types. For any product touching patient information, this sector rule overrides the federal privacy analysis entirely, and its exceptions are administrative, not automatic. Banking data follows the same pattern from the financial regulator. Central bank rules keep the master system of record in the UAE, according to compliance-mapping analyses of the Gulf regimes, which treat the banking and health rules as the binding constraints and the federal law’s transfer articles as the general framework around them. The free zones run parallel regimes with real boundaries. DIFC companies answer to Data Protection Law No. 5 of 2020 and ADGM companies to its Data Protection Regulations 2021, and both regimes treat mainland UAE as a separate jurisdiction for transfer purposes. A platform serving users across a free zone and the mainland simultaneously needs a lawful transfer route in both directions, because two regulators with different standards can each see the same data flow. Architecture constraints in practice Mapped onto deployment decisions, the picture is narrower than “keep all data in country” and stricter than the federal law alone suggests. Production placement: the federal law does not mandate in-country hosting for general personal data, so a UAE cloud region is a risk-management choice, but health and banking data carry their own in-country requirements that no cloud contract language cures. Backups and replicas: Gulf frameworks reach copies, not just primaries; Kuwait’s framework, for comparison, bars Tier 3 and Tier 4 data from storage outside the country temporarily or permanently, explicitly including backups, replicas and exported logs, and UAE health-data analyses make the same point about copies. Access and logging: giving offshore support teams production access is a transfer decision under Articles 22 and 23 regardless of where the servers sit, and vendor practice in the market increasingly limits production access to named individuals with audit logs. That last control is engineering hygiene rather than statute, and it should be labeled as such in any compliance document. Saudi Arabia, for teams comparing Gulf markets, binds harder at the framework level: its cloud computing rules require certain data levels to be hosted in-Kingdom by licensed providers. Qatar’s central bank requires approval before cloud arrangements for licensees. None of the six Gulf states link their regimes to each other, so a regional architecture needs a per-country register, not one policy. The clock that has not started The practical sequencing for teams building or re-architecting UAE systems follows from the gap between duties and enforcement. Build now to the sector rules that already bind, health, banking and free-zone regimes, because those do not wait for the federal schedule. Build the federal law’s obligations into contracts and data maps now, because Article 29’s six-month window starts when the Executive Regulations appear, and the regulations could be issued at any point. Treat every fine figure in vendor material as a placeholder until a gazette notice says otherwise, and price compliance on the cost of an actual breach rather than on a penalty that has no legal existence yet. When the regulations land, the first published penalty schedule will also settle which of the quoted ceilings was closest. Until then, the honest architecture constraint in the UAE is the sector map above, and the honest deadline is the one that has not started counting. Sources CODE3 Technologies (Deen Mohamed), “Everyone Quotes the Same UAE Data Protection Fine. The Law That Would Confirm It Still Doesn’t Exist,” 2026-11-04. UAE Legislation Portal, Federal Decree by Law No. (45) of 2021 Concerning the Protection of Personal Data, official English text (Articles 2, 22, 23, 26, 28, 29). Lexis Middle East, “Managing Personal Data Transfers from the UAE,” Practice Note, as of November 2026. Data Protection Monitor, “United Arab Emirates Data Protection & Privacy Regulation” (Federal Authority for Artificial Intelligence and Data, effective 2026-06-14). Complyan, “Data Residency Requirements Across GCC Nations: A Compliance Mapping Guide” (Federal Law No. 2 of 2019, Ministerial Decision No. 51 of 2021, CBUAE rule, GCC comparison), 2026-10. UAE Government Portal, “Data protection laws” (PDPL overview, DIFC Law No. 5 of 2020, Federal Law No. 2 of 2019). This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Indonesia’s QRIS Zero-Fee Band Now Covers Every Merchant Category SeaPRwire

Indonesia’s QRIS Zero-Fee Band Now Covers Every Merchant Category

Bank Indonesia cut the merchant discount rate on QRIS payments to zero for every merchant category on transactions up to Rp100,000, effective 1 October 2026, and used a 4 November press conference to reaffirm the policy alongside two further moves: stronger implementation of the domestic credit card scheme and new cross-border QRIS corridors under exploration with Timor-Leste and Hong Kong. The change matters for anyone pricing Indonesian checkout flows, because the zero band previously covered only micro merchants, and it now applies to ordinary retailers, restaurants and service businesses across the roughly 46 million merchants registered on the national QR standard. The schedule as it now stands The revised schedule is a staircase by ticket size and merchant category. Ordinary shops pay nothing on transactions up to Rp100,000. Micro merchants keep their wider zero band, which runs to Rp500,000. Above those thresholds, category rates apply to the whole ticket, not just the excess: 0.7 percent for regular merchants and 0.3 percent for qualifying categories, with designated public-service categories still at zero. Central bank rules put the fee on the merchant and prohibit passing it to the shopper, so published prices must already include the cost. Two worked examples show where the edges sit. A micro merchant taking Rp500,001 pays Rp1,500 on that transaction; the same shop taking Rp500,000 pays nothing. The sticker on the counter reads zero in both cases, but the ledger does not. For a regular merchant, a Rp600,000 ticket carries Rp4,200 of merchant fee at 0.7 percent, which lands directly in the margin calculation of any business running thin-ticket, high-volume sales through QR codes. The cliff above the band Category rates interact with merchant classification, and that is where the avoidable cost sits. A business registered as micro pays Rp1,800 on a Rp600,000 ticket; the same ticket costs Rp4,200 once the business is classified as small, according to wallet provider GoPay’s own merchant guidance, which also states that reclassification from micro to small happens automatically once transactions reach Rp300 million in twelve months. A shop that crosses that line without repricing its payment mix absorbs a 0.3 to 0.4 point swing on above-band tickets without any notice from the scheme. The average ticket makes the band look generous and the distribution makes it look thin. The national average QRIS ticket in the first half of 2026 was Rp89,243, comfortably inside the zero band, so by transaction count most payments now cost the merchant nothing. Inbound tourists break the pattern: foreign visitors in Bali averaged roughly Rp294,000 per transaction in January 2025, three times the national average and deep inside the charged tier. Count-weighted and value-weighted views of the same fee schedule point in opposite directions, and both are true. Settlement timing is the second cost The fee is not the only deduction between a customer’s scan and the merchant’s bank balance. Indonesia’s default QRIS settlement runs to the next working day, Monday to Friday only, with nothing moving on weekends or public holidays. A worked example published on the national QRIS portal shows Rp10 million accumulated on a Friday arriving on Monday as Rp9,927,000, after a 0.7 percent merchant fee and a Rp3,000 payout charge. Payout fees rise to Rp5,900 where settlement routes outside the four large banks. A weekend-heavy business, which describes most food and beverage merchants, is carrying an interest-free float every week, and the size of that float scales with Friday sales. Merchants checking their provider dashboards should reconcile two things against the new schedule: that the deduction shown per transaction matches their category’s rate below and above the Rp100,000 line, and that no surcharge has been added at checkout, which the pass-through prohibition makes a compliance problem as well as a pricing one. The cross-border file The 4 November announcement also kept the export side of the scheme moving. In the eight months to August, inbound cross-border QRIS transactions reached 17.8 million with a value of Rp6.2 trillion, about USD 345.7 million, according to figures relayed by the national news agency ANTARA in late September. The average cross-border ticket works out near Rp348,000, roughly four times the domestic average, which means nearly all tourist-facing QRIS value sits in the tier where merchant fees still apply. Corridor additions are arriving in sequence. Korean bank apps connected to QRIS in April 2026, covering more than 32 million QRIS merchants through the Korea Financial Telecommunications and Clearings Institute link, and the Korean prepaid wallet Shinhan SOL Pay went live on 29 October 2026 with no international brand fee and a waived QR transaction fee until 30 June 2027, according to Korean media reports compiled by a regional payments guide. The Korean connection runs wallet-to-merchant without a double currency conversion, which is the same design the scheme’s earliest corridors used. Southeast Asian corridors under the bilateral QR model have operated with Thailand and Malaysia for years. The two candidates named on 4 November, Timor-Leste and Hong Kong, sit at the exploration stage, and the central bank has not published timelines or fee terms for either. One cost line in the corridor business is disclosed worse than the rest. Singapore banks helping customers pay Thai merchants by QR state, in help pages a level below their product pages, that a 2 percent conversion mark-up applies on top of the exchange rate. The merchant fee is zero at both ends; the spread sits with the payer’s bank and reaches the payer only on the confirmation screen. Why the central bank is giving up the fee The zero band costs the scheme revenue, and the trade the central bank is making is visible in its own statistics. QRIS reached 69.3 million users against roughly 46 million registered merchants, and micro, small and medium enterprises account for about 69 percent of those merchants. BI has signalled it wants QRIS transaction histories used as a reference for small-business credit scoring. A merchant paying nothing into the system still generates a payment record the ecosystem can underwrite. The remaining revenue lines, category rates above the band, payout charges and the float on weekend settlement, stay with the payment industry, so the subsidy to the smallest merchants is paid for by the larger ones. The announcement came inside a wider policy update. The rupiah, which closed September near 17,830 per dollar, weakened to 18,145 by 2 November under global uncertainty, and the central bank paired its payments agenda with reassurance that foreign reserves, at USD 146.3 billion at the end of September, cover 5.3 months of imports. Digital payment expansion is the growth lever the bank keeps pulling while the currency side is under pressure. What payment teams should re-check Three checks follow from the schedule change. First, margin models built on the old assumption that zero MDR applies only to micro merchants overstate cost for small-ticket retail and understate it for merchants that reclassify mid-year; the Rp300 million twelve-month line decides which side a merchant lands on. Second, settlement-calendar pricing, the gap between Friday volume and Monday arrival net of fees, belongs in cash-flow forecasts for weekend-weighted businesses, not just fee-per-transaction models. Third, cross-border corridors carry their real price in conversion spreads and payer-side bank charges rather than merchant fees, so corridor comparisons should start from the payer’s confirmation screen, not the scheme’s published rate card. The band itself is unlikely to shrink. Every signal from the 4 November briefing points the other way: wider zero-fee coverage, more corridors, and a credit-data play that depends on small merchants staying inside the system. The practical question for payment teams in the region is no longer whether small QRIS tickets are free, but where the cost moved to. Sources Medcom.id (Harianty), “Bank Indonesia expands QRIS cross-border cooperation,” report of the 4 November 2026 central bank press conference. World Payments Monitor, “Indonesia Payments & Fintech Regulation,” regulatory update dated 2026-11-03 (QRIS MDR broadening effective 2026-10-01). SEA Weekly, “How ASEAN payment costs shape merchant cash alongside factory orders and household bills,” 2026-11-07 (fee staircase, settlement example, ANTARA figures of 2026-09-26). Berita Daring, “Indonesia’s QRIS Boom: One Bank Figure Says 13.66 Billion Payments, a Trade Brief Says 2.5 Billion,” fee schedule audit (pre- and post-October 2026 MDR categories, H1 2026 average ticket). AccessiaPass, “Paying QRIS in Bali With a Korean Bank App: Fees and How-To,” Korean corridor details checked 2026-11-03. This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Three Clearance Paths for Small Parcels After the Freeze SeaPRwire

Three Clearance Paths for Small Parcels After the Freeze

The USD 800 duty-free threshold for parcels entering the United States is gone in practice now and gone in law from 1 July 2027. Customs and Border Protection published interim final rules on 24 June 2026 that made the suspension of the de minimis exemption indefinite, for both postal and non-postal shipments, removing the expectation that the exemption would simply lapse back into effect. A October 2026 rule then narrowed who can still use the simplified mail entry process. What remains is a fee structure that punishes parcel-by-parcel filing: a USD 150 shipment entered alone now carries at least USD 34.58 in merchandise processing fees, the same floor it would pay if it were a container load. How the exemption ended, in sequence Four dates tell the story. Executive Order 14256 of 2 May 2025 suspended duty-free de minimis treatment for goods of Chinese and Hong Kong origin. Executive Order 14324 of 29 August 2025 extended the suspension to every country of origin, which is the point where the exemption stopped functioning as a commercial strategy for anyone. The One Big Beautiful Bill Act, signed 4 July 2025, repealed the commercial de minimis provision in statute, effective 1 July 2027, so the administrative suspension becomes a legal repeal on that date. Finally, the 24 June 2026 interim final rules wrote the suspension into CBP regulations without an end date. A court ruling along the way changed less than expected. The Supreme Court’s 20 February 2026 decision ended the IEEPA tariff program, and Executive Order 14388 followed, but the de minimis suspension was expressly continued. Teams that planned around a court case restoring duty-free parcels lost that assumption in February. What filing looks like now Every commercial shipment valued at USD 800 or less that once qualified for Section 321 treatment now moves through formal or informal entry. The suspension reaches every transport mode, including the international postal network, and it took effect on the date of publication in the Federal Register for both non-postal and postal shipments. Informal entry is generally available for shipments up to USD 2,500, subject to eligibility. Formal entry is required above that line and for specific merchandise classes, including goods subject to antidumping or countervailing duties. Mail shipments have their own track. The new mail informal entry process, effective 24 July 2026, covers mailed goods up to USD 2,500 that qualify for informal entry. Filing is manual: a spreadsheet with the filer code, bond number, duty owed, merchandise description, carrier, country of origin, the 10-digit tariff classification, the S-10 postal tracking barcode, and arrival details, submitted to CBP by email no later than the seventh day of the month following arrival. Entry can only be made by the owner or purchaser of the goods, or a licensed customs broker they designate. The October rule trimmed that track. Effective 22 October 2026, four categories are excluded from mail informal entry eligibility: merchandise claiming duty-free treatment under Chapter 98 of the tariff schedule, merchandise subject to Chapter 98 or Chapter 99 duties, merchandise claiming free trade agreement treatment, and goods subject to partner government agency requirements. Those shipments move through other entry types. An extended compliance date of 20 January 2027 gives filers a runway for the formal entry requirement on certain mail shipments, including those carrying Chapter 99 duties. Entry Type 86, the electronic filing built specifically for Section 321 volumes, no longer exists. Importers whose process documentation says “we file Type 86” need to re-map that workflow to the entry types that remain. The arithmetic that decides the model The duty is only part of the cost. The merchandise processing fee on a formal entry is 0.3464 percent of customs value, with a floor of USD 34.58 for fiscal year 2027, re-indexed each October. That floor is what breaks the one-parcel-one-entry model. One hundred separate USD 150 orders, each entered individually, hit the fee floor one hundred times: about USD 3,458 in processing fees on USD 15,000 of goods, before any duty. The same USD 15,000 consolidated into a single entry pays the percentage instead, about USD 52. The difference is roughly sixty-fold, decided entirely by how many entries the goods generate. Ocean freight adds the harbor maintenance fee, 0.125 percent of customs value with no cap. This is why consolidation, not duty rates, is now the first lever for small parcels. The duty depends on tariff classification and any additional programs stacked on top; the fee structure depends only on how many entries are filed. Path 1: consolidate inbound, fulfil domestically The first path brings inventory across the border as one bulk entry and holds it in the United States, fulfilling orders domestically from local stock. Duty and fees are paid once, on one entry, and the border cost converts into a storage cost. Delivery times shorten, which is often the reason brands stay on this path after trying it for the fee savings. The trade-offs are forecast risk, because the goods are committed to the US market before demand is known, and inventory carrying costs that did not exist when each order shipped on demand from overseas. Path 2: bonded warehousing for cash timing The second path addresses timing rather than total cost. Goods sit in a bonded warehouse under customs control, and duty is deferred until each portion is withdrawn for consumption. For businesses with uncertain sell-through, this limits duty exposure to what actually moves. The mechanics cost money: warehouse handling fees, withdrawal filings per release. The model suits goods with volatile demand or seasonal spikes, where paying full duty up front on a bulk entry would strand cash in slow-moving stock. Path 3: keep the parcel model where it still fits Parcel-by-parcel entries still work for some cases. High-value small orders, demand testing in a new market without US stock, and product lines where the per-parcel duty is trivial relative to the product price can justify the per-entry fees and the per-parcel clearance charges carriers and brokers levy. The operational risk in this path is repetition: a classification or valuation error replicated across thousands of entries is a far larger exposure than the same error in one consolidated filing, and the return logistics run cross-border in both directions. Two carve-outs survive untouched. Bona fide gifts and personal or household articles accompanying travellers keep their separate exemptions under 19 U.S.C. 1321, unchanged by any of the 2025 or 2026 actions. Neither helps a business selling goods, and neither covers commercial returns, so the carve-outs matter for personal shipments and traveller luggage rather than any fulfilment model. What to verify before switching paths Three checks come before any model change. The first is tariff classification: the duty rate and every stacked program attach to the 10-digit classification, so a wrong code poisons the landed-cost math for all three paths. The second is program stacking, since some origin countries carry additional duty layers that apply per shipment regardless of entry type. The third is the broker’s fee schedule for informal entries, because the per-entry service charge varies widely and, on low-value shipments, can exceed the fee floor itself. Importers running the numbers for fiscal 2027 should use the USD 34.58 floor, not the prior year’s figure, since the re-index took effect in October. None of the three paths restores the old economics. What they change is how much of the cost arrives as fees, when the duty is paid, and how much inventory risk the importer carries. The repeal in law on 1 July 2027 removes any remaining plan built on waiting out the suspension. Sources U.S. Customs and Border Protection, “E-Commerce Frequently Asked Questions” (de minimis suspension, entry types, mail informal entry, exclusions effective 2026-10-22, extended compliance date 2027-01-20). Public Law 119-21 (One Big Beautiful Bill Act), Section 70531, statutory repeal of commercial de minimis effective 2027-07-01. Finetex Global, “De Minimis Reform: What It Means for Small Apparel Importers,” dates and rules checked on US government sources on 2026-11-11. Long Road Warehouse, “Is Section 321 Still in Effect? De Minimis in 2026” (MPF floor, consolidation arithmetic). Executive Orders 14256 (2025-05-02) and 14324 (2025-08-29); Executive Order 14388 (2026-02-20, suspension continued after IEEPA ruling). This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Riyadh and Jeddah Split the Saudi Trade Show Calendar SeaPRwire

Riyadh and Jeddah Split the Saudi Trade Show Calendar

The 20th Jeddah International Motor Show closed on 7 November after four days at the Jeddah International Exhibition and Convention Center. On 23-25 November the same city hosts the Saudi Franchise Expo and the Jeddah edition of the Foodex Saudi food and beverage show in the same week. Riyadh’s Foodex edition opens first, 16-18 November, and the franchise expo’s Riyadh edition follows on 26-28 January 2027 at The Arena. Saudi Arabia’s exhibition calendar has settled into a two-city rhythm, and the November wave shows how the split now works in practice. The calendar as it reads this month Four events anchor the season. The Jeddah motor show ran 4-7 November at the Jeddah International Exhibition and Convention Center, marking its twentieth edition with internal-combustion, hybrid, electric and extended-range vehicles on the same floor, test drives on open roads, and regional debuts of new models. Foodex Saudi, the food and beverage show organised by Reed Sunaidi Exhibitions, part of RX, runs its Riyadh edition 16-18 November and its Jeddah edition 23-25 November, one week later. The Saudi Franchise Expo occupies the same Jeddah dates, 23-25 November, at the Jeddah Center for Exhibitions and Events, with evening opening hours from 4:00 to 11:00 PM. Its Riyadh edition is scheduled for 26-28 January 2027, also at The Arena. The pattern is visible in the sequencing. Two organisers are running paired editions across the two cities within a single season, one starting in Jeddah and moving to Riyadh, the other starting in Riyadh and following a week later in Jeddah. Neither organiser is running both cities simultaneously. One organiser group, two cities, staggered editions The franchise expo and Foodex Saudi sit on the same organiser family: Sunaidi Expo organises the franchise show directly, and Reed Sunaidi Exhibitions, the joint venture with RX, runs Foodex. For the franchise expo, the official site lists the Jeddah edition first with 179 international, regional and local brands across 7,000 square metres, and the Riyadh edition three months later in a different venue. For Foodex, the Riyadh edition comes first and Jeddah follows a week later. The same production machinery serves both markets, with the edition order flipped between the two shows. The staggered structure has a practical consequence for exhibitors. A brand exhibiting in both editions of either show builds one stand production and ships it between cities, but needs two teams, two build-up windows and two sets of local logistics. The three-month gap between the franchise expo’s Jeddah and Riyadh editions is wide enough to rebuild or retheme the stand; the one-week gap between Foodex editions is not, so the Riyadh build comes down and goes back up almost immediately. Who walks the floor in each city The buyer structures differ by show type as much as by city. The franchise expo’s own figures, published on its site, report 465 or more agreements signed to date across editions, a 68-to-32 split between trade and general visitors, and satisfaction figures above 97 percent. The same page cites a Saudi franchise market valued at USD 15 billion with more than 15,000 franchise branches and 27 percent annual growth in the non-oil sector, figures attributed to the Ministry of Commerce and Investment and the Riyadh Chamber. The visitor profile list runs from food and beverage through retail, education, IT and business services, which is the audience shape of an investment-seeking show rather than a pure sourcing show. The franchise expo’s on-site programme explains part of that audience shape. The official site lists a business matchmaking service that pre-schedules meetings pairing brands with vetted investors, alongside workshops and panel discussions on franchising, financing and operations led by practitioners. The 465-plus agreements figure is presented as a cumulative result of that matchmaking machinery across editions, which positions the show closer to a deal room than a catalogue floor. Exhibitors attending for lead generation rather than brand exposure compete for meeting slots as much as for floor position, and the matchmaking allocation is an organiser decision that does not automatically follow stand size. Foodex Saudi’s trade listings report the last Riyadh edition at 12,800 square metres with 229 exhibitors and 11,500 visitors, drawn from commodity chains spanning Europe, South America, Africa and Asia. Entry runs on real-name online pre-registration verified against passports, with badge collection on site, per the trade listings’ visitor-process notes. The motor show, by contrast, is the consumer-heavy event of the three: its programme of public test drives, virtual reality experiences and a hackathon is built to draw end buyers as well as trade visitors, and its vehicle mix, covering internal-combustion, hybrid, battery-electric and extended-range powertrains on one floor, is framed around a regional market where alternative-energy vehicles are gaining share. The Jeddah clustering on 23-25 November puts a food sourcing show and a franchise investment show in the same city in the same week. For regional buyers flying in for one, the second show is a same-trip addition, and for local visitors the evening hours at the franchise expo make same-day attendance at both feasible. Riyadh’s editions sit apart, which spreads the season’s demand across two venues and two months. What the split means for exhibiting costs Venue and format choices feed directly into budgets. The franchise expo’s 7,000-square-metre footprint with 179 brands implies a larger average share of floor per exhibitor than a 500-brand food show of similar size, and its 4:00-11:00 PM schedule shifts staffing into evening shifts, which changes crewing quotes in a market where evening event labour prices differently from daytime. Build-up for Foodex closed on 15 November, the day before opening, per the show’s published timeline, leaving no slack between build and open. The same listing’s stand production timeline works backwards from opening day: builders should be briefed around 16 weeks before opening, which for the Riyadh edition meant late July 2026, a deadline the listing marks as already passed for late entrants. Lead times compound across the double-edition play. A brand booking the January 2027 Riyadh franchise edition faces a build window that overlaps the Gulf’s peak exhibition season, when stand contractors, freight forwarders and hotels are simultaneously serving the winter calendar. Exhibitors who treat the second edition as a repeat of the first, with the same contractor, the same drawings and the same local crew, typically negotiate the package as one engagement; exhibitors who book the two editions separately pay two mobilisation charges for what is materially one production. The two-venue structure also means exhibitors quote against different venue service packages in each city. Riyadh’s Arena and Jeddah’s exhibition centers have different in-house catering rules, which matters for a food show where sampling drives stand traffic. Exhibitors running the double-edition play typically request the same stand position pattern in both cities to reuse floor plans. What to confirm before committing Two details need organiser confirmation rather than listing trust. The first is venue naming for Foodex’s Riyadh edition: trade listings disagree, with some placing the show at The Arena Riyadh and others at the Riyadh International Convention and Exhibition Center on King Abdullah Road. The discrepancy matters for freight routing and hotel bookings, and the organiser’s own exhibitor manual is the binding reference. The second is the calendar itself: the January 2027 franchise expo dates in Riyadh are published on the official site, but the food show’s 2027 editions and the motor show’s next edition were not yet listed at the time of writing, so exhibitors planning a two-city season should hold dates loosely until the organiser confirms. Saudi Arabia’s exhibition market has grown into a two-circuit structure because the demand supports it: a capital-city market with government-adjacent and investment-seeking buyers, and a Red Sea port city whose shows pull regional trade visitors. The November calendar is the first season where the split shows up as paired editions from the same organiser group in the same month, and the January franchise dates confirm it was a plan rather than a scheduling accident. Sources Saudi Franchise Expo, official organiser website (Jeddah edition 2026-11-23/25 at Jeddah Center for Exhibitions and Events; Riyadh edition 2027-01-26/28 at The Arena; 179 brands, 7,000 sqm, 465+ agreements, 68/32 visitor split; market figures attributed to Ministry of Commerce and Investment and Riyadh Chamber). StandsZone, “Foodex Saudi 2026” listing (Riyadh edition 2026-11-16/18, organiser Reed Sunaidi Exhibitions, part of RX, build-up timeline). SaudiCon, “2026 Jeddah International Motor Show opens 20th edition,” reporting the Saudi Auto platform (2026-11-04/07, Jeddah International Exhibition and Convention Center). Jufair exhibition listing, Foodex Saudi (last Riyadh edition 12,800 sqm, 229 exhibitors, 11,500 visitors; venue naming discrepancy noted). Qiyetang exhibition listing, Foodex Saudi two-city dates (Riyadh 2026-11-16/18, Jeddah 2026-11-23/25). This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
EU Ad Repository Guidelines Move: What Sellers Should Track SeaPRwire

EU Ad Repository Guidelines Move: What Sellers Should Track

The European Commission opened a call for evidence on 4 November 2026 on how the advertising repositories of very large online platforms should be designed. Responses close on 2 December, a targeted consultation on a draft text is planned for 2027, and final guidelines are targeted for the second quarter of 2028. The obligation the guidelines will shape is already live: Article 39 of the Digital Services Act requires very large platforms and search engines to maintain public, searchable archives of the advertisements they display, and the Commission has already fined one operator EUR 45 million for running a repository that fell short. Sellers and advertisers whose campaigns run on those platforms have two dates in view and a metadata audit worth starting now. What Article 39 already demands Each repository entry must record the advertisement’s content, the person or organisation on whose behalf it appeared, who paid for it where that differs, the period during which it ran, whether it was aimed at particular groups and the main targeting criteria used, including exclusions, and the number of users reached, broken down by member state. The archives must be publicly accessible and searchable, accessible through an API, retained for at least twelve months after the advertisement’s last display, and free of personal data about the people who received the ads. Article 26 adds the real-time layer: at the moment an advertisement is shown, it must be identifiable as advertising, with the presenter, the payer and the main targeting parameters disclosed to the viewer. The repository is the retrospective record; the on-ad disclosure is the point-of-view obligation. Platforms are expected to satisfy both, and the public consultation on repository design addresses only the archive side. Why the Commission is writing guidelines now The archive obligation has produced enforcement action. The Commission’s own policy page records a EUR 45 million fine against the provider of X for a non-compliant advertising repository, and describes commitments from other very large platforms to bring their repositories into line, with the Commission stating it will take action where agreement on compliance cannot be reached. Sixteen DSA proceedings have been opened across the supervision programme to date, covering content moderation, minor protection and advertising among other files. The quality problem is the stated motivation. Early repositories vary widely in how well they can be searched, how completely they expose targeting criteria and reach, and whether the ad content itself remains accessible. The Commission frames better archives as enforcement infrastructure: researchers, journalists and national Digital Services Coordinators use the data to detect scams, disinformation campaigns, misleading commercial practices and illegal product promotion, and a common technical standard would give regulators a baseline against which to measure each platform’s archive. The policy page ties the same transparency programme to protecting public health, ensuring consumer protection and safeguarding the integrity of elections, which places commercial advertising archives inside a supervision framework built for wider harms. The consultation documents list three areas the guidelines will address: how easily the data can be searched, how much insight the archives give into targeting and reach, and how accessible the ad content is. Each maps to a complaint researchers have raised about the first two years of archive operation. The Commission is collecting input from researchers, civil society organisations, journalists, the platforms themselves and advertising industry representatives, and reporting around the consultation notes that regulators have already questioned platforms on financial scams and misleading promotions, where a stronger, standardised evidence base would help national Digital Services Coordinators build cases against a common benchmark. The timeline, and what it does and does not change The sequence runs: call for evidence until 2 December 2026, targeted public consultation on a draft text in 2027, final guidelines in the second quarter of 2028. Under Article 39(3), the Commission issues the guidelines after consulting the European Board for Digital Services, researchers and the public. The long runway has a practical consequence: platforms keep operating their archives under their own reading of the rules until the guidelines land. Nothing in the consultation changes the fields each entry must carry, the twelve-month retention, the API requirement or the searchability duty; those are in the regulation text. What the guidelines will settle is the technical standard for each, which affects how machine-readable the archives become and how reproducible third-party research on them is. The move fits a broader advertising-transparency agenda. On 12 October 2026 the EU launched a pilot repository programme for online political advertising, built on the same premise that public, queryable archives let outsiders verify who paid for what. What sellers and advertisers should audit now For advertisers, the archive regime changes the privacy of campaign strategy. Targeting criteria, exclusions and reach figures for every ad on a very large platform sit in a public database that competitors can query. An audit of ad account metadata is the practical first step: confirming that the payer field reflects the real paying entity, that targeting parameters recorded by the platform match the campaign’s intended design, and that nothing in the recorded criteria is commercially sensitive enough to warrant restructuring the campaign’s group definitions. Once the guidelines standardise these fields, discrepancies between what a brand intended and what the archive records become visible to anyone who looks. Marketplace sellers face a separate set of DSA duties that operate alongside the archive regime. Providers of online marketplaces must verify traders’ identity before those traders can sell, and must let consumers identify the trader behind an offer. When a platform becomes aware that a seller offered an illegal product, it must inform affected buyers, identify the seller and offer redress options, and several marketplaces now maintain EU-specific recall pages listing products notified in the previous six months. Sellers whose account documentation lags their corporate reality, after a rename, a restructure or a change of legal entity, generate exactly the mismatches this machinery surfaces, and the verification happens before the next listing, not after. Two preparation items track the consultation directly. The first is participating in it: the Commission has framed the call for evidence as input from the people who use the data, and industry responses arguing for search-by-advertiser and structured targeting fields would shape the 2027 draft. The second is API readiness: brands and agencies that monitor competitor advertising, verify compliance or run research will need to work against whatever machine-readable standard the guidelines set, and building internal tooling against a platform’s current idiosyncratic archive format risks rework after 2028. The grey areas Business confidentiality is the friction point the consultation names without resolving. Detailed targeting records expose how campaigns reach audiences, and the guidelines will have to draw a line between transparency into advertising practices and exposure of commercial strategy. How that line lands is unresolved, and platforms’ current archives already differ in how much targeting detail they publish, so the effective disclosure level a seller experiences today depends on which platform carries the campaign. A second open question is search quality. The regulation requires searchable archives, but the consultation’s framing, better search as one of three priorities, implies the Commission considers current implementations inadequate. Until the guidelines define a floor, archive search that works by advertiser, by product and by date range cannot be assumed, and compliance checks that depend on it inherit that gap. Sellers tracking their own archived ads should test retrieval on each platform directly rather than assuming the archive answers a query it has no obligation, yet, to answer well. Sources Digital Watch Observatory, “European Commission seeks input regarding public ad repositories under DSA,” reporting the call for evidence published 2026-11-04, closing 2026-12-02, final guidelines targeted Q2 2028, and the political-ads pilot repository launched 2026-10-12. European Commission, “The impact of the Digital Services Act on digital platforms” (Article 39 regime, EUR 45 million fine against the provider of X, repository commitments, 16 proceedings). European Commission, “How the Digital Services Act enhances transparency online” (transparency obligations framework). Regulation (EU) 2022/2065 (Digital Services Act), Articles 26 and 39, EUR-Lex. The European Post, “Advertising Repositories Guidance Puts Platform Ads In View” (consultation scope and timetable). This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
EUDR Filings: The Final Stretch to 30 December 2026 SeaPRwire

EUDR Filings: The Final Stretch to 30 December 2026

From 30 December 2026, customs will not release coffee, cocoa, timber, rubber, soya, cattle products or palm oil into free circulation in the European Union until a due diligence statement reference number sits in the declaration. The German enforcement act that fills in the domestic machinery reached the Bundestag on 30 September 2026, and on 12 November lawmakers deleted one of its clauses, stripping the power to delegate federal tasks to private entities. The filing obligations themselves come from the EU regulation and do not move with national drafts. Operators now have roughly six weeks to line up the data, the information system registration and the customs codes those filings ride on. Who files a statement, and who stopped The filing duty belongs to operators: companies that place a covered product on the EU market for the first time, or export it. The December 2025 revision, Regulation (EU) 2025/2650, created a new role downstream. A downstream operator, one that processes or resells goods already placed on the EU market, no longer files its own due diligence statement. Its duties are record-keeping: the names and contact details of suppliers and commercial customers, retained for at least five years, and, for the first buyer after an operator, the reference numbers attached to the goods. Companies in that role that are not small or medium enterprises must also register in the information system, even though they file nothing. The revision also moved the perimeter. If the first operator sits outside the EU, the first EU-based company that makes the product available on the market is treated as an operator and carries the full filing duty. Importers and distributors buying from non-EU suppliers need to check which role their contract puts them in before December, because the two roles diverge sharply in workload. Customs representatives sit outside both: the Commission’s FAQ states they never count as operators, and they declare their principal’s codes and reference numbers. What goes into the filing A due diligence statement carries the operator’s details, EORI number, tariff classification, product description and quantity, the country of production, and the geolocation of every plot of land where the commodity was produced. The regulation asks for latitude and longitude coordinates, with polygon data for plots above four hectares. Filing happens in the EU information system before the product is placed on the market, and the operator hands the resulting reference number to its first customer. There is a shorter route for the smallest producers. Micro and small primary producers established in low-risk countries, which include all EU member states, can file a one-time simplified declaration and receive an identification number that covers their products, instead of a statement per batch. In place of coordinates they may submit the postal address of the land or holding. The due diligence duty itself stays in force for them, including collecting information on origin, but the per-shipment paperwork collapses into a single registration. Risk assessment and risk mitigation only enter the picture when there is a non-negligible risk. For raw materials from low-risk countries, the simplified due diligence of Article 13 applies and those two steps drop out unless there is evidence of a breach. Only once risk is negligible or absent does the operator submit the statement, which is a sequencing point smaller teams sometimes miss: the statement is the last step of a due diligence system, not a form that starts one. The customs mechanics Release for free circulation is the step that triggers everything. Customs warehousing, inward processing, temporary admission and transit do not count as placing on the market, and the re-export of goods that never acquired Union goods status falls outside the regulation entirely. Before release for free circulation, or before export by an operator, the declaration must carry the statement’s reference number or the simplified declaration’s identification number. The tariff code table was updated for this. The Commission published revision 1 of its TARIC working document on 23 September 2026: code C717 now stands for the simplified declaration of micro and small primary producers, and new codes C720, Y188, Y196 cover re-imports and exports by downstream operators, each split between small and non-small companies. Code Y141, used by operators relying on the deferral to 30 June 2027, remains valid until 29 June 2027. Teams configuring ERP or broker filing systems should check their code tables against the September revision, because summer overviews describe some codes differently. One mechanical detail catches re-imports. A company bringing back products previously placed on the EU market states its supplier’s reference number in the declaration; if no number exists, the Commission issues a conventional reference number. And if the information system flags a product for a check, customs suspends release until the status clears. The dates that matter Large and medium-sized operators comply from 30 December 2026. Micro and small operators established before 31 December 2024 get six more months, to 30 June 2027, except in timber: micro and small operators already covered by the EU Timber Regulation comply from 30 December 2026 like everyone else. Companies established after 31 December 2024 get no deferral at all, regardless of size. Timber products already on the market before 30 December 2026 stay under the Timber Regulation until 31 December 2029. Product scope also shifted this autumn. Delegated Regulation (EU) 2026/2102, in force since 18 September 2026, took cattle hides, retreaded and used tyres, soya beans for sowing and certain aircraft and vehicle seats out of scope, and adds soluble coffee, some palm oil derivatives and a handful of other items from 30 December 2027. Any internal product matrix built on the old Annex I needs a re-check against the September text. Enforcement is still being written in Germany The EU regulation applies directly, but each member state supplies the penalties and the inspection machinery, and the German draft shows how much is still in motion. The draft implementing act entered the Bundestag on 30 September 2026 as printed paper 21/8278, naming the Federal Office for Agriculture and Food as the competent authority with the state authorities responsible for primary production and timber harvesting. Its sanction ladder runs from fines up to EUR 100,000 to prison terms of up to five years, and up to ten years for severe, lasting environmental damage; companies above certain turnover thresholds face fines calculated as a percentage of EU-wide turnover, up to 4 percent depending on the breach. The Bundesrat had asked in September for forest-owner relief to be written into the act itself: a postal address with a company number in place of coordinates, and bundled declarations through recognised forestry associations. The federal government answered with a general administrative regulation instead, submitted on 7 October 2026 as printed paper 577/26. Under it, timber that members of recognised forest owners’ associations market through their association is declared by the association as the operator, and the members file nothing of their own. The administrative regulation binds the authorities, not companies, so for importers and traders it changes nothing. On 12 November the Bundestag deleted the draft’s delegation clause, removing the Federal Office’s power to hand tasks to private legal entities. The act is not law until promulgated, and its sanction schedule remains open. The Commission, for its part, has confirmed the core EU text will not be reopened and there will be no third extension of the application date. The May 2026 simplification package was the last structural change. The grey areas worth checking before filing Three points generate most of the avoidable friction. First, size and age interact: a micro or small company set up after 31 December 2024 files on the large-company timetable, so a founding date on paper decides a compliance date. Second, role depends on transaction shape, not job title: the same company can be an operator for one product line and a downstream operator for another, and the first EU company in the chain when the operator is offshore carries the operator’s full duty. Third, the statement number has to reach the customs declaration and the first customer at the same time, which means the data pipeline, plot coordinates, supplier declarations, risk documentation, has to be finished before the first shipment of December, not in parallel with it. The geolocation work is the slowest piece and the one with no shortcut, apart from the narrow postal-address route for the smallest primary producers. Companies in commodity chains with many smallholder plots have the longest lead time, and for them the six remaining weeks are a data deadline, not a legal formality. Sources Polygon One, “EUDR current status: delay, latest news, deadlines and what applies when,” timeline updated through 2026-11-12. EUR-Lex, Regulation (EU) 2025/2650 (targeted revision of Regulation (EU) 2023/1115). EUR-Lex, Delegated Regulation (EU) 2026/2102 (amended Annex I, in force 2026-09-18). European Commission, TARIC working document for Regulation (EU) 2023/1115, revision 1, 2026-09-23 (via Polygon One timeline). EcoSkills Academy, “EUDR: What Companies Need to Do Before the Deadline,” 2026-11. Nicola Bernard, “EU Deforestation Regulation: Application from 30 December 2026,” citing DIHK and EUR-Lex C/2026/3896. KPMG Law, “EUDR: These obligations apply throughout the supply chain, as of 2026.” Bundesrat printed paper 577/26 (general administrative regulation, 2026-10-07) and Bundestag printed paper 21/8278 (implementing act draft, 2026-09-30), via Polygon One legislative timeline. This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
The $2.5 Trillion Question: Who Finances the Exporters Banks Turned Down? SeaPRwire

The $2.5 Trillion Question: Who Finances the Exporters Banks Turned Down?

Trade finance gap 2026: the rejection math, three working detours for SME exporters, and what each one actually costs A shea butter exporter in Ghana holds a confirmed purchase order from a European buyer. The goods are packed, the invoice is cut, and the cash will not arrive for 75 days. The bank that has held the company’s account for six years declines the financing request in an afternoon, citing policy, and offers no appeal process worth the name. Down the road, a competitor with half the revenue gets funded in 48 hours by a platform the owner found through a supplier chat group. Neither exporter changed as a credit. The system around them changed, and the direction it changed in is measurable: the Asian Development Bank’s ninth Global Trade Finance Gap Survey, released January 15, 2026, estimates the global trade finance gap at $2.5 trillion for 2025, unchanged from 2023 and nearly double the 2015 level, with about four in ten SME applications rejected in the 2023-2025 survey window. This article takes that exporter’s dead end seriously as an engineering problem rather than a grievance. The gap will not be legislated away; the banks that rejected 41 percent of SME trade finance requests have reasons rooted in compliance cost and capital rules, and those reasons are not dissolving. What exists instead is a set of detours, each with a real price and a real failure mode. Three of them work often enough to matter: financing anchored to the buyer’s credit instead of the seller’s, guarantees layered by development banks onto local lending, and non-bank invoice financing that prices speed over cost. The difference between a company that survives the rejection and one that shrinks is usually whether its management knows which detour fits which order, and what each one truly costs per year. Why the front door stopped opening The rejection arithmetic needs care, because 2026’s survey contained a genuinely confusing headline. For the first time, the gap survey found SME rejection rates, at 41 percent, nearly level with large and mid-cap corporate rates at 40 percent across the 2023-2025 data window, and ADB itself flags that this requires more research (ADB news release, January 15, 2026). Two readings compete. The optimistic one: banks’ SME strategies, which more than 80 percent of surveyed banks reported having in the January 2026 survey, are finally moving the needle. The pessimistic one, which the survey’s own text leans toward: large-corporate rejection rose to meet the SME rate, meaning the front door did not open for small firms, it narrowed for everyone. Total gap volume, flat at $2.5 trillion in the January 2026 estimate, supports the second reading. A market that improved for SMEs while the aggregate shortfall stayed at a record would look different from every angle, and none of the angles look like that. The mechanics of bank retrenchment are dull and decisive. Trade finance is documentation-heavy, short-tenured and capital-inefficient relative to other lending lines, so when compliance costs rise, banks rebalance toward products with fatter margins per unit of effort. Steven Beck, who leads trade finance at ADB, has framed the consequence plainly: firms redirecting supply chains need more working capital exactly when banks are not stepping in, a missed opportunity for growth. Anti-money-laundering screening costs the same to run on a $60,000 receivable as on a $6 million one, which makes small tickets structurally unattractive to the compliance department before a credit officer ever sees them. The survey found 84 percent of banks using AI for fraud prevention and risk analysis as of January 2026, with 57 percent exploring AI to expand financing capacity, which will eventually lower screening costs. Eventually is doing real work in that sentence; a screening model that clears a small exporter’s invoice is not yet standard equipment, and the rejection rates show it. The result is a structural mismatch rather than a cyclical one. Demand for trade finance is rising, with 80 percent of polled banks expecting growth in the January 2026 poll as companies diversify markets and reconfigure supply chains. Supply is flat, capital-cost-driven and concentrated. The $2.5 trillion shortfall equals about 10 percent of global trade, down fractionally from 10.6 percent, as of the 2025 estimate, the survey’s version of good news that still leaves one in ten traded dollars unfunded. Table 1: The financing gap in one frame Measure Value Period Source detail Global trade finance gap $2.5 trillion 2025 ADB 9th survey, January 2026 Share of global trade ~10 percent 2025 ADB, down from 10.6 percent Gap in 2015 ~$1.5 trillion 2015 ADB survey series SME application rejection rate 41 percent 2023-2025 data ADB 9th survey Large/mid-cap rejection rate 40 percent 2023-2025 data ADB 9th survey ADB TSCFP cumulative support $57 billion 2009-2025 ADB program data ADB trade support, 2025 $5.7 billion 2025 ADB program data Source: ADB , “Demand for Trade Finance to Rise Amid Supply Chain Realignment,” January 15, 2026 One ratio in that table deserves its own sentence. The entire development-bank guarantee apparatus, $57 billion deployed since 2009 through nearly 300 partner banks, supported $5.7 billion of trade in 2025, a figure that is roughly a quarter of one percent of the 2025 annual gap. The detours that follow are real; none of them, scaled by current institutions, closes the gap alone. Exporters planning around them should plan accordingly. Path one: borrow the buyer’s balance sheet The first detour changes whose credit gets priced. In supply chain finance anchored to a large buyer, the supplier’s receivable is financed against the buyer’s creditworthiness rather than the seller’s financials, and the anchor’s cheap capital passes partway down the chain. The ADB has pushed this model explicitly: “let big companies help unlock funding for smaller ones,” in the survey program’s framing, with liquidity channeled to lower-tier SMEs that banks will not price on their own statements. In practice, platforms connect the pieces: Indian network Vayana, for example, links MSME suppliers into European anchor buyers’ supply chain finance programs so the EU buyer’s cost of capital reaches the supplier, and anchor-embedded SCF arrangements across the market typically price in the 10 to 16 percent per year range for the supplier, per 2025-2026 market pricing guides. The cost is the second-best feature. The best feature is that approval logic lives outside the SME’s own balance sheet, which is precisely the thing the front-door rejection punished. A three-year-old exporter with thin books and a Fortune-listed buyer is, under anchor-anchored finance, a good credit wearing bad paperwork. The constraint is structural and non-negotiable: the anchor must participate. Someone at the buyer has to confirm invoices on the platform, accept the payment-term implications, and often field a treasury conversation about supply chain finance programs. Suppliers to large multinationals in electronics, FMCG and auto chains get this infrastructure handed to them by procurement departments. A supplier selling to a mid-sized regional wholesaler has no anchor to borrow against, and path one closes. The failure mode is concentration too: if the anchor hits trouble, the financing window closes with it, and the exporter discovers it had one lender wearing a buyer’s face. Path two: rent a multilateral’s rating The second detour changes whose guarantee stands behind the loan. Development banks with AAA ratings issue guarantees and risk-sharing covers to local commercial banks, letting those banks lend to SME exporters they would otherwise decline. ADB’s Trade and Supply Chain Finance Program operates through nearly 300 partner banks on exactly this logic, and the model replicates at national scale: Kenya’s export credit guarantee scheme covers 50 percent of trade finance loans for agricultural exporters; Ghana’s EXIM guarantee facility backs cocoa, cashew and shea exporters; Ghana’s GIRSAL risk-sharing facility absorbs up to 50 percent of agricultural loan defaults. In India, the government’s Interest Equalization Scheme has historically knocked up to 3 percentage points off MSME manufacturers’ pre- and post-shipment credit costs, an illustration of how a public instrument, guarantee or subsidy, lands directly in the borrower’s rate (market pricing guides, 2025-2026). The cost stack here has two layers and only one is visible. The visible layer is the borrower’s rate, which sits near commercial levels, typically the 8 to 11 percent per year range in 2025-2026 for local-currency export credit in major emerging markets, less any equalization benefit. The invisible layer is eligibility friction: guarantee programs attach to sectors, registration statuses and documentation standards, and a firm that qualifies for nothing gets nothing, regardless of how good the program is on paper. Coverage caps bite as well; a 50 percent guarantee de-risks the bank’s exposure but rarely doubles its appetite, and the guarantee fee itself, where charged, adds basis points to an already thin-margin trade. The honest assessment of path two is that it is the cheapest money on this list when it works, and the least reliable to find when you need it. Program availability varies by country and year, partner-bank participation varies by branch, and the ADB’s own numbers, $5.7 billion of trade supported in 2025 against a $2.5 trillion gap, show the pipeline is deep but narrow. An exporter who banks with a partner institution and operates in a covered sector should exhaust this path before any other. An exporter who does not should not wait for it to arrive. Path three: pay for speed The third detour abandons the bank’s pricing entirely and buys time. Non-bank fintech lenders finance export invoices against shipment documents rather than financial statements: no collateral, decisions on buyer credit and document quality, disbursal in 24 to 72 hours. The pricing reflects what it replaces. In 2025-2026 platform terms, India-based Drip Capital advances 80 to 90 percent of invoice value on post-shipment export invoices at 1.5 to 2.5 percent per month; invoice marketplace KredX priced in the 12 to 20 percent per year range in 2026; the RBI-regulated TReDS platforms (M1xchange and peers) ran 8 to 15 percent per year through competitive bidding in 2026 among institutional financiers; across African markets in 2026, export-focused platforms charge roughly 1.5 to 3.5 percent per month, which compounds to an annualized 18 to 42 percent per the 2025-2026 market pricing guides. Traditional export factoring, where coverage exists, prices out cheaper: a 2026 all-in range of 2 to 4 percent of invoice value for a typical 60-to-90-day export invoice, with non-recourse protection costing a premium over recourse (export factoring market guides, 2026). Table 2: The three detours, priced side by side Path Instrument Indicative cost Speed Hard constraint Buyer-anchored SCF Receivable financed on buyer’s credit ~10-16 percent per year Days, once anchor is on platform Anchor buyer must participate DFI guarantee via local bank Guaranteed/trade credit line ~8-11 percent per year, less subsidies Weeks; program-dependent Sector and partner-bank eligibility Fintech invoice financing Post-shipment advance 1.5-2.5 percent per month (18-30 percent per year); TReDS 8-15 percent per year 24-72 hours Ticket caps; buyer-document quality Source: market pricing guides compiled from SpheraLink (2025-2026), Trad (2026) and All Frontier Global factoring guides The monthly-percentage quote deserves translation, because it is where fintech customers get surprised. A 2 percent monthly fee on a 75-day receivable is not 2 percent per year; annualized it approaches 24 percent, and the food-export guides’ 18 to 42 percent APR range is the honest frame. At those rates, fintech financing is a bridge, not a diet: it converts a confirmed order into cash now and bills the margin for the privilege. The Ghanaian shea case circulating in 2026 trade-finance guides, $42,000 advanced within 48 hours against an order track record and a confirmed letter of credit, is the model working as designed. The same firm running every shipment through the platform for a year would hand over more in fees than its bank lending would have cost, had the bank said yes. The file that unlocks all three Every detour prices the same underlying asset: clean documents. The fintech advance is underwritten on the commercial invoice, packing list, bill of lading and proof of shipment; the anchor program needs the buyer’s invoice confirmation, which presumes the invoice matches the order exactly; the guarantee route attaches to registration statuses and compliance files. An exporter carrying a messy document history pays for the mess at every window, in higher fintech spreads, slower anchor onboarding and narrower program eligibility. The industry’s own modernization push makes this worse before it makes it better: ADB’s report leans on digitalizing trade by 2030, e-documentation and shared KYC utilities as the structural fix for vetting cost, which means exporters whose paperwork is already digital will clear the new rails first while paper-based peers wait. Preparation has a measurable payoff at the margin that matters. A 2 percent monthly fintech fee and a 2.4 percent monthly fee differ by 20 percent in annual cost; the difference between those quotes is usually buyer-document quality and country coverage, not negotiation skill. Similarly, the reapplication file matters because the screening layer is going automated: the 84 percent AI adoption figure in the ADB survey means the reviewer of a rejected application is increasingly a model trained on document patterns, and a resubmission with reason codes addressed reads differently from an identical retry. None of this appears in any program brochure. All of it shows up in the rate. Which detour, which order Sequencing matters more than selection, and the logic follows the exporter’s actual exposure rather than the platform’s marketing. Order from a large creditworthy buyer, repeat business: anchor-anchored supply chain finance first, at 10 to 16 percent per year, because the buyer’s credit is the asset and the cost stays tolerable at scale. Push procurement to onboard the anchor if the program is not yet live. Domestic or regional bank relationship, covered sector, no urgency: the guarantee route first, at 8 to 11 percent per year before subsidies, because it is the cheapest capital on the list. Apply early; eligibility friction takes quarters, not days. Confirmed order, cash deadline, bank door closed: fintech invoice financing as the bridge, priced at 18 to 30 percent annualized. Use it to fulfill, get paid, and return to paths one and two for the next cycle; do not let a bridge become the permanent capital structure. Any path: keep the rejection itself in the file. Reapplication data, reason codes and document quality are what AI screening models, the 84 percent adoption wave, train on, and a clean reapplication file is the cheapest credit improvement an exporter can buy. The uncomfortable summary is that none of the three detours fixes the $2.5 trillion gap, because the gap is a banking-system economics problem and the detours are firm-level arbitrage around it. What they fix is the individual exporter’s quarter. For the shea exporter with the confirmed European order, that is the difference between shipping and not shipping, and until the front door reopens, shipping is the metric that counts. Data basis Data as of November 2026. Gap and rejection figures come from ADB’s ninth Global Trade Finance Gap Survey, released January 15, 2026, which analyzed responses collected during 2023-2025 from more than 110 trade finance providers representing up to a third of the global market; secondary reporting describes the underlying panel as roughly 137 banks and 185 companies across 50 countries, and this article uses ADB’s own release for headline figures rather than the secondary count. The $2.5 trillion gap is ADB’s estimate of unmet trade finance demand for 2025, unchanged from its 2023 estimate, expressed in US dollars at global scale. SME and corporate rejection rates are application-level rates within the surveyed providers’ books, not economy-wide approval statistics, and ADB itself notes the near-parity finding requires further research. Pricing ranges for the three detours (10-16 percent, 8-11 percent, and 1.5-2.5 percent per month with TReDS at 8-15 percent) come from published market pricing guides and platform-published terms for 2025-2026, compiled in the sources; the estimates vary by buyer country, tenor and document quality; they are indicative ranges, not quotes. The Ghana shea exporter case is as reported in the trade-finance guides cited. What this analysis cannot show is provider-specific pricing for any individual transaction. Sources ADB , “Demand for Trade Finance to Rise Amid Supply Chain Realignment,” news release on the 9th Global Trade Finance Gap Survey, January 15, 2026 SpheraLink , “Export Finance and Working Capital Every New Exporter Must Understand,” 2025-2026 market pricing guide Trad , “Export Factoring Explained: How It Works, Costs, and How to Qualify,” 2026 All Frontier Global , invoice discounting and factoring lexicon, platform pricing compendium, 2026 FoodExpoConnect , “Export Financing for African SMEs: Grants, Loans & Alternative Capital in 2026,” 2026 About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
Gigawatts Are Announced. Megawatts Must Be Energized. SeaPRwire

Gigawatts Are Announced. Megawatts Must Be Energized.

HUMAIN’s 6.6 GW pipeline, the 1.5 GW national target and the transformer queue that decides which arrives first (2026) The number that governs Saudi Arabia’s AI infrastructure story is not the biggest one. It is 467, and it counts megawatts: the data center load actually drawing power across the kingdom in the first quarter of 2026, as disclosed by the Ministry of Communications and Information Technology. Against it stand the announcements. HUMAIN, the sovereign AI company owned by the Public Investment Fund, carries a pipeline of 6.6 gigawatts by 2034. The national target under Vision 2030 is 1.5 gigawatts by 2030. Planned capacity tracked at 3.4 gigawatts in the second quarter of 2026. The distance between 467 megawatts and any of those figures is not a rounding error, a financing gap or a demand question. It is an electrical delivery schedule, and it moves at the speed of substations. This article works through what that arithmetic means structurally. The announced pipeline is real capital and real demand, not vaporware, and dismissing it would miss the actual story. The story is that two independent constraints, grid energization on the supply side and anchor-tenant concentration on the demand side, determine which announced gigawatts become billed megawatts, and both constraints bite hardest on the participants least able to wait. Neither constraint is visible in the announcement numbers that dominate the sector’s coverage. The gap, measured The operational series is short and unambiguous. Saudi Arabia operated 68 MW of data center capacity in 2021, 440 MW at the end of 2025, and 467 MW in Q1 2026, spread across more than 60 facilities, per MCIT figures (Saudi Press Agency, August 15, 2026). Cumulative investment in data centers and digital infrastructure is reported at SAR 56.2 billion by the same official channel, though a separate market tally puts data-center-specific investment nearer SAR 16 billion; the wider figure includes the digital envelope, not just halls and cooling. Growth of roughly six times in four years is a fast buildout by any regional standard, and it is still less than a third of the national target for 2030. Table 1: Saudi data center capacity, from operating load to announced pipelines Measure Value Status Source and period Operational load, 2021 68 MW Actual MCIT, year-end 2021 Operational load, end-2025 440 MW Actual MCIT, December 2025 Operational load, Q1 2026 467 MW Actual MCIT, April 2026 disclosure National target 1.5 GW by 2030 Target Vision 2030 program documents Planned pipeline 3.4 GW Planned Asharq Business tracking, Q2 2026 HUMAIN interim goal 1.9 GW by 2030 Target CEO Tareq Amin, November 2025 HUMAIN pipeline 6.6 GW by 2034 Pipeline HUMAIN disclosures, 2025-2026 Source: Saudi Press Agency , August 15, 2026; MCIT quarterly figures as compiled by Saudi Energy Consulting , 2026 Three different denominators hide in that table, and conflating them is how the sector’s coverage misleads. Operational load is electricity actually contracted and drawn. National targets are policy commitments with budget lines but no delivery dates. Corporate pipelines are land, capital and intent. The 6.6 GW figure and the 1.9 GW figure are both HUMAIN’s, a fact worth pausing on: the company’s own interim goal is 27 percent larger than the entire national 2030 target, and both cannot be delivered inside the decade without a step-change in energization speed that nothing in the current record yet demonstrates. The two variables that decide the outcome The first structural variable is energization, and its physics is unforgiving. A data center’s capacity is the power its equipment can draw, not its floor area or its server count, and the moment capacity exists is the moment a utility connects firm power. Saudi Arabia does have system-level headroom: the grid delivered 160.5 TWh to customers in the first half of 2025, an annualized rate near 321 TWh, so the 2030 target of 1.5 GW works out to roughly 3.7 percent of current deliveries and the 6.6 GW pipeline to about 16 percent. The constraint is not generation in aggregate. It is allocation and delivery: every megawatt of new AI load must pass through a feasibility study, a capacity review, an interconnection point, substation expansion and final grid acceptance, a sequence that industry trackers summarize as “a grid event, not a fit-out.” The evidence sits in procurement documents rather than press releases. Tenders ran in the first half of 2026 for a 2,000 MVA bulk supply point and two substations, the physical preconditions for HUMAIN’s dense AI load. Transformer lead times run two to four years across the global supply chain. HUMAIN’s own behavior confirms the ordering: the company signed its xAI framework, covering 500 MW of power and $3 billion in equity, in November 2025; locked a joint venture with stc’s center3 covering up to 1 GW in December 2025; signed a $12 billion financing framework with the National Infrastructure Fund in January 2026; and only then concentrated its chip and application agreements, with AMD, Microsoft, Qualcomm and Adobe, around the 2026 LEAP cycle, where industry tracking put total announced deals at $15 billion. Power first, capital second, chips third. That is the signing order of a company that knows its binding constraint. The second structural variable is anchor concentration. The demand that justifies Saudi Arabia’s buildout does not arrive as a smooth market; it arrives as a handful of sovereign-scale commitments, each of which must convert from announcement to contract to energized load. The conversion record so far is mixed. HUMAIN broke ground on twin 100 MW campuses in Riyadh and Dammam in August 2025 with a committed go-live in Q2 2026; as of end-July 2026, the go-live of either campus cannot be verified from any filing or credible report, and the company has declined to disclose delivery progress when asked. The stc/center3 joint venture targeting up to 1 GW was extended but not signed as of a June 2026 filing. DataVolt’s Riyadh East project, 44 MW total with 36 MW anchored by HUMAIN, had not closed financing. AWS committed $5.3 billion to its Saudi region and an AI zone with HUMAIN carrying 50 MW by 2028; Microsoft is embedding the ALLaM model into its Copilot stack; AirTrunk’s founder Robin Khuda described the partnership as bringing together “the whole digital ecosystem.” Each is a real commitment. None so far is billed megawatts. The two variables are independent, and this matters for the argument’s testable form. Energization is a supply-side, physical quantity: it moves with procurement, manufacturing and utility scheduling, and no demand event accelerates a transformer. Anchor conversion is a demand-side, contractual quantity: it moves with counterparties’ capital cycles and their own global capacity plans, and no substation accelerates a signature. A bottleneck in one does not imply a bottleneck in the other, which is why the sector needs to watch both, and why a month of good news on deals says nothing about power and vice versa. Where each variable is heading Energization capacity is growing, but on a curve that lags announcements by construction. The visible markers are the substation tenders of the first half of 2026, the bulk supply point procurement for the 6 GW campus, and the quarterly MCIT load series, which added only 27 MW between end-2025 and Q1 2026. At that net-add rate, the 1.5 GW 2030 target requires roughly 260 MW of net additions per year from 2027 onward, five to ten times the current quarterly pace sustained annually. HUMAIN’s stated plan, 11 data centers progressing at about 50 MW per quarter, would meet the interim goal only if every site energizes on schedule, with zero slippage across a five-year window, in a market where the two flagship 100 MW campuses have already slipped past one committed quarter. Anchor concentration is heading toward fewer, larger, slower deals rather than many small ones. The sovereign logic is explicit in how the buyers behave: government and enterprise customers paying for “sovereign” AI want models running on in-Kingdom infrastructure with documented evaluation evidence, which pushes workloads to HUMAIN’s owned stack rather than to third-party colocation. That concentration is a strength for the champion and a scarcity for everyone else. The xAI, Microsoft, AWS and stc relationships absorb the first gigawatts of priority demand. What remains for non-anchor participants is capacity that energizes later, sells into a market where the sovereign champion sets terms, and carries no committed tenant to underwrite it. What sovereign demand actually consists of It is worth spelling out what the anchor tenants are buying, because “sovereign AI” reads like branding until you look at the procurement logic. The Saudi government and its enterprise buyers do not simply want large models; sector reporting through 2026 describes buyers who require models to run on in-Kingdom infrastructure, with documented evaluation evidence and auditable human-oversight records, before a workload counts as sovereign. That requirement converts directly into HUMAIN’s architecture. The company must own data centers, contract chips, host models and operate applications, because a government buyer cannot trace a workload through a foreign hyperscaler’s multi-tenant regions and still call it sovereign. The commercial structure that follows is an exchange of exclusivity for reach. Microsoft embeds the ALLaM model into its 365 Copilot stack; AWS places ALLaM in Bedrock and hosts HUMAIN’s compute on its Marketplace. From the hyperscalers’ side, this buys a compliant sovereign offering in a market where foreign operators cannot sell sovereignty themselves. From HUMAIN’s side, it buys distribution the champion could never build alone, at the cost of anchoring its demand inside platforms whose global capacity plans it does not control. The vertical integration that looks like strength in the press releases is also a dependency: the sovereign stack’s utilization now moves with two American companies’ enterprise cycles. This is where the second structural variable stops looking like a constraint and starts looking like a design choice. Saudi Arabia could, in principle, have spread the demand across many tenants the way a commercial colocation market does. It chose concentration, because concentration is what makes the sovereignty claim auditable. The concentration then feeds back into the first variable: a single champion’s sites receive priority in the interconnection queue precisely because they carry the state’s own demand. The two variables are independent in their physics but coupled in the kingdom’s institutional design, and that coupling is the strongest reason to expect the pattern to persist rather than correct. The comparison next door The United Emirates runs the same experiment with a different architecture, and the contrast isolates which parts of Saudi Arabia’s bottleneck are universal and which are chosen. Reporting on both markets through 2026 describes the UAE model as asset-light: sovereign demand is served through operators that lease and aggregate capacity rather than owning the full stack, letting projects come online faster against rented power and shared infrastructure. Saudi Arabia’s HUMAIN sits at the opposite pole, owning land, halls, power contracts, chips and models in one balance sheet, a structure its own leadership frames as vertical integration in service of the sovereign claim. The trade-off shows up exactly where this article’s two variables predict. The asset-light model converts announcements to megawatts faster because it buys energized capacity rather than building it; it gives up control over sourcing, pricing and the audit trail that sovereign buyers demand. The heavy model controls everything and therefore waits for everything: its speed is the speed of its own substations. Neither is wrong; they are bets on different customers. For buyers who want sovereignty with evidence, the heavy model wins on compliance and loses on time. For buyers who want capacity now, the light model delivers first and answers questions later. For the region’s suppliers and investors, the comparison carries one practical instruction. A gigawatt announced in Riyadh and a gigawatt announced in Abu Dhabi do not carry the same delivery risk, and pricing them alike is the fastest way to own the wrong exposure. The delivery-status gap, energized versus announced, is wider inside the heavy model, which means Saudi projects carry more of the schedule risk and UAE projects carry more of the counterparty risk. Participants should know which risk they are underwriting before they price either. Who feels this first The queue of losers, if that is the word, forms in a predictable order. Foreign cloud and colocation entrants without an anchor contract feel it first: they can build shells, but the scarce goods, firm power and sovereign workloads, are being allocated to the champion’s stack and its named partners. Chip and equipment vendors feel it second, on their order books: hardware shipped against announcements waits in crates for energized halls, converting vendor revenue recognition into a bet on someone else’s grid. Mid-tier colocation operators and capacity resellers feel it third, squeezed between sovereign supply they cannot access and hyperscaler regions that arrive late but arrive complete. Investors price it last and most bluntly: a valuation keyed to announced gigawatts is underwriting construction and grid-connection risk, not demand risk, and the 27 MW quarterly net-add figure is the denominator that discipline eventually re-imposes. The kingdom itself absorbs much of the cost through the sovereign balance sheet, which is the point of a sovereign champion: PIF can hold land, power contracts and financing commitments open for years in a way no private developer can price. That patience is an advantage, and it is also why the private participants around the champion, rather than the champion itself, are the ones whose timelines break first. Table 2: HUMAIN’s major commitments, announcement to conversion status Counterparty Scope announced Announced Conversion status as of mid-2026 xAI 500 MW power, $3B equity framework November 2025 Framework; campus power not yet energized stc / center3 JV up to 1 GW December 2025 Extended, not signed, per June 2026 filing National Infrastructure Fund $12B financing framework January 2026 Framework; project-level closes pending AWS $5.3B region; 50 MW AI zone by 2028 2025-2026 Region committed; AI zone capacity target 2028 AMD, Microsoft, Qualcomm, Adobe Chips, models, applications 2026 LEAP cycle Announced at $15B total deal value Source: HUMAIN disclosures and market tracking compiled by NextFin , 2026; deal values as reported by the companies and Global Data Center Hub tracking What would prove this call wrong A structural argument earns its keep by naming its own failure signals, so here they are, ranked by how early they fire. The twin 100 MW campuses energize close to a revised schedule, and MCIT’s quarterly series jumps by more than 100 MW in one or two quarters. That would show the grid queue is shorter than the procurement record implies, and the supply-side constraint loosens. The 2,000 MVA bulk supply point and substation tenders convert to awarded contracts within two quarters, and equipment orders for transformers show delivery dates inside 24 months. That would compress the energization curve materially. The stc/center3 joint venture is signed with a delivery date, and DataVolt’s Riyadh East financing closes. That would show anchor conversion is normalizing rather than concentrating. A non-anchor foreign operator announces an energized, tenanted hall at scale without sovereign workloads. That would falsify the concentration claim directly. If most of these fire through 2027, the right model is a fast-follow market with a temporary grid lag, and the announced pipeline mostly arrives, late. If they do not, the correct reading of 2026’s announcement wave is simpler and colder: the kingdom is buying optionality on a power delivery curve that only the sovereign champion can afford to wait for, and everyone else in the value chain is pricing megawatts they have not been promised. Data basis Data as of November 2026. The capacity series (68 MW, 440 MW, 467 MW) comes from MCIT disclosures reported by the Saudi Press Agency on August 15, 2026. The SAR 56.2 billion and SAR 16 billion investment figures count different scopes and are presented separately, not averaged. The 1.5 GW national target, the 3.4 GW planned pipeline (Asharq Business, Q2 2026) and HUMAIN’s 6.6 GW and 1.9 GW figures are commitments and pipelines, marked as such in the table, never merged with operational load. Grid delivery arithmetic uses 160.5 TWh of first-half 2025 deliveries annualized to about 321 TWh, with target shares computed against that annualized base; the estimate of required net additions divides the remaining distance to 1.5 GW by the years to 2030. Conversion statuses for HUMAIN’s commitments come from company statements and market filings through mid-2026 as compiled by NextFin. Definitions: “energized” means firm power contracted and drawn at the interconnection point; “planned” means a disclosed project with no energization date; “pipeline” means a corporate build goal with land and capital attached. Limitations MCIT publishes quarterly operational load, not energization dates per project, so the gap between contractual power and drawn power is inferred, not observed. HUMAIN’s campus go-live status is negative evidence, absence of a service announcement, which cannot distinguish delay from quiet commercial operation. Two low-credibility tracker figures (a 6,600 MW AI-grade pipeline; DataVolt’s 1,500 MW NEOM load) were excluded from the tables for provenance. Sources Saudi Press Agency , MCIT data center capacity and investment disclosures, August 15, 2026 (site home) Saudi Energy Consulting , “HUMAIN’s 6.6 GW AI Campus Dream: Can Saudi Arabia Power the Data Center Rush?,” 2026 NextFin , “Saudi Arabia, UAE Push Ahead With Data Center Plans, but Live Capacity Lags Announced Gigawatts,” 2026 Asharq Business , planned capacity tracking, Q2 2026 (site home) Global Data Center Hub , LEAP 2026 deal value and project tracking, 2026 (site home) About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
Indonesia’s QRIS Boom: One Bank Figure Says 13.66 Billion Payments, a Trade Brief Says 2.5 Billion SeaPRwire

Indonesia’s QRIS Boom: One Bank Figure Says 13.66 Billion Payments, a Trade Brief Says 2.5 Billion

Auditing the denominator, the vintage and the fee schedule behind Indonesia’s QRIS numbers, 2025-2026 In the first half of 2026, Bank Indonesia recorded 12.55 billion QRIS transactions worth Rp 1,120 trillion. In a trade brief published in June 2026, New Zealand’s Ministry of Foreign Affairs and Trade put Indonesia’s QRIS volume for calendar 2025 at 2.5 billion transactions worth Rp 262.1 trillion. The second document describes the same national QR system, in an earlier year, at roughly a fifth of the central bank’s count. Both numbers are wearing official clothes. Only one of them can describe what it claims to describe. This article audits the disagreement rather than picking a winner. The method is the one regulators’ own statisticians use: take each published figure, reconstruct its denominator, its time window and its definition, then test whether the numbers could coexist under any honest reading. The answer here is not fraud or a data error in the usual sense. It is something more common and more costly: a stale vintage circulating under a current-year label, plus a fee schedule whose headline contradicts its own fine print. The distinction matters, because a reader who mistakes an old vintage for a growth collapse will make a different decision from one who understands the labels. What each document actually says Start with the central bank, which is the system operator and the natural source of record. At its December 2025 Board of Governors Meeting, Bank Indonesia reported full-year 2025 QRIS figures: approximately 13.66 billion transactions, around 59 million users, and roughly 42 million merchants, of which about 90 percent are micro, small and medium enterprises. The transaction count ran at more than double the bank’s own annual target of 6.5 billion. These figures were reported publicly and picked up across the payments press; they supersede the bank’s earlier mid-year data, which had shown 10.31 billion transactions through September 2025 alone. The other document is narrower. MFAT’s June 2026 trade brief, in the row its authors labeled 2025, carries two QRIS numbers: 2.5 billion transactions and Rp 262.1 trillion in value. The brief is a trade-promotion document, not a payments statistics bulletin, and its payment rows cite aggregated sources. Bank Indonesia’s own published series, from its Laporan Pelaksanaan Sistem Pembayaran (payment system report) and its August 2026 release, gives a different and internally consistent trail: 55.43 million registered users at the end of 2024, 59.53 million at the end of 2025, 65.77 million by June 2026, and merchant counts of 42.75 million at end-2025 rising to 44.86 million by June 2026, with the MSME share at 96.68 percent in the mid-2026 reading. Deputy Governor Filianingsih Hendarta put the bank’s forward frame on the record in January 2026: “In 2026, we will continue to drive the expansion of QRIS by embracing the theme of independence, represented by 17, 8, and 45,” referring to targets of 17 billion transactions, cross-border acceptance in eight countries and 45 million merchants (Marketing-Interactive, January 2026). Nobody announcing a 17 billion target for 2026 believes the system did 2.5 billion in 2025. The two documents are not describing the same year with different methods. Something else is going on. Table 1: Three QRIS readings, their labels and their implied average ticket Source, publication date Period label Transactions Value Implied avg ticket MFAT trade brief, June 2026 Calendar 2025 2.5 billion Rp 262.1 trillion Rp 104,840 Bank Indonesia RDG, December 2025 Calendar 2025 13.66 billion not published in this release not derivable Bank Indonesia release, August 2026 H1 2026 12.55 billion Rp 1,120 trillion Rp 89,243 Source: Bank Indonesia releases and December 2025 RDG figures as compiled in the payments press; MFAT trade brief via MFAT , June 2026 Taking the denominators apart The ticket column does most of the audit work here, so it deserves its own paragraph. An average ticket is value divided by count, and each pair of numbers implies one. MFAT’s pair implies Rp 104,840 per transaction. Bank Indonesia’s first-half 2026 pair implies Rp 89,243. These are close enough to be the same system with the same mix; a QR payment rail’s average ticket does not swing 80 percent in twelve months without an announced structural change, and no such change occurred. So the disagreement is not about the size of a transaction. It is about how many transactions there were, and the gap between 2.5 billion and 13.66 billion is a factor of 5.5. Now test the vintage. QRIS volume by year, from Bank Indonesia’s historical reporting: roughly 2 billion transactions in 2022, about 3.5 billion in 2023, and by 2025 a run rate that had already passed 10 billion through September alone. MFAT’s 2.5 billion, paired with Rp 262.1 trillion, sits cleanly in the 2022 range. A figure that belongs to 2022, wearing a 2025 label in a document published in 2026, is a stale vintage, not a conflicting measurement. This is the audit’s first finding, and it is the mundane kind: a trade brief recycled an old row without updating it, and the label traveled further than the data. The third check is the bank’s own projection table, because projections are where well-run institutions mislead themselves most honestly. In the governor’s annual meeting remarks published in late 2025, Bank Indonesia’s table projected QRIS volume of 15,374 million transactions and Rp 1,486.8 trillion in value for 2025. The actual outturn was 13.66 billion, about 11 percent under the projection. That is a normal miss, and it says something the raw growth numbers do not: even the operator that runs the rail, with real-time visibility, overestimated by a margin a casual reader would never notice between “13.66 billion” and “15.37 billion.” Projection and actual must never be merged into one series, and in the bank’s own documents they are marked separately. In derivative documents they frequently are not. Table 2: Users and merchants, two official readings of the same quarters Period Users (BI payment system report) Merchants MSME share Q4 2024 55.43 million not in this row not in this row Q4 2025 59.53 million 42.75 million not in this row December 2025 RDG ~59 million ~42 million ~90 percent June 2026 65.77 million 44.86 million 96.68 percent Source: Bank Indonesia payment system report 2025 and August 2026 release; December 2025 RDG figures as compiled by the payments press Here the audit finds agreement rather than conflict. The RDG round numbers sit within rounding distance of the report’s precise ones, for the same periods. When two official products from one institution agree to within a rounding error, the vintage question is settled for those cells: they are the same year, honestly labeled. Where the numbers cannot coexist So far the audit has found one stale row. The deeper incompatibility sits in the fee schedule, and it is the kind that survives even perfect data. From October 1, 2026, Bank Indonesia extended the zero merchant discount rate, MDR, to every merchant category on QRIS transactions up to Rp 100,000. Before that change, the zero band applied to micro merchants (UMI) up to Rp 500,000, and regular merchants paid 0.7 percent on transactions above Rp 100,000, with education at 0.6 percent, fuel retailers at 0.4 percent, and designated public-service categories at zero. These are the bank’s published category rates. The 2026 change did not abolish the schedule above Rp 100,000; it removed the charge inside the band for everyone. Now put the average ticket next to the band. The first-half 2026 average ticket is Rp 89,243, inside the zero band. But an average inside the band does not mean most value is inside the band, and this is where the “QRIS is free” framing breaks. If the transaction distribution has a long right tail, which tourist and large-ticket behavior guarantees it does, then the count-weighted median can sit at Rp 60,000 while the value-weighted majority sits above Rp 100,000, where the 0.7 percent rate still applies. The inbound tourist data makes the tail concrete: in January 2025, foreign visitors made 24,121 inbound QRIS payments in Bali worth Rp 7.1 billion, an average of roughly Rp 294,000 per transaction, three times the national average and well inside the charged tier. A kiosk selling coffee and a hotel booking share the same QR standard, the same statistics, and opposite fee treatment. The honest statement of the fee regime is therefore count-free, value-priced: by transaction count, the zero band covers a large share of Indonesian QRIS activity; by transaction value, the charged tiers still carry the bulk of the money. Neither half of that sentence is a contradiction. Announcing only the first half, as much of the coverage did, is the second audit finding: the denominator switched from transactions to value without an announcement. The third incompatibility is smaller and worth naming because it recurs across the region’s payment statistics. The 2025 quarter-on-quarter growth figures in the payment system report, 139.99 percent for volume and 107.22 percent for value in Q4 2025, are quarter-over-quarter rates. Annualized naively, they would imply a system several times larger than the bank’s own annual count, which of course they do not describe. Quarterly growth and annual totals answer different questions, and the audit’s rule is to never let a quarter’s percentage borrow an annual denominator. What the cross-checks establish Run the findings together and the audit supports four statements with defined denominators. The 13.66 billion figure is the system operator’s actual count for calendar 2025, cross-checked against its own mid-year run rate (10.31 billion through September 2025) and its user and merchant series, which match the RDG release to within rounding. The 2.5 billion figure is internally coherent, carries a plausible 2022-era average ticket, and matches QRIS volume for calendar 2022; its 2025 label in the 2026 brief is a vintage error, not a measurement dispute. The fee schedule is count-free on tickets up to Rp 100,000 from October 2026 and value-priced above it, at 0.7 percent for regular merchants, with the national average ticket (Rp 89,243, H1 2026) below the band and tourist tickets (Rp 294,000, Bali, January 2025) far above it. The bank’s 2025 projection (15,374 million transactions) exceeded its actual by roughly 11 percent, a reminder that operator projections and operator actuals are different series even when both come from the same institution. The fraud line belongs in this accounting too, because scale and loss move together. The Indonesian payment industry’s own anti-fraud body recorded Rp 4 trillion in social-engineering fraud losses for calendar 2024 (ASPI/IASC annual report, via Bank Indonesia). A system that grew from roughly 2 billion transactions in 2022 to 13.66 billion in 2025 grew its fraud surface at the same time, and the 2026 zero-fee band, by pushing more low-value commerce onto the rail, grows it further. The other rail and the other rows A QRIS audit that stops at the QR code misses the second half of Indonesia’s payment stack, and the second half carries its own pricing lesson. BI-FAST, the central bank’s real-time interbank transfer rail launched in December 2021, handled 1.359 billion transactions in Q4 2025 alone, a 30.44 percent increase, and carried 82.6 percent of retail payment volume that quarter (Bank Indonesia payment system report, 2025). Its pricing is published in pieces a reader can actually check: the infrastructure charges participating banks Rp 19 per transaction for interbank credit transfers, and the fee a sending bank may charge its customer is capped at Rp 2,500 per transfer. Two rails, two pricing logics: QRIS prices the merchant by ticket size and category, BI-FAST prices the sender by a flat cap with a known wholesale cost underneath. An operator pricing Indonesia payments without separating the two will quote a “free” QR acceptance story against a capped transfer story and conclude the stack is cheaper than its own invoice shows. The denominator here is the transfer, not the ticket, and the cap is per transfer regardless of amount, which makes BI-FAST regressive in exactly the way QRIS’s schedule is progressive. The account-ownership rows in the same trade brief deserve the same vintage treatment as the QRIS rows. MFAT’s brief carries adult bank account ownership of 60 percent for 2025. The World Bank’s Global Findex, the standard reference, measured 56 percent for 2024, up from roughly 52 percent in 2021. The three numbers form a plausible trend line rather than a contradiction, but they are three different instruments: a national promotional target row, a survey estimate with a defined sample and questionnaire, and an earlier survey vintage. Unlike the QRIS case, where the factor-of-5.5 gap ruled out honest trend reading, here a reader could merge the rows into one series and get an answer that is roughly right and methodologically wrong. The audit distinction is between numbers that cannot coexist (QRIS 2025) and numbers that coexist only because their definitions drift (ownership 2021 to 2025). Both belong in the same caution, for different reasons. Cross-border expansion adds a third family of numbers with an unstated denominator. QRIS is now accepted in Malaysia, Thailand, Japan, China and Singapore, with UAE links under exploration, and the bank’s 2026 target is acceptance in eight countries (Deputy Governor Hendarta, January 2026). The January 2025 Bali figures, 24,121 foreign-visitor transactions worth Rp 7.1 billion, are the only published slice of what cross-border volume actually looks like at ground level: tiny in count, large in ticket, concentrated in one tourist island. A “five countries” acceptance claim and a “24,121 monthly transactions” usage figure describe the same program from opposite ends, and neither headline carries the other’s denominator. The new QRIS Tap feature shows the same pattern in miniature: launched in October 2025, it reached 508,000 transactions across 14 provinces within months, a growth rate of roughly 1,200 percent month-on-month that is arithmetic on a very small base. Percentage growth on small bases is the most quotable and least informative number in payments statistics. What this section adds to the verdict is a rule about families of numbers. The QRIS vintage error was one bad row; the ownership drift, the cross-border count and the Tap growth rate are structurally recurring: every number that travels from an operational system into a promotional document tends to shed its denominator on the way. The fix is not distrust of the operator. It is treating every transferred number as a claim about a specific period, a specific unit and a specific base, and refusing to quote it without those three attachments. Verdict The two headline numbers are not a mathematical contradiction; they are two different datasets, one current and one roughly four years old, sharing a label. On the evidence of ticket consistency, series continuity and the bank’s own targets, the 13.66 billion reading stands as the description of 2025 and the 2.5 billion reading stands as a stale row that should carry a 2022 label or be dropped. The fee story, which survives the data dispute untouched, is a denominator switch: free by count inside the band, charged by value above it, with the average tourist transaction paying three times over. A reader who carries one sentence out of this audit should carry this one: before quoting a payments statistic, ask which year the number belongs to and which denominator the fee applies to, because in Indonesia’s QRIS both questions have answers that the headlines do not print. Methodology Data as of November 2026. This audit used only published figures and did no fieldwork; every number carries its source in the text or the tables. The core computation is the implied average ticket: transaction value divided by transaction count for each labeled period, computed without rounding the inputs (MFAT pair: Rp 262.1 trillion over 2.5 billion; Bank Indonesia H1 2026 pair: Rp 1,120 trillion over 12.55 billion). Vintage attribution compares the disputed pair against Bank Indonesia’s public annual volume series and its mid-year 2025 run rate, treating a factor-of-5.5 gap with consistent ticket sizes as evidence of a period mismatch rather than a definitional one. Time frame: figures labeled calendar 2025, Q4 2025, H1 2026 and January 2025, all as published between June 2026 and August 2026 plus the December 2025 RDG. The denominator definition for the fee analysis is explicit: count-weighted share inside the Rp 100,000 zero band versus value-weighted share, with Bali inbound transactions as the tail illustration. Limitations: the bank did not publish a full-year 2025 value figure in the December RDG release, so the 2025 implied ticket cannot be computed from the operator’s own pair; the transaction-size distribution is inferred from the tourist tail and the published average, not observed; and the MFAT brief’s underlying source chain for its payment rows is not disclosed in the document itself. Sources PaymentBrief , “Indonesia Payments: QRIS, Local Acquiring and BI-FAST,” 2026 (transposing Bank Indonesia December 2025 RDG full-year figures and the MDR schedule effective October 1, 2026) Marketing-Interactive , “BI unveils cross-border expansion and merchant growth plans for QRIS,” January 2026 (quoting Deputy Governor Filianingsih Hendarta; transposing Bank Indonesia 2025 outturn and 2026 “17-8-45” targets) Bank Indonesia , Governor’s Annual Meeting remarks and payment system projections, late 2025; payment system report figures for Q4 2024, Q4 2025; QRIS release of August 2026 for H1 2026 (site home) MFAT , Indonesia trade brief, June 2026, payment system row labeled 2025 (site home) ASPI/IASC annual report, social-engineering fraud losses, calendar 2024 (no public link) About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
America’s Crypto Exchanges Lobbied for Clarity. They Got a Rulebook and a $6.3 Billion Hole. SeaPRwire

America’s Crypto Exchanges Lobbied for Clarity. They Got a Rulebook and a $6.3 Billion Hole.

US crypto policy 2026: an opt-in CFTC framework, 50 state regimes, and the reserves that paid for a record exchange hack On November 7, Binance announced that its chief financial officer was leaving the company to pursue a new venture. The announcement came eight days after hackers drained $6.3 billion in customer assets from the world’s largest crypto exchange, and nine days before the Commodity Futures Trading Commission’s chairman went on television to say the industry was voluntarily lining up under his rulebook. Two facts that look unrelated are not. The finance chief’s exit and the regulator’s recruitment pitch describe the same job from two ends: the person who has to explain the balance sheet, and the person who has to explain the rulebook, are increasingly the same overworked role. This piece is about that role. Not the traders, not the lobbyists, but the compliance and security operators inside US-facing crypto firms, the people who spent 2026 signing up for federal oversight while personally deciding whether a hacked exchange should cover its users out of its own reserves. Their public statements, collected here from interviews, conference remarks and regulatory filings, tell a consistent story. Two conditions made their year what it was, and both had to be true at once. The size of the room Start with scale. Crypto-tied organizations put more than $200 million into the 2026 midterm elections, the largest cohort of single-issue super PACs in US history, according to Public Citizen, the watchdog group that tracks corporate political spending (CNBC, October 31, 2026). Fairshake, the industry’s flagship PAC network, backed 33 House candidates, 19 Republicans and 14 Democrats, and placed a baseline of $1 million into six priority incumbents. Coinbase alone donated $25 million to Fairshake’s midterm effort in 2025, after contributing $79 million in the 2024 cycle. Ripple, whose chief legal officer Stu Alderoty told CNBC the spending was “a very good return,” gave another $25 million in 2025. That money bought access, and 2026 was supposed to be the year it converted into law. It did not. The Clarity Act, the comprehensive market structure bill, stalled in the Senate on September 15 after Democrats argued it did too little to prevent top government officials from profiting off crypto ventures. The window that remains is short. Andrew Cuomo, the former New York governor who now sits on the board of exchange OKX, told CNBC in late October that lawmaking is unlikely if Congress changes hands in January: “You’re going to have a Democratic Congress overseeing an administration… where the regulators are making decisions under the scrutiny of a hostile Congress, and that is not a good place to be.” The money also met the ballot directly, with unclear returns. Fairshake’s network told CNBC it had already spent $55 million opposing Sherrod Brown in Ohio, the former Senate Banking Committee chairman and longtime crypto critic, after spending about $40 million to unseat him in 2024. A Marist poll conducted October 15-18 showed Brown holding a four-point edge over his Republican opponent among likely voters, within the poll’s 4.5-point margin of error. Lynaugh’s own read to CNBC was that “a lot of these races are going to be extremely tight.” For the operators inside these firms, the lesson of the cycle is not that spending failed; it is that even a successful cycle buys process, not statute, and process is what their job now runs on. So the operators’ employer base is a set of firms rich enough to spend eight figures on elections, yet still without the statute they spent the eight figures to get. That contradiction frames everything else they said this year. What the operators keep saying The quotes repeat. The wording changes; the structure does not. Michael Selig, the CFTC chairman, told CNBC on November 13 that the industry is opting in. “We’re also getting interest from new entrants who say, ‘Look, signing up with 50 different state regimes is tough. We’d rather come to one regulator and get a license at the CFTC,’” he said at the Cantor Convergence conference in Miami Beach. His agency published an advance notice of proposed rulemaking on October 5, five days after the Senate vote failed, seeking comment on a framework for retail crypto commodity transactions. Selig described it as a “critical step” in keeping the United States the crypto capital of the world. Richard Teng, Binance’s co-CEO, spent his November 3 interview on CNBC’s Squawk on the Street describing an intrusion, not a product. “The attackers spent months building their way in,” he said. His account, backed by a security report the company published the same day: in June, a wallet DevOps engineer downloaded a tampered Homebrew installer while searching for a popular AI coding tool; in September, the same group posed as recruiters and ran job interviews with a second engineer, ending in a coding exercise that carried hidden malware. “From there they moved violently through our internal AI tools and obtained access that breached the system that authorized our wallet transaction,” Teng said. Ryan VanGrack, vice chairman at Coinbase, made the affirmative case to CNBC in October: “The ultimate goal is to make sure that we bring our 20th century financial system into the 21st century… In an era where affordability is top of mind for American voters, it’s important that we find a way that we can move money more cheaply.” Mason Lynaugh, who runs Stand With Crypto, the advocacy arm Coinbase launched in 2023, talked about endorsements and turnout: 45 candidates endorsed this cycle, “thousands or tens of thousands” of advocates mobilized per district. Read the six quotes side by side and one pattern emerges. Every speaker is describing a system they must join rather than a rule that applies to them. Selig’s new entrants opt in. Teng’s engineers absorb an intrusion and rebuild. VanGrack and Lynaugh lobby, endorse, mobilize. None of them describes waiting for a regulator’s order. In US crypto compliance, 2026’s verb of choice is volunteer. The pattern has a counterweight, and it came from the companies themselves. When Utah filed 14 criminal charges against prediction market Kalshi and its two top executives on October 28, including 12 counts of illegally promoting online gambling, Kalshi called the prosecution a “crazy overreach” and added: “We look forward to putting a stop to this in court, just like we did in Arizona.” A firm that won its Arizona criminal case in federal court in May is still being criminally charged by a second state in October. Volunteering for one regulator has not ended the argument with the other fifty. Condition one: the liability shift nobody legislated The first condition behind the operators’ year is financial. When the October 29 hack hit Binance, no statute, no insurance pool and no deposit guarantee determined who bore the $6.34 billion loss. The company decided. It pledged to cover all customer losses, tapped its own reserves, and by November 3 reported that it had replenished 98 percent of affected assets, with industry partners including Tether, Circle and Ripple freezing roughly $3 billion in suspected stolen funds. Coinbase, a competitor, blocked transfers to the compromised wallets and offered direct assistance. North Korea-linked hackers tied to the TraderTraitor group remain the FBI’s attribution, though Teng himself declined to make it. Nothing in the new federal framework required any of that. The CFTC’s October notice addresses transaction rules and market abuse for commodity trading; it does not create a recovery mechanism for a stolen-wallet event. The GENIUS Act, signed in July 2025, set the first federal framework for stablecoins; it did not touch exchange custody either. The gap between “regulated” and “made whole” is filled by a decision each exchange makes alone, funded from its own treasury. Binance’s CFO was the person on the hook for explaining that decision, and eight days after the loss was disclosed, the seat was vacant. Operators in smaller firms read that event as precedent, and not the reassuring kind. Covering losses voluntarily is a balance-sheet commitment that scales with your user base rather than your revenue. A mid-sized exchange that suffers the same social-engineering breach cannot replenish assets at Binance’s pace. The security report’s own detail makes the threat general: the entry vector was a search engine, a fake developer tool and a job interview. No capital requirement in any rulebook screens for that. Condition two: the map that keeps being redrawn The second condition is jurisdictional. The same firms opting into the CFTC’s framework remain exposed to an unfinished war between federal and state authority, and 2026 kept moving the lines. The scoreboard, in sequence: in March, Arizona became the first state to file criminal charges against Kalshi, and a federal judge permanently blocked the case that May. In April, the Third Circuit Court of Appeals ruled that New Jersey could not regulate Kalshi’s prediction market because the CFTC holds exclusive authority. On August 28 and September 25, two other federal appeals courts ruled against Kalshi and Polymarket’s bids to escape state-level oversight, handing states wins. New Jersey petitioned the Supreme Court on September 2. The CFTC has sued several states, including Arizona, Connecticut and Illinois, to defend what Selig calls exclusive jurisdiction over event contracts. Then came Utah’s criminal charges in late October, aimed at the CEO and COO personally. Table 1: Federal vs. state rulings touching prediction markets in 2026, in order Date (2026) Action Forum Outcome March Arizona files criminal charges against Kalshi State court Federal judge blocked the case in May April New Jersey barred from regulating Kalshi Third Circuit CFTC exclusive jurisdiction upheld August 28 States win appeal vs. Polymarket Federal appeals court State oversight allowed September 2 New Jersey petitions Supreme Court SCOTUS docket Pending September 25 States win second appeal vs. Kalshi Federal appeals court State oversight allowed October 28 Utah files 14 criminal charges incl. CEO, COO State court Kalshi calls it overreach, will contest Source: The Verge , October 30, 2026, citing Utah attorney general filings and prior rulings Selig told CNBC he will take the fight “up to the Supreme Court if that’s where it’s going” and said he will not “allow for states to go bring lawsuits against our exchanges, claiming that they’re unlicensed gambling.” That is the chairman of the opt-in framework conceding that his framework’s coverage map is contested. An operator who registers with the CFTC in November does not know which state’s attorney general shows up in the docket next February, or whether the appeals courts that split in 2026 stay split. The two conditions compound. Liability without a federal backstop means the firm’s own reserves absorb user losses. Fragmented jurisdiction means the firm’s registration does not travel. A compliance officer managing both at once is building on one leg and standing on the other, and 2026 supplied no statute that addressed either. Answering the single-cause test Could either condition alone explain the operators’ year? Test each against the record. Take fragmentation alone. If the only problem were the 50-state map, the CFTC’s October framework would have closed the year on a high note, and it did produce genuine demand; Selig says new entrants are “lining up.” But Binance was already a registered derivatives platform with US-facing compliance infrastructure, and it was still the one that lost $6.3 billion to a phishing campaign that started with a search engine. Regulation did not fail there, because the failure happened in a layer no regulator examines: one engineer’s laptop and a tampered installer. Jurisdictional clarity and operational security are different failure surfaces, and 2026 proved they break independently. Take liability alone. If the only problem were self-funded loss coverage, the solution would be insurance, and insurance exists; the reason it did not absorb this event is precisely that no rulebook defines the coverage trigger, the shortfall procedure or the disclosure clock, because those questions sit in the stalled statute. The Clarity Act’s September collapse and the CFTC’s October stopgap are the same event seen from the Senate and the agency. Without the statute, the liability question has no default answer, so every exchange answers it alone. Two conditions, then, and they interact: the missing statute is the reason liability defaults to reserves, and the contested jurisdiction map is the reason registration does not finish the job. If either condition alone were sufficient, the year would have closed differently: registration would have prevented the loss, or an insurance pool would have absorbed it. It closed differently under neither. Remove either and the operators’ 2026 looks different. Keep both and you get the year the quotes describe. Who never sees this link The people at the other end of the pipeline do not perceive either condition. The Gallup poll released in September found a record 89 percent of US adults say government corruption is widespread, and the CNBC All-America Economic Survey this month found only 20 percent rate the economy as excellent or good. The voter’s frame is affordability, not jurisdiction. When Representative Steven Horsford of Nevada, one of the Democrats Fairshake funded, described his town halls to CNBC, the crypto question arrived sideways: small businesses ask whether they should accept digital asset payments, “They’re being asked more and more by their consumers whether or not they take those payments for services and goods.” The customer sees a payment option. The merchant sees a question about accounting. Neither sees the reserve decision or the appeals court split standing behind it. Regulators see a slice. Selig’s framework addresses commodity transaction rules; state attorneys general see gambling; the SEC’s older enforcement legacy lingers in the background; the FBI sees the laundering. Each is correct within its slice, and the operator’s job is to hold all the slices at once, because the loss lands on the firm regardless of which slice was looking. That invisibility has a cost. Users of a covered exchange assume coverage is structural, the way deposit insurance is structural, because the last hack ended with 98 percent replenishment and no visible shortfall. The first mid-sized exchange that cannot replenish will teach the difference, and the lesson will arrive through the users’ balances rather than the Federal Register. What the rulebook was never going to fix The opt-in framework is real, and the demand for it is real. It answers one question: which federal agency holds the pen. It does not answer who pays when the pen’s licensees are breached, or which court’s definition of gambling binds a federally regulated platform. Those answers were in the bill that died on September 15, and if Cuomo’s reading holds, the next attempt starts from scratch in 2027. The operators who spent $200 million to hurry the process will spend 2027 doing the two jobs the statute was supposed to merge: funding their own worst day, and filing their own defense of jurisdiction, one state at a time. Sourcing Data as of November 2026. Every quotation in this piece comes from public, on-the-record sources: CNBC’s exclusive interview with CFTC Chairman Michael Selig (November 13, 2026), CNBC’s interview with Binance co-CEO Richard Teng (November 3, 2026), CNBC’s midterm spending report (October 31, 2026) with direct quotes from Ryan VanGrack, Stu Alderoty, Mason Lynaugh, Andrew Cuomo and Representative Steven Horsford, and The Verge’s report on Utah’s criminal charges (October 30, 2026), which quotes Kalshi’s statement to the Associated Press. Binance’s 98 percent replenishment figure, the intrusion timeline and the $3 billion freeze come from the company’s security report and Teng’s interview as reported by CNBC. Political spending figures carry Public Citizen and OpenSecrets attribution as reported by CNBC. No unnamed sources were used. What these sources do not disclose is any audited breakdown of the replenished reserves, and none of the filings publishes a per-project energization date. Where a figure depends on a company’s own accounting, such as the replenishment percentage, the text says so rather than treating it as an audited number. Ethics note This article examines named companies and named officials using only their public statements and published filings. It makes no accusation against any individual beyond what charging documents and courts have already put on the record, and it repeats the companies’ own denials and characterizations where they exist, including Kalshi’s response to the Utah charges and Teng’s refusal to attribute the hack. The FBI’s attribution to North Korea-linked actors is reported as an FBI position, not as an independent finding. The replenishment and asset-freeze figures are company-reported and unaudited; readers should weight them accordingly. Sources CNBC , “CFTC Chair Selig tells CNBC crypto industry is embracing agency rules as legislation hopes fade,” November 13, 2026 CNBC , “Binance co-CEO Teng says hackers used fake job interviews, AI tool to steal $6.3 billion in crypto,” November 3, 2026 CNBC , “Crypto industry pours more than $200 million into 2026 midterms,” October 31, 2026 The Verge , “Utah charges Kalshi and its CEO with illegally promoting online gambling,” October 30, 2026 TechCrunch , “Binance CFO is leaving to ‘pursue a new venture’ after $6.3 billion hack,” November 7, 2026 About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
Three Clearance Paths for Small Parcels After the Freeze SeaPRwire

Three Clearance Paths for Small Parcels After the Freeze

The USD 800 duty-free threshold for parcels entering the United States is gone in practice now and gone in law from 1 July 2027. Customs and Border Protection published interim final rules on 24 June 2026 that made the suspension of the de minimis exemption indefinite, for both postal and non-postal shipments, removing the expectation that the exemption would simply lapse back into effect. A October 2026 rule then narrowed who can still use the simplified mail entry process. What remains is a fee structure that punishes parcel-by-parcel filing: a USD 150 shipment entered alone now carries at least USD 34.58 in merchandise processing fees, the same floor it would pay if it were a container load. How the exemption ended, in sequence Four dates tell the story. Executive Order 14256 of 2 May 2025 suspended duty-free de minimis treatment for goods of Chinese and Hong Kong origin. Executive Order 14324 of 29 August 2025 extended the suspension to every country of origin, which is the point where the exemption stopped functioning as a commercial strategy for anyone. The One Big Beautiful Bill Act, signed 4 July 2025, repealed the commercial de minimis provision in statute, effective 1 July 2027, so the administrative suspension becomes a legal repeal on that date. Finally, the 24 June 2026 interim final rules wrote the suspension into CBP regulations without an end date. A court ruling along the way changed less than expected. The Supreme Court’s 20 February 2026 decision ended the IEEPA tariff program, and Executive Order 14388 followed, but the de minimis suspension was expressly continued. Teams that planned around a court case restoring duty-free parcels lost that assumption in February. What filing looks like now Every commercial shipment valued at USD 800 or less that once qualified for Section 321 treatment now moves through formal or informal entry. The suspension reaches every transport mode, including the international postal network, and it took effect on the date of publication in the Federal Register for both non-postal and postal shipments. Informal entry is generally available for shipments up to USD 2,500, subject to eligibility. Formal entry is required above that line and for specific merchandise classes, including goods subject to antidumping or countervailing duties. Mail shipments have their own track. The new mail informal entry process, effective 24 July 2026, covers mailed goods up to USD 2,500 that qualify for informal entry. Filing is manual: a spreadsheet with the filer code, bond number, duty owed, merchandise description, carrier, country of origin, the 10-digit tariff classification, the S-10 postal tracking barcode, and arrival details, submitted to CBP by email no later than the seventh day of the month following arrival. Entry can only be made by the owner or purchaser of the goods, or a licensed customs broker they designate. The October rule trimmed that track. Effective 22 October 2026, four categories are excluded from mail informal entry eligibility: merchandise claiming duty-free treatment under Chapter 98 of the tariff schedule, merchandise subject to Chapter 98 or Chapter 99 duties, merchandise claiming free trade agreement treatment, and goods subject to partner government agency requirements. Those shipments move through other entry types. An extended compliance date of 20 January 2027 gives filers a runway for the formal entry requirement on certain mail shipments, including those carrying Chapter 99 duties. Entry Type 86, the electronic filing built specifically for Section 321 volumes, no longer exists. Importers whose process documentation says “we file Type 86” need to re-map that workflow to the entry types that remain. The arithmetic that decides the model The duty is only part of the cost. The merchandise processing fee on a formal entry is 0.3464 percent of customs value, with a floor of USD 34.58 for fiscal year 2027, re-indexed each October. That floor is what breaks the one-parcel-one-entry model. One hundred separate USD 150 orders, each entered individually, hit the fee floor one hundred times: about USD 3,458 in processing fees on USD 15,000 of goods, before any duty. The same USD 15,000 consolidated into a single entry pays the percentage instead, about USD 52. The difference is roughly sixty-fold, decided entirely by how many entries the goods generate. Ocean freight adds the harbor maintenance fee, 0.125 percent of customs value with no cap. This is why consolidation, not duty rates, is now the first lever for small parcels. The duty depends on tariff classification and any additional programs stacked on top; the fee structure depends only on how many entries are filed. Path 1: consolidate inbound, fulfil domestically The first path brings inventory across the border as one bulk entry and holds it in the United States, fulfilling orders domestically from local stock. Duty and fees are paid once, on one entry, and the border cost converts into a storage cost. Delivery times shorten, which is often the reason brands stay on this path after trying it for the fee savings. The trade-offs are forecast risk, because the goods are committed to the US market before demand is known, and inventory carrying costs that did not exist when each order shipped on demand from overseas. Path 2: bonded warehousing for cash timing The second path addresses timing rather than total cost. Goods sit in a bonded warehouse under customs control, and duty is deferred until each portion is withdrawn for consumption. For businesses with uncertain sell-through, this limits duty exposure to what actually moves. The mechanics cost money: warehouse handling fees, withdrawal filings per release. The model suits goods with volatile demand or seasonal spikes, where paying full duty up front on a bulk entry would strand cash in slow-moving stock. Path 3: keep the parcel model where it still fits Parcel-by-parcel entries still work for some cases. High-value small orders, demand testing in a new market without US stock, and product lines where the per-parcel duty is trivial relative to the product price can justify the per-entry fees and the per-parcel clearance charges carriers and brokers levy. The operational risk in this path is repetition: a classification or valuation error replicated across thousands of entries is a far larger exposure than the same error in one consolidated filing, and the return logistics run cross-border in both directions. Two carve-outs survive untouched. Bona fide gifts and personal or household articles accompanying travellers keep their separate exemptions under 19 U.S.C. 1321, unchanged by any of the 2025 or 2026 actions. Neither helps a business selling goods, and neither covers commercial returns, so the carve-outs matter for personal shipments and traveller luggage rather than any fulfilment model. What to verify before switching paths Three checks come before any model change. The first is tariff classification: the duty rate and every stacked program attach to the 10-digit classification, so a wrong code poisons the landed-cost math for all three paths. The second is program stacking, since some origin countries carry additional duty layers that apply per shipment regardless of entry type. The third is the broker’s fee schedule for informal entries, because the per-entry service charge varies widely and, on low-value shipments, can exceed the fee floor itself. Importers running the numbers for fiscal 2027 should use the USD 34.58 floor, not the prior year’s figure, since the re-index took effect in October. None of the three paths restores the old economics. What they change is how much of the cost arrives as fees, when the duty is paid, and how much inventory risk the importer carries. The repeal in law on 1 July 2027 removes any remaining plan built on waiting out the suspension. Sources Sources: U.S. Customs and Border Protection, “E-Commerce Frequently Asked Questions” (de minimis suspension, entry types, mail informal entry, exclusions effective 2026-10-22, extended compliance date 2027-01-20). https://www.cbp.gov/trade/basic-import-export/e-commerce/faqs Public Law 119-21 (One Big Beautiful Bill Act), Section 70531, statutory repeal of commercial de minimis effective 2027-07-01. Finetex Global, “De Minimis Reform: What It Means for Small Apparel Importers,” dates and rules checked on US government sources on 2026-11-11. https://www.finetexglobal.com/de-minimis-reform-what-it-means-for-small-apparel-importers Long Road Warehouse, “Is Section 321 Still in Effect? De Minimis in 2026” (MPF floor, consolidation arithmetic). https://www.longroadwarehouse.com/blog/article/section-321-de-minimis-status Executive Orders 14256 (2025-05-02) and 14324 (2025-08-29); Executive Order 14388 (2026-02-20, suspension continued after IEEPA ruling). This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
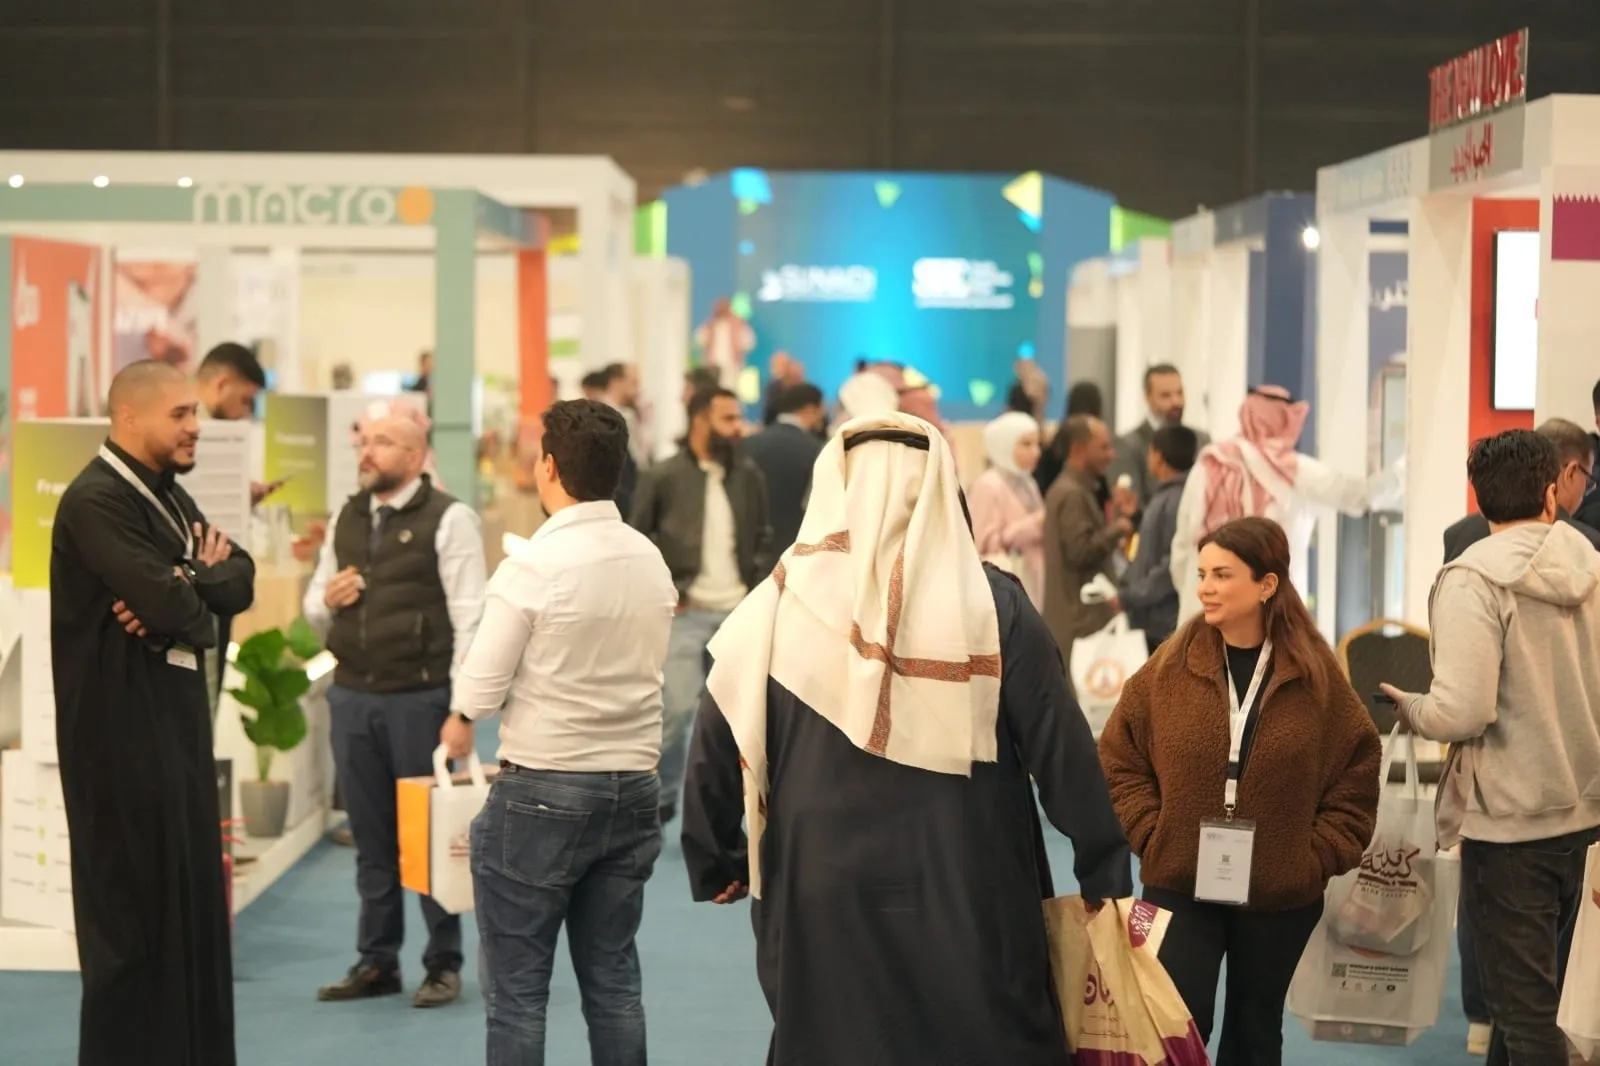
Riyadh and Jeddah Split the Saudi Trade Show Calendar SeaPRwire

Riyadh and Jeddah Split the Saudi Trade Show Calendar

The 20th Jeddah International Motor Show closed on 7 November after four days at the Jeddah International Exhibition and Convention Center. On 23-25 November the same city hosts the Saudi Franchise Expo and the Jeddah edition of the Foodex Saudi food and beverage show in the same week. Riyadh’s Foodex edition opens first, 16-18 November, and the franchise expo’s Riyadh edition follows on 26-28 January 2027 at The Arena. Saudi Arabia’s exhibition calendar has settled into a two-city rhythm, and the November wave shows how the split now works in practice. The calendar as it reads this month Four events anchor the season. The Jeddah motor show ran 4-7 November at the Jeddah International Exhibition and Convention Center, marking its twentieth edition with internal-combustion, hybrid, electric and extended-range vehicles on the same floor, test drives on open roads, and regional debuts of new models. Foodex Saudi, the food and beverage show organised by Reed Sunaidi Exhibitions, part of RX, runs its Riyadh edition 16-18 November and its Jeddah edition 23-25 November, one week later. The Saudi Franchise Expo occupies the same Jeddah dates, 23-25 November, at the Jeddah Center for Exhibitions and Events, with evening opening hours from 4:00 to 11:00 PM. Its Riyadh edition is scheduled for 26-28 January 2027, also at The Arena. The pattern is visible in the sequencing. Two organisers are running paired editions across the two cities within a single season, one starting in Jeddah and moving to Riyadh, the other starting in Riyadh and following a week later in Jeddah. Neither organiser is running both cities simultaneously. One organiser group, two cities, staggered editions The franchise expo and Foodex Saudi sit on the same organiser family: Sunaidi Expo organises the franchise show directly, and Reed Sunaidi Exhibitions, the joint venture with RX, runs Foodex. For the franchise expo, the official site lists the Jeddah edition first with 179 international, regional and local brands across 7,000 square metres, and the Riyadh edition three months later in a different venue. For Foodex, the Riyadh edition comes first and Jeddah follows a week later. The same production machinery serves both markets, with the edition order flipped between the two shows. The staggered structure has a practical consequence for exhibitors. A brand exhibiting in both editions of either show builds one stand production and ships it between cities, but needs two teams, two build-up windows and two sets of local logistics. The three-month gap between the franchise expo’s Jeddah and Riyadh editions is wide enough to rebuild or retheme the stand; the one-week gap between Foodex editions is not, so the Riyadh build comes down and goes back up almost immediately. Who walks the floor in each city The buyer structures differ by show type as much as by city. The franchise expo’s own figures, published on its site, report 465 or more agreements signed to date across editions, a 68-to-32 split between trade and general visitors, and satisfaction figures above 97 percent. The same page cites a Saudi franchise market valued at USD 15 billion with more than 15,000 franchise branches and 27 percent annual growth in the non-oil sector, figures attributed to the Ministry of Commerce and Investment and the Riyadh Chamber. The visitor profile list runs from food and beverage through retail, education, IT and business services, which is the audience shape of an investment-seeking show rather than a pure sourcing show. The franchise expo’s on-site programme explains part of that audience shape. The official site lists a business matchmaking service that pre-schedules meetings pairing brands with vetted investors, alongside workshops and panel discussions on franchising, financing and operations led by practitioners. The 465-plus agreements figure is presented as a cumulative result of that matchmaking machinery across editions, which positions the show closer to a deal room than a catalogue floor. Exhibitors attending for lead generation rather than brand exposure compete for meeting slots as much as for floor position, and the matchmaking allocation is an organiser decision that does not automatically follow stand size. Foodex Saudi’s trade listings report the last Riyadh edition at 12,800 square metres with 229 exhibitors and 11,500 visitors, drawn from commodity chains spanning Europe, South America, Africa and Asia. Entry runs on real-name online pre-registration verified against passports, with badge collection on site, per the trade listings’ visitor-process notes. The motor show, by contrast, is the consumer-heavy event of the three: its programme of public test drives, virtual reality experiences and a hackathon is built to draw end buyers as well as trade visitors, and its vehicle mix, covering internal-combustion, hybrid, battery-electric and extended-range powertrains on one floor, is framed around a regional market where alternative-energy vehicles are gaining share. The Jeddah clustering on 23-25 November puts a food sourcing show and a franchise investment show in the same city in the same week. For regional buyers flying in for one, the second show is a same-trip addition, and for local visitors the evening hours at the franchise expo make same-day attendance at both feasible. Riyadh’s editions sit apart, which spreads the season’s demand across two venues and two months. What the split means for exhibiting costs Venue and format choices feed directly into budgets. The franchise expo’s 7,000-square-metre footprint with 179 brands implies a larger average share of floor per exhibitor than a 500-brand food show of similar size, and its 4:00-11:00 PM schedule shifts staffing into evening shifts, which changes crewing quotes in a market where evening event labour prices differently from daytime. Build-up for Foodex closed on 15 November, the day before opening, per the show’s published timeline, leaving no slack between build and open. The same listing’s stand production timeline works backwards from opening day: builders should be briefed around 16 weeks before opening, which for the Riyadh edition meant late July 2026, a deadline the listing marks as already passed for late entrants. Lead times compound across the double-edition play. A brand booking the January 2027 Riyadh franchise edition faces a build window that overlaps the Gulf’s peak exhibition season, when stand contractors, freight forwarders and hotels are simultaneously serving the winter calendar. Exhibitors who treat the second edition as a repeat of the first, with the same contractor, the same drawings and the same local crew, typically negotiate the package as one engagement; exhibitors who book the two editions separately pay two mobilisation charges for what is materially one production. The two-venue structure also means exhibitors quote against different venue service packages in each city. Riyadh’s Arena and Jeddah’s exhibition centers have different in-house catering rules, which matters for a food show where sampling drives stand traffic. Exhibitors running the double-edition play typically request the same stand position pattern in both cities to reuse floor plans. What to confirm before committing Two details need organiser confirmation rather than listing trust. The first is venue naming for Foodex’s Riyadh edition: trade listings disagree, with some placing the show at The Arena Riyadh and others at the Riyadh International Convention and Exhibition Center on King Abdullah Road. The discrepancy matters for freight routing and hotel bookings, and the organiser’s own exhibitor manual is the binding reference. The second is the calendar itself: the January 2027 franchise expo dates in Riyadh are published on the official site, but the food show’s 2027 editions and the motor show’s next edition were not yet listed at the time of writing, so exhibitors planning a two-city season should hold dates loosely until the organiser confirms. Saudi Arabia’s exhibition market has grown into a two-circuit structure because the demand supports it: a capital-city market with government-adjacent and investment-seeking buyers, and a Red Sea port city whose shows pull regional trade visitors. The November calendar is the first season where the split shows up as paired editions from the same organiser group in the same month, and the January franchise dates confirm it was a plan rather than a scheduling accident. Sources Sources: Saudi Franchise Expo, official organiser website (Jeddah edition 2026-11-23/25 at Jeddah Center for Exhibitions and Events; Riyadh edition 2027-01-26/28 at The Arena; 179 brands, 7,000 sqm, 465+ agreements, 68/32 visitor split; market figures attributed to Ministry of Commerce and Investment and Riyadh Chamber). https://www.saudifranchiseexpo.com/ StandsZone, “Foodex Saudi 2026” listing (Riyadh edition 2026-11-16/18, organiser Reed Sunaidi Exhibitions, part of RX, build-up timeline). https://www.standszone.com/trade-shows/foodex-saudi-expo SaudiCon, “2026 Jeddah International Motor Show opens 20th edition,” reporting the Saudi Auto platform (2026-11-04/07, Jeddah International Exhibition and Convention Center). https://saudicon.app/zh/news/jeddah-international-motor-show-2026-opens-its-20th-edition-with-globa-8c888099 Jufair exhibition listing, Foodex Saudi (last Riyadh edition 12,800 sqm, 229 exhibitors, 11,500 visitors; venue naming discrepancy noted). https://en.jufair.com/exhibition/14641.html Qiyetang exhibition listing, Foodex Saudi two-city dates (Riyadh 2026-11-16/18, Jeddah 2026-11-23/25). https://www.qiyetang.com/g87943820.html This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
EU Ad Repository Guidelines Move: What Sellers Should Track SeaPRwire

EU Ad Repository Guidelines Move: What Sellers Should Track

The European Commission opened a call for evidence on 4 November 2026 on how the advertising repositories of very large online platforms should be designed. Responses close on 2 December, a targeted consultation on a draft text is planned for 2027, and final guidelines are targeted for the second quarter of 2028. The obligation the guidelines will shape is already live: Article 39 of the Digital Services Act requires very large platforms and search engines to maintain public, searchable archives of the advertisements they display, and the Commission has already fined one operator EUR 45 million for running a repository that fell short. Sellers and advertisers whose campaigns run on those platforms have two dates in view and a metadata audit worth starting now. What Article 39 already demands Each repository entry must record the advertisement’s content, the person or organisation on whose behalf it appeared, who paid for it where that differs, the period during which it ran, whether it was aimed at particular groups and the main targeting criteria used, including exclusions, and the number of users reached, broken down by member state. The archives must be publicly accessible and searchable, accessible through an API, retained for at least twelve months after the advertisement’s last display, and free of personal data about the people who received the ads. Article 26 adds the real-time layer: at the moment an advertisement is shown, it must be identifiable as advertising, with the presenter, the payer and the main targeting parameters disclosed to the viewer. The repository is the retrospective record; the on-ad disclosure is the point-of-view obligation. Platforms are expected to satisfy both, and the public consultation on repository design addresses only the archive side. Why the Commission is writing guidelines now The archive obligation has produced enforcement action. The Commission’s own policy page records a EUR 45 million fine against the provider of X for a non-compliant advertising repository, and describes commitments from other very large platforms to bring their repositories into line, with the Commission stating it will take action where agreement on compliance cannot be reached. Sixteen DSA proceedings have been opened across the supervision programme to date, covering content moderation, minor protection and advertising among other files. The quality problem is the stated motivation. Early repositories vary widely in how well they can be searched, how completely they expose targeting criteria and reach, and whether the ad content itself remains accessible. The Commission frames better archives as enforcement infrastructure: researchers, journalists and national Digital Services Coordinators use the data to detect scams, disinformation campaigns, misleading commercial practices and illegal product promotion, and a common technical standard would give regulators a baseline against which to measure each platform’s archive. The policy page ties the same transparency programme to protecting public health, ensuring consumer protection and safeguarding the integrity of elections, which places commercial advertising archives inside a supervision framework built for wider harms. The consultation documents list three areas the guidelines will address: how easily the data can be searched, how much insight the archives give into targeting and reach, and how accessible the ad content is. Each maps to a complaint researchers have raised about the first two years of archive operation. The Commission is collecting input from researchers, civil society organisations, journalists, the platforms themselves and advertising industry representatives, and reporting around the consultation notes that regulators have already questioned platforms on financial scams and misleading promotions, where a stronger, standardised evidence base would help national Digital Services Coordinators build cases against a common benchmark. The timeline, and what it does and does not change The sequence runs: call for evidence until 2 December 2026, targeted public consultation on a draft text in 2027, final guidelines in the second quarter of 2028. Under Article 39(3), the Commission issues the guidelines after consulting the European Board for Digital Services, researchers and the public. The long runway has a practical consequence: platforms keep operating their archives under their own reading of the rules until the guidelines land. Nothing in the consultation changes the fields each entry must carry, the twelve-month retention, the API requirement or the searchability duty; those are in the regulation text. What the guidelines will settle is the technical standard for each, which affects how machine-readable the archives become and how reproducible third-party research on them is. The move fits a broader advertising-transparency agenda. On 12 October 2026 the EU launched a pilot repository programme for online political advertising, built on the same premise that public, queryable archives let outsiders verify who paid for what. What sellers and advertisers should audit now For advertisers, the archive regime changes the privacy of campaign strategy. Targeting criteria, exclusions and reach figures for every ad on a very large platform sit in a public database that competitors can query. An audit of ad account metadata is the practical first step: confirming that the payer field reflects the real paying entity, that targeting parameters recorded by the platform match the campaign’s intended design, and that nothing in the recorded criteria is commercially sensitive enough to warrant restructuring the campaign’s group definitions. Once the guidelines standardise these fields, discrepancies between what a brand intended and what the archive records become visible to anyone who looks. Marketplace sellers face a separate set of DSA duties that operate alongside the archive regime. Providers of online marketplaces must verify traders’ identity before those traders can sell, and must let consumers identify the trader behind an offer. When a platform becomes aware that a seller offered an illegal product, it must inform affected buyers, identify the seller and offer redress options, and several marketplaces now maintain EU-specific recall pages listing products notified in the previous six months. Sellers whose account documentation lags their corporate reality, after a rename, a restructure or a change of legal entity, generate exactly the mismatches this machinery surfaces, and the verification happens before the next listing, not after. Two preparation items track the consultation directly. The first is participating in it: the Commission has framed the call for evidence as input from the people who use the data, and industry responses arguing for search-by-advertiser and structured targeting fields would shape the 2027 draft. The second is API readiness: brands and agencies that monitor competitor advertising, verify compliance or run research will need to work against whatever machine-readable standard the guidelines set, and building internal tooling against a platform’s current idiosyncratic archive format risks rework after 2028. The grey areas Business confidentiality is the friction point the consultation names without resolving. Detailed targeting records expose how campaigns reach audiences, and the guidelines will have to draw a line between transparency into advertising practices and exposure of commercial strategy. How that line lands is unresolved, and platforms’ current archives already differ in how much targeting detail they publish, so the effective disclosure level a seller experiences today depends on which platform carries the campaign. A second open question is search quality. The regulation requires searchable archives, but the consultation’s framing, better search as one of three priorities, implies the Commission considers current implementations inadequate. Until the guidelines define a floor, archive search that works by advertiser, by product and by date range cannot be assumed, and compliance checks that depend on it inherit that gap. Sellers tracking their own archived ads should test retrieval on each platform directly rather than assuming the archive answers a query it has no obligation, yet, to answer well. Sources Sources: Digital Watch Observatory, “European Commission seeks input regarding public ad repositories under DSA,” reporting the call for evidence published 2026-11-04, closing 2026-12-02, final guidelines targeted Q2 2028, and the political-ads pilot repository launched 2026-10-12. https://dig.watch/updates/eu-commission-seeks-input-on-public-ad-repository European Commission, “The impact of the Digital Services Act on digital platforms” (Article 39 regime, EUR 45 million fine against the provider of X, repository commitments, 16 proceedings). https://digital-strategy.ec.europa.eu/en/policies/dsa-impact-platforms European Commission, “How the Digital Services Act enhances transparency online” (transparency obligations framework). https://digital-strategy.ec.europa.eu/en/policies/dsa-brings-transparency Regulation (EU) 2022/2065 (Digital Services Act), Articles 26 and 39, EUR-Lex. The European Post, “Advertising Repositories Guidance Puts Platform Ads In View” (consultation scope and timetable). https://theeuropeanpost.eu/brussels-today/advertising-repositories-guidance-puts-platform-ads-in-view This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More