EUDR Filings: The Final Stretch to 30 December 2026 SeaPRwire

EUDR Filings: The Final Stretch to 30 December 2026

From 30 December 2026, customs will not release coffee, cocoa, timber, rubber, soya, cattle products or palm oil into free circulation in the European Union until a due diligence statement reference number sits in the declaration. The German enforcement act that fills in the domestic machinery reached the Bundestag on 30 September 2026, and on 12 November lawmakers deleted one of its clauses, stripping the power to delegate federal tasks to private entities. The filing obligations themselves come from the EU regulation and do not move with national drafts. Operators now have roughly six weeks to line up the data, the information system registration and the customs codes those filings ride on. Who files a statement, and who stopped The filing duty belongs to operators: companies that place a covered product on the EU market for the first time, or export it. The December 2025 revision, Regulation (EU) 2025/2650, created a new role downstream. A downstream operator, one that processes or resells goods already placed on the EU market, no longer files its own due diligence statement. Its duties are record-keeping: the names and contact details of suppliers and commercial customers, retained for at least five years, and, for the first buyer after an operator, the reference numbers attached to the goods. Companies in that role that are not small or medium enterprises must also register in the information system, even though they file nothing. The revision also moved the perimeter. If the first operator sits outside the EU, the first EU-based company that makes the product available on the market is treated as an operator and carries the full filing duty. Importers and distributors buying from non-EU suppliers need to check which role their contract puts them in before December, because the two roles diverge sharply in workload. Customs representatives sit outside both: the Commission’s FAQ states they never count as operators, and they declare their principal’s codes and reference numbers. What goes into the filing A due diligence statement carries the operator’s details, EORI number, tariff classification, product description and quantity, the country of production, and the geolocation of every plot of land where the commodity was produced. The regulation asks for latitude and longitude coordinates, with polygon data for plots above four hectares. Filing happens in the EU information system before the product is placed on the market, and the operator hands the resulting reference number to its first customer. There is a shorter route for the smallest producers. Micro and small primary producers established in low-risk countries, which include all EU member states, can file a one-time simplified declaration and receive an identification number that covers their products, instead of a statement per batch. In place of coordinates they may submit the postal address of the land or holding. The due diligence duty itself stays in force for them, including collecting information on origin, but the per-shipment paperwork collapses into a single registration. Risk assessment and risk mitigation only enter the picture when there is a non-negligible risk. For raw materials from low-risk countries, the simplified due diligence of Article 13 applies and those two steps drop out unless there is evidence of a breach. Only once risk is negligible or absent does the operator submit the statement, which is a sequencing point smaller teams sometimes miss: the statement is the last step of a due diligence system, not a form that starts one. The customs mechanics Release for free circulation is the step that triggers everything. Customs warehousing, inward processing, temporary admission and transit do not count as placing on the market, and the re-export of goods that never acquired Union goods status falls outside the regulation entirely. Before release for free circulation, or before export by an operator, the declaration must carry the statement’s reference number or the simplified declaration’s identification number. The tariff code table was updated for this. The Commission published revision 1 of its TARIC working document on 23 September 2026: code C717 now stands for the simplified declaration of micro and small primary producers, and new codes C720, Y188, Y196 cover re-imports and exports by downstream operators, each split between small and non-small companies. Code Y141, used by operators relying on the deferral to 30 June 2027, remains valid until 29 June 2027. Teams configuring ERP or broker filing systems should check their code tables against the September revision, because summer overviews describe some codes differently. One mechanical detail catches re-imports. A company bringing back products previously placed on the EU market states its supplier’s reference number in the declaration; if no number exists, the Commission issues a conventional reference number. And if the information system flags a product for a check, customs suspends release until the status clears. The dates that matter Large and medium-sized operators comply from 30 December 2026. Micro and small operators established before 31 December 2024 get six more months, to 30 June 2027, except in timber: micro and small operators already covered by the EU Timber Regulation comply from 30 December 2026 like everyone else. Companies established after 31 December 2024 get no deferral at all, regardless of size. Timber products already on the market before 30 December 2026 stay under the Timber Regulation until 31 December 2029. Product scope also shifted this autumn. Delegated Regulation (EU) 2026/2102, in force since 18 September 2026, took cattle hides, retreaded and used tyres, soya beans for sowing and certain aircraft and vehicle seats out of scope, and adds soluble coffee, some palm oil derivatives and a handful of other items from 30 December 2027. Any internal product matrix built on the old Annex I needs a re-check against the September text. Enforcement is still being written in Germany The EU regulation applies directly, but each member state supplies the penalties and the inspection machinery, and the German draft shows how much is still in motion. The draft implementing act entered the Bundestag on 30 September 2026 as printed paper 21/8278, naming the Federal Office for Agriculture and Food as the competent authority with the state authorities responsible for primary production and timber harvesting. Its sanction ladder runs from fines up to EUR 100,000 to prison terms of up to five years, and up to ten years for severe, lasting environmental damage; companies above certain turnover thresholds face fines calculated as a percentage of EU-wide turnover, up to 4 percent depending on the breach. The Bundesrat had asked in September for forest-owner relief to be written into the act itself: a postal address with a company number in place of coordinates, and bundled declarations through recognised forestry associations. The federal government answered with a general administrative regulation instead, submitted on 7 October 2026 as printed paper 577/26. Under it, timber that members of recognised forest owners’ associations market through their association is declared by the association as the operator, and the members file nothing of their own. The administrative regulation binds the authorities, not companies, so for importers and traders it changes nothing. On 12 November the Bundestag deleted the draft’s delegation clause, removing the Federal Office’s power to hand tasks to private legal entities. The act is not law until promulgated, and its sanction schedule remains open. The Commission, for its part, has confirmed the core EU text will not be reopened and there will be no third extension of the application date. The May 2026 simplification package was the last structural change. The grey areas worth checking before filing Three points generate most of the avoidable friction. First, size and age interact: a micro or small company set up after 31 December 2024 files on the large-company timetable, so a founding date on paper decides a compliance date. Second, role depends on transaction shape, not job title: the same company can be an operator for one product line and a downstream operator for another, and the first EU company in the chain when the operator is offshore carries the operator’s full duty. Third, the statement number has to reach the customs declaration and the first customer at the same time, which means the data pipeline, plot coordinates, supplier declarations, risk documentation, has to be finished before the first shipment of December, not in parallel with it. The geolocation work is the slowest piece and the one with no shortcut, apart from the narrow postal-address route for the smallest primary producers. Companies in commodity chains with many smallholder plots have the longest lead time, and for them the six remaining weeks are a data deadline, not a legal formality. Sources Sources: Polygon One, “EUDR current status: delay, latest news, deadlines and what applies when,” timeline updated through 2026-11-12. https://polygon-one.com/en/eudr-current-status EUR-Lex, Regulation (EU) 2025/2650 (targeted revision of Regulation (EU) 2023/1115). https://eur-lex.europa.eu/ EUR-Lex, Delegated Regulation (EU) 2026/2102 (amended Annex I, in force 2026-09-18). https://eur-lex.europa.eu/ European Commission, TARIC working document for Regulation (EU) 2023/1115, revision 1, 2026-09-23 (via Polygon One timeline). EcoSkills Academy, “EUDR: What Companies Need to Do Before the Deadline,” 2026-11. https://ecoskills.academy/eudr-compliance-guide-before-the-deadline Nicola Bernard, “EU Deforestation Regulation: Application from 30 December 2026,” citing DIHK and EUR-Lex C/2026/3896. https://nicola-bernard.de/en/eu-deforestation-regulation-application-from-30-december-2026 KPMG Law, “EUDR: These obligations apply throughout the supply chain, as of 2026.” https://kpmg-law.de/en/eudr-these-obligations-apply-throughout-the-supply-chain-as-of-2026/ Bundesrat printed paper 577/26 (general administrative regulation, 2026-10-07) and Bundestag printed paper 21/8278 (implementing act draft, 2026-09-30), via Polygon One legislative timeline. This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Autech Parking Solutions Rebrands to Expand Its Global Presence in Automated Parking SeaPRwire

Autech Parking Solutions Rebrands to Expand Its Global Presence in Automated Parking

Seoul, Korea – November 13, 2026 – (SeaPRwire) – Autech Parking Solutions, a South Korean provider of automated parking systems formerly known as Autech-Otis Parking Systems, has rebranded as part of its efforts to strengthen its position in the global parking solutions market. Founded in 1978, the company brings nearly five decades of experience in the automated parking industry. To date, Autech Parking Solutions has delivered over 150,000 parking spaces across more than 2,000 project sites, building an extensive track record in South Korea’s automated parking maintenance sector. The company also supplies automated parking systems to international clients in Israel, Vietnam, India, Indonesia, and China. Building on its experience in domestic and international markets, Autech Parking Solutions focuses on providing customized parking systems designed to accommodate challenging and non-standard spaces. Its product portfolio includes palletless fork-type and comb-type conveyor systems, which transfer vehicles without the need for pallets, as well as its XY (chess-type) parking system, designed to make efficient use of available space. These solutions can serve as alternatives for buildings with unconventional structural layouts or sites with significant space constraints. The company also offers acoustic solutions designed to reduce noise and vibration in automated parking facilities, helping improve comfort in residential buildings. In addition, it provides EV charging systems that can be integrated into automated parking infrastructure. As part of its ongoing development of parking automation technologies, Autech Parking Solutions is currently piloting a robotic parking system in South Korea. For more information about Autech Parking Solutions, please visit https://www.atps.co.kr/en/main/. Media Contact Company: AUTECH PARKING SOLUTIONS CO.LTD Contact: Overseas Business Division Email: SangHyun.Song@atps.co.kr Website: https://www.atps.co.kr/en/main/
More

2026年菲律宾电信资本开支冲上24.5亿美元,真正该盯的是钱没流向哪里

DICT口径:PLDT、Globe、Converge三家合计承诺22.1亿美元,DITO却在收缩,Konektadong Pinoy法案2月生效的注册规则正在重写最后一公里的入场券 2026年9月初,菲律宾信息与通信技术部(DICT)公布了一组带着里程碑气质的数字:全国三家最大的网络建设商当年合计承诺资本开支约22.1亿美元,加上DITO Telecommunity的预计投入后,总额将升至24亿至24.5亿美元。部长Henry Aguda把这解读为信心投票,跨过20亿美元大关,意味着行业相信这个国家。这话没错,但和多数官方表态一样说得不全。资本开支总额只是标题,不是预测。这轮投入能否真正改变市场,看的不是加总,而是构成,而构成正在朝两个方向同时移动:挑战者花的钱比去年少,一部2025年通过的法律则悄悄把网络的最后一公里,从特许经营权控制的资产,变成了任何合格公司都能注册去建的东西。 纸面上,在一个1.14亿人口的国家投24.5亿美元建电信网络,像是扩张周期的开场。实际决定这笔资金用途的是两个变量:DITO建设周期的走向,以及Konektadong Pinoy法案新框架下的注册速度。本文把两个变量拆开,核对公开数字到底能支撑什么结论,并列出判断出错时会出现的信号。 24.5亿美元到底买什么 DICT的口径基于截至2026年8月的公司披露和业绩说明会。三家运营商构成已确认部分: 运营商 2026年资本开支指引(比索口径) 美元折算 备注 PLDT Inc. 约550亿比索 约9.3亿美元 单笔最大承诺 Globe Telecom 低于594亿比索 9.5亿至9.7亿美元 封顶口径 Converge ICT 170亿至200亿比索 约3.1亿美元 按中值计 DITO Telecommunity 预计1.7亿至2.5亿美元 计入24亿至24.5亿区间 低于2025年水平 已确认合计(PLDT+Globe+Converge) 约22.1亿美元 截至2026年8月的披露 行业合计(含DITO等) 24亿至24.5亿美元 DICT估算 来源:Newsbytes.ph 🔗,报道DICT 2026年9月1日声明 引用这组数字前先做三点阅读提示。第一,22.1亿美元是指引,不是经审计的实际支出,DICT自己都注明这些数字“仍可能随运营商支出计划变化”。第二,美元折算用的是该部自己的汇率,公告没有同步公布;比索口径(550亿、594亿、170亿至200亿比索)才是更硬的数字。第三,DITO那份是预测而非承诺,这正是22.1亿与24.5亿之间的差额要紧的原因:如果DITO落在区间下沿,标题数字里约有1.9亿美元属于推断。 变量一:DITO在少花钱,而不是多花钱 DICT声明里最有信息量的一行是关于挑战者的。DITO Telecommunity,这家2021年入局、打破PLDT与Globe双寡头的第三家运营商,2026年预计投入1.7亿至2.5亿美元,低于2025年的150亿至180亿比索(按当时汇率约合2.6亿至3.1亿美元)。一家挑战者在入局第六年削减资本开支,不是细节,是阶段切换。 DITO的建设路径与其他有国资背景新进入者的市场并无二致:先重金砸铁塔和频谱以满足覆盖义务,再在用户增长必须开始自我造血时收手。2026年指引说明收手已经发生。由此推出两个后果,不需要看DITO内部账本也能成立。 第一个是竞争性的。停止扩张覆盖的挑战者,只能拿着一张固定的网络打价格战。短期利好消费者,中期会侵蚀所有人的每用户收入。PLDT和Globe正被要求以创纪录的水平投入,PLDT的550亿比索是其年度最大承诺,而一个不再需要靠持续资本开支支撑增长叙事的对手,恰恰有空间在价格上出手。纸面上行业在大力投资;实际上,挑战者资本开支假期之后的价格压力,吃掉的利润可能比省下的资本开支还多。 第二个是结构性的。DITO退场后,增量覆盖的重心移到政府自己的项目上:国家光纤骨干网推进,以及Konektadong Pinoy法案的加速落地。DICT声明把两者与运营商承诺并排列出,这不是修辞。当私人资本集中到密集且有利可图的走廊,不赚钱的边缘就只能靠国家骨干网和开放接入制度吸引来的新进入者。2026至2028年那些边缘地区能不能被覆盖,取决于这两个机制,而不是标题里那个总数。 变量二:最后一公里从特许经营变成注册制 Konektadong Pinoy法案(第12234号共和国法)2025年通过,实施细则于2025年11月出台。操作枢纽出现在2026年2月2日:国家电信委员会(NTC)签署第002-02-2026号备忘录通告,即数据传输行业参与者(DTIP)的注册与授权框架。框架的核心动作是废除数据传输的国会特许经营权要求:商业性传输数据的实体改为在NTC做行政注册,不再需要一部量身定制的法律。 通告把行业切为四个分段,每段设置各自的资产门槛,门槛的刻度刻意让小玩家能从边缘入场、核心环节保持资本密集: 分段 最低资产要求 证书有效期 国际网关设施(IGF) 10亿比索(约1600万美元) 最长15年 核心网/骨干网 1亿比索 最长15年 中间一公里 1000万比索 最长10年 最后一公里 50万比索(约8000美元) 5年 来源:eLegal Philippines 🔗,关于NTC第002-02-2026号备忘录通告 为最后一公里运营设50万比索的资产门槛,是刻意的政策选择:把社区网络、合作社和小ISP定价进市场。通告还为准微型实体和面向农村及未覆盖地区的社区网络开设“绿色通道”,要求所有获授权参与者执行网络安全标准、按年公开费率透明度报告,并在每年4月30日前向NTC和菲律宾竞争委员会提交年度报告,内容涵盖投资、覆盖、分分段网络地图与定价。注册者还须保持负债资产比不超过70%。 实际上,框架的第一年交出的是摩擦,不是洪流。DICT于2025年11月发布实施细则,NTC在2026年一季度启动存量牌照持有人的转换,要求公共电信实体申报自己占据哪些分段。到三季度,委员会仍在就是否把数据传输(DTIP监管)与旧的增值服务(VAS)制度之间的边界划在哪里征求意见。一位马尼拉律师事务所在梳理全年进展时说得直白:多数VAS业务本质上必然涉及数据传输,而NTC目前把互联网接入和VoIP划入DTIP框架、其余VAS留在旧制度,这条线至今没有划清。 所以第二个变量处于激活但未验证的状态。法律拆掉了特许权壁垒,注册门槛已经公布,转换时钟在走。尚未被证明的是数量:2月以来到底冒出了多少新的最后一公里注册者,其中有没有人在三巨头已覆盖的走廊之外动工。这个数字是当下菲律宾电信业信息量最大的单一统计,而它并不在DICT那份资本开支公告里。 实施细则里的其余杠杆 注册制是拿到头条的条款,但实施细则捆着几个直接影响2026年资本开支转化效率的机制。每一个作用在不同约束上,也各有各的失效方式。 强制基础设施共享。接入服务商与无源基础设施(铁塔、管道、光纤)的业者,必须以公平且不歧视的条件开放关键设施。目标是阻止重复建设、压低铺设的资本成本。失效方式是定价纠纷:在在位者掌握资产的地盘上,“公平”接入费怎么定,这正是细则要求公布参考接入报价(RAO)与接入清单、而不是让双方私下谈的原因。 “一次开挖”政策,要求道路施工时同步埋设管道。路已经挖开时埋光纤导管,是网络建设者能遇到的最低土建成本时刻。机制在纸面上便宜,完全依赖公共工程部门与电信侧的协调,细则只布置了任务,强制不了配合。 通过频谱管理政策框架改革频谱。框架须指导频率的分配、指配与收回,配套定期审查与竞争敏感的指配机制,并引入收回闲置频谱、改配给更高效使用者的机制。这是对在位者阴影最长的一条,因为“闲置”是在位者可以争辩却无法无视的判断。 投资财政激励,含免税期、关税豁免与增值税零税率,用于把私人资本拉向服务不足与未覆盖地区。 网络安全从最佳实践升格为持牌条件。注册者须实施公认框架(ISO/IEC 27001、NIST或CIS),建立事件响应流程,并向国家CERT报告重大事件。合规是持续经营的前提。 把这五条合起来看,规则试图从四个方向同时压低农村覆盖的成本:更便宜的土建、更便宜的基础设施接入、更便宜的频谱、更便宜的税。加总之后是否等于更便宜的农村网络,取决于细则只画了轮廓的实施细节。BusinessWorld的法律分析点出了显而易见的风险:参与度上升不会自动变成有效竞争,监管不够强的话,市场碎片化或在位者主导都会延续。同一篇分析还点名DICT、NTC与竞争委员会三者职能重叠,协调失败可能造成监管碎片化。 对这个框架第一年最诚实的概括因此是不对称的。降本杠杆已经生效、不需要新立法;一个挖一次路、租管道、领激励的新进入者马上就能把便宜兑现。创造竞争的杠杆,注册本身,也已生效但数量未验证。这种不对称正是值得盯注册数而非激励申领数的原因。 企业业务收入是更安静的证据 在位者为何愿意在挑战者收缩之际以创纪录水平投入,还有第三个不那么张扬的解释:需求结构从个人订阅转向了企业数据。PLDT 2026年上半年业绩给出了信号。企业业务收入达248亿比索,其中企业数据与ICT服务贡献184亿比索,PLDT Global的收入同比增长30%,公司正扩大其在区域互联中的角色。这种形状的增长不靠家庭宽带套餐驱动,它跟着数据中心流量、云互联以及DICT自己点名的AI建设走。 PLDT指标(2026年上半年) 数值 企业业务收入 248亿比索 企业数据与ICT收入 184亿比索 PLDT Global收入同比增长 30% 来源:PLDT披露数据;2026年资本开支背景见 Light Reading 🔗 企业业务的倾斜也解释了那个受关注最少的国际基础设施条目:一项5亿美元的国内海底电缆提案,开工后预计24个月建成。对群岛国家来说海底电缆听起来是国际项目,直到需求结构摆出来才明白,吕宋、米沙鄢与棉兰老岛数据中心之间的岛际企业回传,恰恰是消费端指标永远照不亮的瓶颈。24个月的建设时钟意味着2026年做的决定在2028年落地,这使今年的资本开支指引数字对AI与数据中心需求真正到来时的网络形态,预测力相当有限。 这取决于你相信哪条收入线的增长是持久的。如果企业数据增长是持久的结构性轮动,在位者550亿比索以上的投入就是维护一台利润发动机的理性支出,标题里的24.5亿美元与其说是扩张,不如说是重新平台化。如果它是一个周期顶点,AI基础设施需求像其他市场那样退潮,同样的投入就成了产能搁浅风险,而DITO的谨慎反而像是对市场最锋利的读法。 谁先受冲击,按什么顺序 重构不会同时落到所有参与者头上。按机制而非体量排序: VAS服务商最先面临归类风险。DTIP与VAS的边界未定,意味着那些以为自己只受轻度监管的内容或平台服务商,可能一夜之间被注册为数据传输参与者,资产门槛、网络安全认证、年度报告一并挂上来。2026年三季度的征求意见流程将决定这张网撒多宽。 城市密集区的在位最后一公里运营商第二个暴露,前提是注册量真的起量。50万比索的门槛恰好在收入最肥的地段招人进场;在省级市场,绿色通道的社区网络路径才是现实的挑战者,而它的速度取决于拨款。 DITO自己的零售地位排第三,方向相反:一家冻结网络增长的挑战者,在对头收割企业需求的同时,要么需要打价格战(削减资本开支的动作暗示它有备而来),要么在走一条指引里没有透露的利基路线。 频谱持有人最后暴露,也最缓慢,路径是细则规定的频谱管理政策框架,含收回闲置频率并重新指配的机制。收回权在动用之前就会改变行为。 两个先行指标携带大部分信息。第一个是NTC按分段统计的注册数,理想情况按月公布:通告生效一年内最后一公里注册者哪怕过几十家,开放接入命题就得到验证;到2027年中还停留在个位数,则说明门槛不是真正的约束。第二个是DITO的2027年指引:再出现一个低于3亿美元的年份,就确认收缩是战略而非时点,所有在位者模型里默认的竞争烈度都得重新定价。 两种情形会让这个读法失效 任一变量反向运动,上述判断即告失效。如果DITO的2027年指引逆转,重回150亿比索以上的投入,无论出于新融资还是覆盖义务,“挑战者收缩”这条腿塌掉,资本开支构成的论证反向翻转为新一轮建设竞赛。如果NTC的DTIP注册表显示数百个活跃的最后一公里运营商正在服务三巨头放弃的区域,“摩擦而非洪流”这条腿塌掉,Konektadong Pinoy法案从脚注变成主角。两个数字都是公开的,或即将公开;不需要任何特殊渠道。谁引用24.5亿美元的标题而不带这两个数字,引用的只是里程碑,不是趋势。 数据基础 资本开支数字来自DICT 2026年9月1日声明,该声明汇总了截至2026年8月的公司披露与业绩说明会;同一声明经五份独立报道交叉核对(Newsbytes.ph、Telecom Review Asia、Communications Today、Developing Telecoms、Context.ph),所有数字一致。监管框架依据为第12234号共和国法、2025年11月的实施细则,以及2026年2月2日签署的NTC第002-02-2026号备忘录通告,另参考两份菲律宾法律实务分析。PLDT 2026年上半年企业业务数据与海底电缆提案,来自本项目电信指标数据集记录的行业报道。DITO的2025年支出区间是DICT自己的对比口径。未直接阅读运营商财务报表,全部数字为披露式报道的二手来源。 局限 美元折算沿用DICT口径,各报道间存在差异。DITO的2026年支出是预测而非披露。DTIP注册数,即本文的关键先行指标,成稿时尚不可得,因此基于注册表的论断是预测,不是发现。VAS边界走向取决于仍在征求意见的监管过程。 来源 ph🔗 — 菲律宾电信资本开支2026年预计达24.5亿美元,2026年9月1日 Telecom Review Asia🔗 — Philippine Telco Sector Lines Up USD 2.2B in 2026 CapEx,2026年9月 BusinessWorld Online🔗 — Konektadong Pinoy Act: Expanding access, redefining competition,2026年 eLegal Philippines🔗 — NTC为Konektadong Pinoy法案颁布新指引,2026年2月 asia🔗 — Philippine digital regulation: Connectivity, fintech developments,2026年10月22日 Light Reading🔗 — Philippine telcos set $2.2B for infrastructure investment in 2026,2026年 关于 Global Infinity Labs Global Infinity Labs是一家专注于MCP数据服务的AI创新公司。本文由Global Infinity Labs专家团队撰写,基于其MCP数据服务所提供的信息与数据进行分析。 联系邮箱:support@globalinfinitylabs.com
More
Dubai Chamber membership data shows where Chinese firms cluster SeaPRwire

Dubai Chamber membership data shows where Chinese firms cluster

On 5 November 2026, Dubai Chambers signed a memorandum of understanding with the Jiangsu Chamber of International Commerce, extending a province-level cooperation framework to one of the largest manufacturing regions in China. The agreement matters less as a single signing than as a data point in a measurable pattern: more than 6,650 Chinese companies were active members of Dubai Chamber of Commerce by the end of September 2026, more than three times the 2016 count, and Dubai-China non-oil trade reached roughly AED363.5 billion (USD98.9 billion) in 2025, up 118.4 percent from AED166.4 billion in 2016. Behind those headline figures sits a membership structure with its own industry distribution, fee schedule and processing timeline, and those operational details are what a market-entry plan actually uses. What the Jiangsu agreement actually sets up The memorandum was signed at Dubai Chambers’ headquarters by Mohammad Ali Rashed Lootah, President and CEO of Dubai Chambers, and Wang Shanhua, Chairman of the Jiangsu Chamber of International Commerce. Its framework covers three cooperation channels: business delegations in both directions, market-entry assistance for companies establishing operations, and B2B matchmaking between the two business communities. The two chambers also committed to explore joint participation in business events and jointly organized trade activities. The province focus is specific rather than symbolic. The agreement is designed to help companies from Jiangsu, particularly those based in Yancheng, establish and expand in Dubai, while supporting Dubai-based businesses exploring commercial opportunities across the province. It builds on earlier groundwork: in May 2026, the chambers held discussions with the China Council for the Promotion of International Trade Jiangsu Sub-Council on deepening trade and investment cooperation. For companies watching the channel, the practical takeaway is that market-entry support now runs at provincial granularity, with a named counterpart organization on each side rather than a general bilateral aspiration. The membership numbers behind the partnership The membership base gives the agreement its scale. By the end of September 2026, more than 6,650 Chinese companies were registered as active members of Dubai Chamber of Commerce, a figure that has more than tripled since 2016. The industry distribution within that base is the more useful number: over 3,830 of the member companies operate across trade and services, representing around 58 percent of all Chinese member companies. That concentration tells market entrants two things. First, the established Chinese presence is weighted toward trading and service operations, which means the support infrastructure members have built up, from certificates of origin to trade documentation channels, is calibrated to that profile. Second, the remaining 42 percent spans manufacturing-adjacent, technology and investment vehicles, the segments both governments are now targeting through agreements like the Jiangsu memorandum. A company entering outside the trade-and-services mainstream should expect fewer peer benchmarks in its own segment but a chamber apparatus that is actively recruiting for that diversification. The wider institution shows the same orientation. Dubai International Chamber, one of three chambers under Dubai Chambers, attracted 373 international companies to Dubai during 2025, including 64 multinational companies and 309 small and medium enterprises. Its global representative-office network reached 38 offices by the end of 2025, the organization received 141 international trade delegations during the year, and it participated in or organized 235 international roadshows across 190 cities. Membership is embedded in that machinery: roadshows feed delegations, delegations feed registrations, and the registration data feeds the next round of provincial agreements. What membership costs and what it buys The fee schedule is published and banded. Annual membership runs from AED 300 to AED 2,200 depending on legal form, ownership nationality or activity type. Establishments practicing a specific activity pay AED 700; general trading pays AED 1,200 to 2,200; banks, insurance companies, building contractors and branches of international foreign companies pay AED 2,200; free zone companies pay AED 2,200; e-traders and holders of the Intelaq license pay AED 300. Members of the Mohammed Bin Rashid Establishment for Small and Medium Enterprises receive a five-year exemption. Processing is fast when the file is complete: applications meeting the requirements are reviewed and approved within two hours, with the certificate issued after payment. Renewal runs annually and requires a copy of the renewed trade license. The functional reason exporters join is document-driven: a certificate of origin requires a registered member, and commercial document attestation runs through the chamber. The published service set also covers mediation between commercial parties and networking channels, which positions membership as documentation infrastructure rather than a passive directory listing. Companies that neither export nor need attestation may not need membership at all, since the published pages do not describe it as universally mandatory, but banks and counterparties frequently request it in practice. The provincial-model scale is visible against the chamber’s wider footprint. In a separate engagement, Dubai Chambers and the Prague Chamber of Commerce explored economic cooperation with non-oil trade of USD1.44 billion, per the chambers’ own announcement, a figure that puts the China relationship’s AED363.5 billion in proportion: the Jiangsu agreement is not a symbolic exchange but an extension of the chamber’s largest single trade corridor down to province level. The same logic explains why the member data is published by nationality in quarterly counts rather than aggregated: the corridor metrics are the institution’s operating dashboard, and each new provincial memorandum feeds a measurable target rather than a general aspiration. The trade and investment trajectory The commercial baseline under the membership growth is trade, and its shape is documented. Non-oil trade between Dubai and China rose from AED166.4 billion in 2016 to around AED363.5 billion in 2025, an increase of 118.4 percent over the decade. Investment flows moved on the same axis but later: Dubai attracted more than 300 foreign direct investment projects from China between 2016 and 2025 with combined capital exceeding AED24.6 billion, and the annual pace accelerated sharply in the most recent years, with Chinese FDI capital rising from around AED1.2 billion in 2024 to more than AED3.4 billion in 2025. Non-oil trade between the two grew almost 23 percent over the same recent period. The lag between trade growth and investment growth is the pattern worth reading. Trading relationships established the member base; the investment step-up is the newer phase, and the sector agenda attached to recent engagement reflects it, with discussions covering artificial intelligence, advanced manufacturing, logistics, smart mobility, the digital economy and venture capital rather than merchandise trade alone. The Shenzhen forum and what it signals The Jiangsu memorandum followed the Dubai Business Forum China, held in Shenzhen in October 2026, which attracted 854 Chinese investors and business leaders and featured the largest overseas business delegation Dubai Chambers has ever led: 112 senior representatives from Dubai’s public and private sectors. The program ran across sessions on artificial intelligence, advanced manufacturing, logistics, smart mobility, the digital economy and venture capital, under the chambers’ economic agenda for the emirate. For an outside observer, the sequence, forum, provincial memorandum, published membership data, forms a pipeline with measurable stages. The forum surfaces demand, the memorandum institutionalizes it at province level, and the membership registry records the result in quarterly counts. Companies evaluating entry timing can read that pipeline directly: the institution has committed public targets around international expansion, its fee and processing terms are fixed and published, and the provincial channels now include named counterparts in one of the largest manufacturing regions feeding the member base. The risk sitting on the other side of the ledger is concentration: a member base that is 58 percent trade-and-services moves with trade cycles, which is precisely the exposure the diversification agenda is built to reduce. Sources Sources: Economy Middle East, “Dubai Chambers, Jiangsu chamber sign MoU to boost trade and investment as Dubai-China non-oil trade hits $98.9 billion,” 2026-11-05. https://economymiddleeast.com/news/dubai-chambers-jiangsu-chamber-sign-mou-to-boost-trade-and-investment-as-dubai-china-non-oil-trade-hits-98-9-billion/ Dubai Chambers membership, trade and FDI figures as stated by Dubai Chambers and reported in source 1 (6,650 active Chinese member companies end-September 2026; AED363.5 billion non-oil trade 2025; 300+ FDI projects and AED24.6 billion capital 2016-2025). Dubai International Chamber 2025 activity data (373 international companies, 64 multinationals, 309 SMEs, 38 offices, 141 delegations, 235 roadshows across 190 cities), per Dubai Chambers. EZONE, “Dubai Chamber of Commerce Membership: Fees, Who Needs It and How to Join,” citing the published Dubai Chambers fee schedule and two-hour approval timeline, reviewed 2026-11-13. https://e.zone/?p=44609 Africa Business Watch / EINPresswire, “MWE Display Joins Dubai Business Forum China in Shenzhen,” 2026-10-20 (forum date, delegation size and session agenda). https://www.africabusinesswatch.com/article/950859765-mwe-display-joins-dubai-business-forum-china-in-shenzhen-to-advance-middle-east-digital-signage-partnerships Economy Middle East, “Dubai Chambers, Prague Chamber of Commerce explore economic cooperation as non-oil trade hits $1.44 billion,” 2026 (Prague corridor figure, per Dubai Chambers). https://economymiddleeast.com/news/dubai-chambers-prague-chamber-of-commerce-explore-economic-cooperation-as-non-oil-trade-hits-1-44-billion/ This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Vietnam profit repatriation rules and the SBV dollar-buying shift SeaPRwire

Vietnam profit repatriation rules and the SBV dollar-buying shift

On 6 November 2026 the State Bank of Vietnam announced a USD2 billion foreign exchange swap programme with a 182-day maturity, and from 11 November it began buying US dollars outright at VND25,500 per dollar in scheduled Monday and Wednesday sessions. The two operations are liquidity management, not a rewrite of the capital account: every rule governing how a foreign investor moves dividends out of the country sits in Circular 38/2026/TT-NHNN, which has been in force since 18 August 2026, and that circular is unchanged. What the FX shift does change is the backdrop against which repatriation timing gets decided, which makes this the right moment to restate the full money-trail checklist the circular actually requires. The two operations and what they do The first mechanism is the swap. The State Bank buys dollars from commercial banks at VND24,399 per dollar and commits to selling them back after 182 days at VND24,704, a structure that supplies dong with a built-in return obligation. The programme supplied nearly VND50 trillion to the banking system on 9 November, according to Nguyen Linh Phuong, deputy director of the central bank’s Monetary Policy Department, as reported by the Vietnam News Agency service. The six-month maturity means banks hold dong funding into May 2027, covering both year-end settlement and the Tet period. The second mechanism is the outright purchase, running from 11 November 2026 at VND25,500 per dollar in sessions every Monday and Wednesday. Eligible sellers are credit institutions and foreign bank branches holding positive foreign exchange positions, and the maximum purchase from each institution is the amount needed to bring its position back to balance. The structural difference is the absence of a sell-back commitment: every USD1 billion purchased outright supplies approximately VND25.5 trillion that never has to be returned at a set date, which is why the market reads the spot channel as the more durable injection. The purchase price sits close to market. The interbank rate on 9 November was VND25,547 per dollar, only about 0.18 percent above the central bank’s buying price, according to An Binh Securities’ macro update of 10 November, so banks have an incentive to sell when rates drift back toward that level. Why the bank is doing it The pressure indicators behind the operations are published. In the final week of October the State Bank injected a net VND28.13 trillion through open market operations, according to the Vietnam Banks Association. Interbank overnight rates reached 5.79 percent on 30 October and the three-month rate climbed to 7.47 percent. Outstanding credit reached approximately VND20.9 quadrillion as of 4 November, up 12.55 percent from the end of 2025, with seasonal demand toward year-end adding to funding pressure. The deposit side has already moved: all 46 commercial banks had reduced listed deposit rates for maturities of six months or longer by at least 0.5 percentage points as of 4 November, and around 22 banks had lowered lending rates, again per the banks association. The FX supply side supports the purchases: October’s trade surplus reached about USD7.3 billion, September’s roughly USD1.3 billion, and FDI disbursements reached USD24.08 billion in the first ten months of 2026, up 13.1 percent year on year, according to ACBS research. Foreign exchange reserves, estimated at USD87.6 billion as of 18 June 2026 by the news service account, remain below the peak of nearly USD112 billion in early 2022, so the purchases double as reserve rebuilding while the exchange rate is benign. For a foreign investor, the relevant reading is directional: the central bank is buying dollars at a rate just under the interbank level, the dong has weakened about 2.3 percent against the dollar year to date at commercial banks according to ACBS, and the operations aim to keep that drift orderly. None of it alters the paperwork. The account trail profit repatriation must follow Circular 38/2026/TT-NHNN, issued 31 July 2026 and effective 18 August 2026, replaced Circular 06/2019/TT-NHNN and rebuilt the foreign exchange framework for direct investment. Its central object is the investment capital account, the renamed successor of the direct investment capital account. All capital movements connected to a direct investment, including profit remittance, must pass through this account at a licensed bank. A company established by foreign investors must have one; an economic organization not established by foreign investors falls in scope once foreign ownership exceeds 50 percent of charter capital, counting member-enterprise holdings. The circular also loosened the front end. Foreign-invested organizations can now open the investment capital account before the investment registration certificate is granted or adjusted, using it in the preparatory phase only to receive charter capital and its interest, pay investment-preparation expenses and return capital if the certificate never comes. Once the certificate is granted, the same account carries the operating revenue and expenditure transactions the old regime required. Two rules matter most for the dividend leg. Profits divided in dong are also collected into the investment capital account, which means dong-denominated distributions do not bypass the designated channel. And equity transfer payments between non-resident investors and resident investors must be made through the investment capital account and must be valued and paid in dong, a pairing that gives every later remittance a documented, single-account cash trail. The checklist before any dividend leaves The repatriation trigger is procedural, and the sequence is fixed. The fiscal year must be closed. The enterprise must have fulfilled its financial obligations to the state. The audited financial statements and the annual corporate income tax finalization return must have been submitted to the directly supervising tax authority. The investor or the entrusted enterprise must notify that tax authority in the prescribed form at least seven working days before the planned remittance. And where the year’s financial statements still show accumulated losses after carry-forward, that year’s profit cannot be remitted at all. Each step is documentary rather than discretionary. A remittance that reaches the bank before the seven-working-day notice has run, or before the audited statements are filed, stalls at the compliance check rather than at the counter, and the administrative penalty framework for account misuse runs to fines of VND30-50 million for individuals and double for organizations. The practical discipline is to schedule repatriation around the audit calendar, since the annual CIT finalization deadline fixes when the full checklist can realistically be complete. The reinvestment shortcut and the closure clock Circular 38 also created a round-trip exemption worth pricing. Where lawful profits and revenues are not transferred abroad, the investor may move them from the investment capital account to a current account at a licensed bank to fund other investment projects or activities in Vietnam; the same mechanism covers capital recovered through reduction, transfer or project termination. Dong dividends collected into the investment capital account can likewise feed capital increase and expansion without leaving the system. An investor reinvesting domestically therefore skips the outbound remittance entirely, saving the international transfer cost and the exchange-rate spread between leaving and re-entering the currency. The counterpart obligation is a closure clock. Economic organizations that previously required an investment capital account but no longer meet the ownership test, because foreign and member-enterprise ownership falls to 50 percent or below, or because they become listed or registered-for-trading public companies, must close the account, and organizations established by foreign investors that lost their foreign ownership entirely must complete closure within 12 months from 18 August 2026. An ownership restructuring without an account-closure step leaves a live compliance gap even when the commercial documents are done. What the dollar purchases change and what they do not The operations change timing economics, not documentation. A company whose dividend checklist is complete faces a currency market where the central bank is an active buyer near the interbank rate, which limits the upside of waiting for a stronger dong and reduces the tail risk of a disorderly move against the dollar. A company whose checklist is incomplete gains nothing from the FX environment, because its constraint is procedural. The account trail, the seven-working-day notice, the audited-statement prerequisite and the loss-year block all sit outside monetary operations, and they are the parts a remittance plan can actually control. Sources Sources: Vietnam News Agency / BizHub, “Explainer: Why Viet Nam is buying US dollars and how the move affects the market,” 2026-11-12. https://bizhub.vietnamnews.vn/explainer-why-viet-nam-is-buying-us-dollars-and-how-the-move-affects-the-market-post417899.html State Bank of Vietnam foreign exchange operations: USD2 billion 182-day swap announced 2026-11-06 (buy VND24,399 / sell-back VND24,704); outright purchases from 2026-11-11 at VND25,500, sessions every Monday and Wednesday, per source 1 citing the central bank. ACBS Research, “SBV Spot USD Purchases,” 2026-11-10/11 (trade surplus, FDI disbursement USD24.08 billion 10M 2026 +13.1% YoY, reserves, interbank levels). https://acbs.com.vn/en/report/sbv-spot-usd-purchases Circular 38/2026/TT-NHNN on foreign exchange management for foreign investment activities, issued 2026-07-31, effective 2026-08-18, replacing Circular 06/2019/TT-NHNN; analysis per Lexsol Law Firm, submitted 2026-11-03. https://lexsolasia.com/en/circular-382026tt-nhnn-new-regulations-on-foreign-exchange-management-for-foreign-investment-activities-in-vietnam Vietnam profit repatriation conditions (fiscal year closure, tax obligations, audited statements and annual CIT finalization, 7-working-day advance notice, loss-year block) per Vietnamese law as summarized by Zagdim, reviewed 2026-11-13. https://zagdim.com/foreigners-vietnam-llc-capital-compliance ASEAN Briefing, “Singapore Holding and Trading Companies: A Guide for Vietnamese Businesses,” 2026 (Decree 103/2026/ND-CP profit retention and remittance rules). https://www.aseanbriefing.com/news/singapore-holding-trading-companies-vietnamese-businesses This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Saudi Arabia raises Saudization to 35 percent for 94 engineering roles SeaPRwire

Saudi Arabia raises Saudization to 35 percent for 94 engineering roles

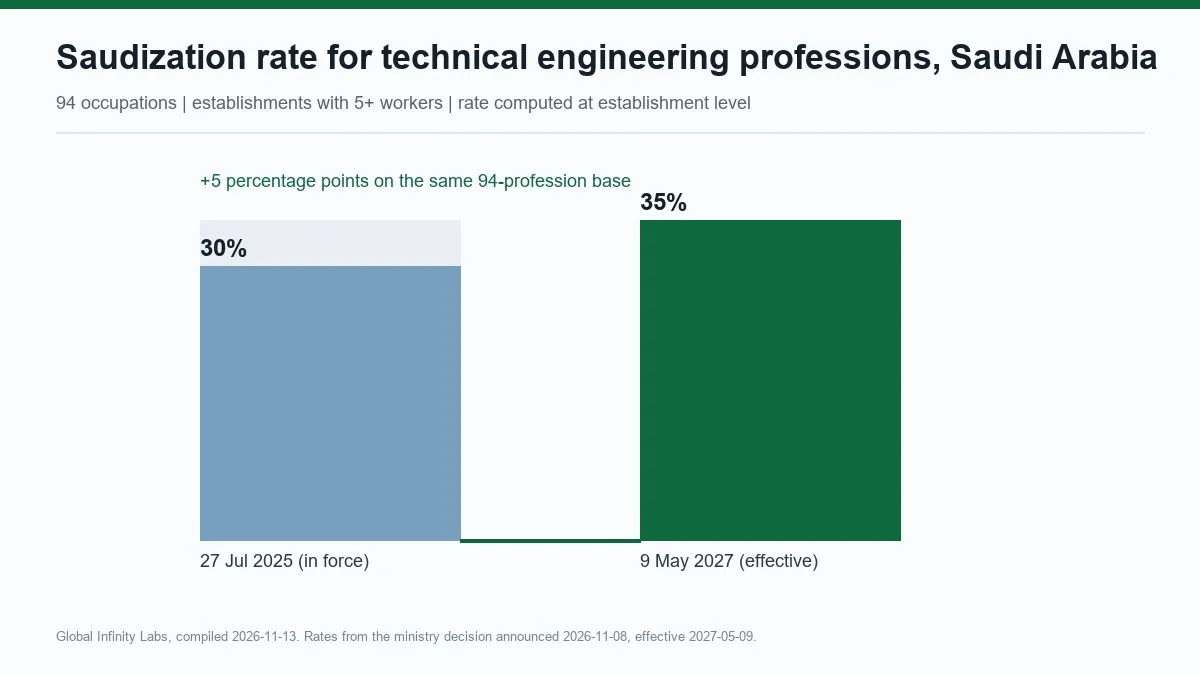
On 8 November 2026, the Ministry of Human Resources and Social Development, working with the Ministry of Municipalities and Housing, announced that the Saudization rate for 94 technical engineering professions in private sector establishments will rise from 30 percent to 35 percent, effective 9 May 2027. The six-month runway is deliberate: establishments in scope have until May to adjust headcount before the higher floor binds, and the calculation method is fixed in advance rather than left to field interpretation. For engineering-heavy contractors, consultancies and industrial operators, the decision changes the compliance arithmetic on every project staffing plan that runs past the second quarter of 2027. What the decision covers The 94 professions are technical engineering occupations classified under the Saudi Standard Classification of Occupations. Published lists name civil engineering technicians, electrical engineering technicians, mechanical engineering technicians, electronic engineering technicians, surveying technicians, mechanical maintenance technicians and architectural draftsmen, among others in the same occupational family. The common thread is technician-grade technical work: roles that support licensed engineers rather than duplicate them, which is where past localization rounds found the largest substitutable expatriate headcount. Two scope rules determine who counts. The first is a size gate: the requirement applies to private sector establishments employing five or more workers in the targeted professions. Establishments below that threshold in these occupations stay outside the mandate. The second is the counting unit: the rate is calculated at the establishment level, in accordance with the ministry’s procedural guide, not at the company or group level. A parent company cannot average a compliant site against a non-compliant one; each registered establishment carries its own ratio, computed from the occupations its workers hold under the standard classification. The procedural guide has been published on the ministry’s website and does the definitional work that determines compliance: which professions are covered, how the Saudization rate is calculated, the implementation mechanisms and the compliance requirements. Since the rate turns on occupation classification, an establishment whose job titles do not match its workers’ actual classification codes will compute a different ratio than the ministry does. Reconciling internal job architecture against the standard classification is therefore the first work item, before any hiring or redeployment decision. The baseline it builds on The new floor is a five-point step, not a new regime. The ministry had already enforced a 30 percent Saudization requirement for technical engineering professions in establishments with five or more workers, effective from 27 July 2025. The 2027 decision raises that existing requirement by five percentage points on the same occupational base and the same counting unit, which makes the change easier to cost: establishments that met the 2025 requirement know their denominator, and the adjustment is incremental headcount in the covered occupations rather than a rebuild of the compliance framework. The sequencing also signals method. Specialized professions are being localized in staged rounds, each announced with a defined effective date months ahead, a published procedural guide and a support package running alongside. For workforce planners, the pattern matters as much as the current number: occupation families that have already seen one staged increase are the natural candidates for the next one, and the interval between announcement and enforcement has been long enough to plan against. What employers must do before 9 May 2027 The compliance sequence for the next six months runs through four steps. First, map the establishment’s headcount against the 94 covered occupations using the standard classification codes, and compute the current establishment-level rate from the guide’s method. Second, quantify the gap between that figure and 35 percent, expressed in the covered occupations specifically; hiring outside the covered list does not move the ratio. Third, close the gap through the ministry’s support channels, which the announcement describes as a comprehensive package covering assistance with recruitment, training, qualification, employment and job stability, plus priority access to Saudization support programs. Fourth, verify the resulting ratio against the guide’s calculation rules before the effective date, since the enforcement check will recompute from the same definitions rather than from internal HR categories. The support package matters for feasibility. Saudization targets in technical occupations are constrained by the supply of qualified nationals, which is why the ministry pairs each mandate with training and qualification programs rather than leaving establishments to bid against each other for an unchanged talent pool. Establishments that engage the qualification channels early hold a timing advantage over those that wait for the effective date and then compete for already-certified candidates. Why engineering, and what the skills data says The choice of occupation family is grounded in the ministry’s own commissioned research. A World Bank study, “Upskilling: Required Skills and Workforce Development in Saudi Arabia,” prepared at the ministry’s request, surveyed 3,016 private sector establishments across the kingdom’s 13 regions between May and October 2024. Its findings describe the constraint the decision addresses: 61 percent of businesses said gaps in employee capabilities had cost them potential profits, 55 percent reported lost business opportunities, and 48.5 percent said capability gaps had affected the quality of their products and services. The same study maps where the workforce actually sits: retail, hospitality and food services account for 43 percent of the surveyed workforce and construction another 19.7 percent. That composition helps explain why the localization program keeps moving into technical and engineering occupations rather than stopping at retail categories; sectors that rely less heavily on advanced capabilities absorb most existing national employment, while the specialized professions remain expatriate-heavy. The study’s recommendation runs in the same direction as the quota increase: move employment toward higher-productivity activities that use advanced skills, rather than protecting low-skill headcount. The wider enforcement backdrop and the grey areas The quota increase lands in an already tightening enforcement environment. On 4 November 2026 the ministry announced enforcement action against recruitment offices, suspending 66 agencies and revoking one license for violations in the recruitment chain, according to the ministry’s own announcement as reported internationally. Read together with the staged quotas, the signal is that compliance is being checked on both sides of the labor market: the demand side through establishment-level ratios and the supply side through the offices that move workers into the kingdom. A worked example shows how the arithmetic lands. An establishment holding 20 workers across the covered occupations needs 7 of them to be Saudi nationals at 35 percent, against 6 at the current 30 percent; the guide’s calculation method governs how fractional results are treated, so the first step is still reading the method rather than assuming standard rounding. The same establishment with 12 covered workers needs 5 at the higher floor against 4 at the lower one, a full additional headcount. Establishments running multiple sites each run this calculation separately, and a group with ten establishments may carry ten distinct gaps even when the group total looks comfortable on a spreadsheet. Two grey areas deserve explicit treatment in staffing plans. The first is the establishment-versus-company distinction, which penalizes internal reallocation strategies: moving a covered technician from a compliant site to a non-compliant one fixes neither ratio and can break both. The second is the classification question, since technician roles defined by function rather than by job title can fall inside or outside the 94 depending on how the establishment’s records map to the standard classification. Establishments expecting to sit near the boundary should document their mapping before the effective date rather than after the first inspection finds a discrepancy. The ministry’s procedural guide is the operative text for both questions, and it is already published, which leaves six months to reconcile against it rather than to guess at it. Sources Sources: Saudi Gazette, “Saudization rate raises to 35% for 94 technical engineering professions, effective May 9, 2027,” November 2026. https://saudigazette.com.sa/article/611717/SAUDI-ARABIA/Al-Rajhi-signs-pacts-with-Burundi-minister-to-recruit-domestic-help?format=simple Ministry of Human Resources and Social Development decision and procedural guide (with the Ministry of Municipalities and Housing), announced 2026-11-08, guide published on hrsd.gov.sa. People Matters Middle East, “Saudi Arabia to raise Saudisation rate to 35% across 94 engineering technical occupations from May 2027,” 2026-11-08. https://me.peoplemattersglobal.com/news/economy-policy/saudi-arabia-to-raise-saudisation-rate-to-35percent-across-94-engineering-technical-occupations-from-may-2027-53271 ETHRWorld EMEA, “Saudi Arabia lifts saudisation rate to 35% for 94 engineering roles,” 2026-11-10. https://hrme.economictimes.indiatimes.com/news/industry/saudi-arabia-lifts-saudisation-rate-to-35-for-94-engineering-roles/135697018 World Bank, “Upskilling: Required Skills and Workforce Development in Saudi Arabia,” prepared at the request of the Ministry of Human Resources and Social Development; survey of 3,016 establishments, May-October 2024. Zawya / SyndiGate, “Saudization rate raises to 35% for 94 technical engineering professions,” November 2026. https://www.zawya.com/en/economy/saudization-rate-raises-to-35-for-94-technical-engineering-professions-effective-may-9-2027-2126599 Legit.ng, “Saudi Arabia Changes Employment Rules for Foreigners in 94 Occupations,” 2026-11-08; enforcement action against recruitment offices reported 2026-11-04. This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Philippines foreign ownership checks: what the SEC now verifies SeaPRwire

Philippines foreign ownership checks: what the SEC now verifies

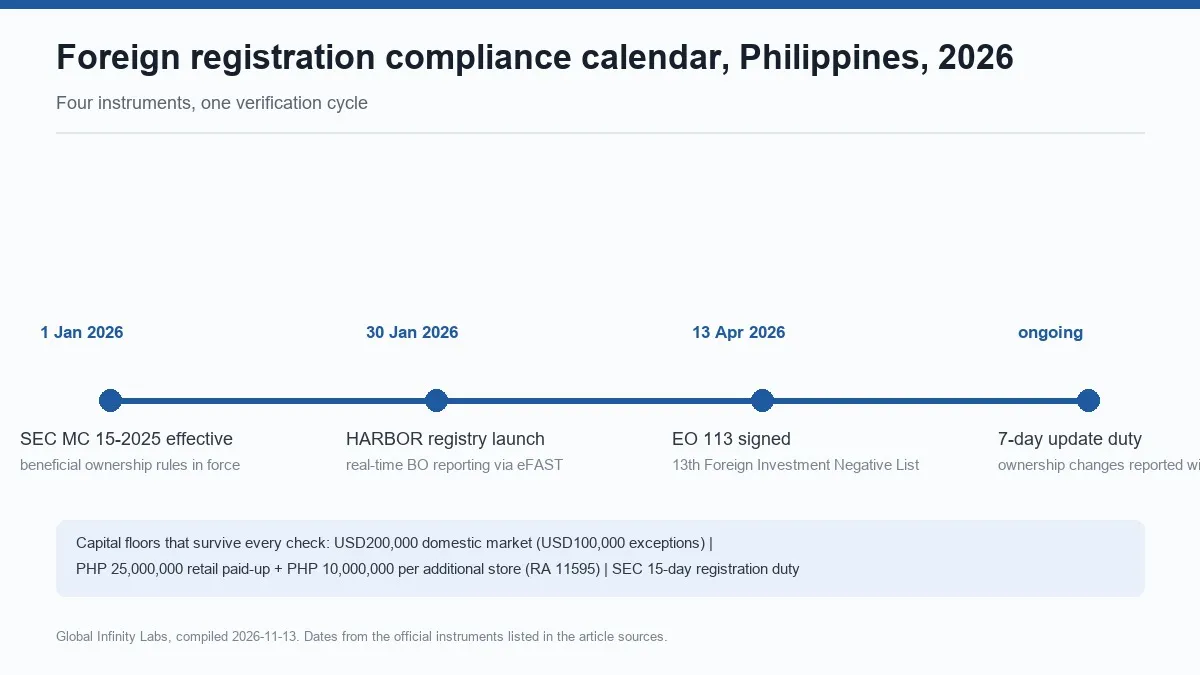
A report published on 9 November 2026 describes a shift in how foreign-owned company registrations are being reviewed: forms now probe the actual source of capital and the real decision-making structure, not just the shareholder list, and applications touching restricted sectors draw more clarification requests before approval. The mechanics behind that shift are not new rules but new verification weight on rules that already exist. Four instruments carry the load: the 13th Regular Foreign Investment Negative List, the amended Foreign Investments Act, the revised beneficial ownership disclosure rules, and the anti-dummy statute. Knowing which instrument answers which question is what separates a registration that clears in one pass from one that bounces between clarification rounds. What the 13th negative list actually caps The current Foreign Investment Negative List is the 13th regular edition, promulgated through Executive Order No. 113 and signed on 13 April 2026. It replaced the 12th list issued under Executive Order No. 175 of 2022, which means any checklist still quoting EO 175 as the operative list is out of date. The document has two parts. List A holds restrictions that come from the Constitution and specific statutes, so it moves whenever those laws move. List B holds restrictions justified by security, defence, health and the protection of small and medium enterprises, and may be amended at most once every two years. List A carries the headline ceilings. Mass media must be wholly owned and managed by citizens. Corporations holding private land need at least 60 percent Filipino ownership, though a foreign-owned company can lease instead. Exploration and development of natural resources is open only to corporations at least 60 percent nationally owned, apart from agreements the Constitution itself authorizes. Practiced professions sit under their own licensing laws rather than the corporate code, and a professional corporation cannot practice a profession unless a special law allows it. Retail trade runs on a separate statute. Under Republic Act No. 11595, a foreign retailer needs minimum paid-up capital of PHP 25,000,000, plus PHP 10,000,000 per physical store once it operates more than one store. The law also requires reciprocity: the foreign retailer’s home country must not bar Filipino retailers from operating there. These figures are statutory floors, not administrative guidance, so no filing step can waive them. The capital floors and where they drop to USD100,000 For everything outside retail and the negative list, the general rule reads the other way. The Foreign Investments Act, as amended by Republic Act No. 11647 in 2022, allows a non-Philippine national to invest up to 100 percent of a domestic enterprise’s capital without prior approval, unless a law or the negative list caps the share. The same amendment instructs the corporate regulator not to add ownership limits of its own and to register a complete application within fifteen days. The constraint that trips most filings is a different clause: every micro and small domestic market enterprise with paid-in equity below USD200,000 is reserved to nationals. The USD200,000 floor carries three statutory exceptions that drop it to USD100,000. The first applies where the business involves advanced technology as determined by the science and technology department. The second covers qualifying startup status. The third applies where the enterprise directly employs at least 15 Filipino workers. Each exception is conditional and evidence-based; the payroll route, for instance, needs a Filipino-majority direct workforce documented in the file. An export enterprise sits outside the domestic-market test entirely, which is why the classification of the company’s customer base matters before the capital figure is chosen. The USD figure is a paid-in equity test, not a filing fee and not a substitute for a peso conversion. Converting the statutory dollar reference into a fixed peso budget requires a dated exchange rate and the specific legal test at filing time. Teams that treat the USD200,000 as a one-line cost item tend to discover at the bank stage that the certificate of inward remittance, which evidences that the capital actually entered the country, is itself now subject to fuller know-your-customer checks before the bank issues it. Beneficial ownership reporting moved out of the annual form A second verification layer sits outside registration altogether. SEC Memorandum Circular No. 15, Series of 2025, the revised beneficial ownership disclosure rules, took effect on 1 January 2026. Under the new regime, the annual general information sheet no longer carries a beneficial ownership section; that information lives in the HARBOR registry, a web platform launched on 30 January 2026 and integrated with the regulator’s eFAST filing portal. Because the platform feeds regulators in real time, disclosure is now an ongoing obligation with its own timeline rather than an annual checkbox. The reporting trigger is any natural person who ultimately owns, controls or benefits from the corporation, traced through every layer of the structure. Category A alone captures anyone holding at least 20 percent of voting shares, and further categories reach control exercised through contractual arrangements, proxy voting or director-appointment rights. Each reported individual requires name, residential address, date of birth, nationality, contact details, tax or passport identification, civil status and politically-exposed-person status. Ownership changes must be reported within seven calendar days of occurrence, and the penalty regime for persistent non-compliance reaches fines of up to PHP 2,000,000 and, in the worst cases, dissolution proceedings. For a foreign shareholder, the practical consequence is that the cap table filed at registration and the beneficial ownership record in HARBOR must describe the same reality at all times. A share transfer executed offshore on a Monday is reportable within the week, even when nothing else about the local company changed. The nominee problem and the penalties behind it The reason regulators lean harder on verification is the pattern the anti-dummy statute exists to punish. Commonwealth Act No. 108, as amended, criminalizes arrangements where citizens lend their names to let foreign parties evade nationality requirements. Penalties run from five to fifteen years of imprisonment, fines of no less than the value of the right or privilege illegally enjoyed, deportation for the foreign principal involved, and cancellation of registrations and licenses. The statute also reaches control, not just title: directing a restricted enterprise through board votes, signing authority or contractual vetoes beyond the permitted equity counts as intervention, even when the share register looks clean. Enforcement coordination among the corporate regulator, the justice department and the immigration bureau has intensified through 2026, and the registry’s real-time beneficial ownership data is precisely what makes the classic mismatch visible: filings showing one ownership split, tax returns and board minutes showing another. The recurring tells are informal side contracts giving a foreign party control beyond its equity cap, a foreign signatory exercising authority the equity does not permit, and proxy arrangements that push voting power past the legal ceiling. Where the grey areas sit Two structures generate most of the avoidable friction. The first is the mixed-purpose company that bundles a restricted activity with an unrestricted one and averages the ownership across both. The rule is per-activity: each line item is tested against the negative list on its own terms, and a general trading label can conceal retail, import or regulated work that carries a different ceiling. The second is the nominee arrangement, where the local shareholder holds shares on paper with no real stake. Beyond being criminal exposure for both sides, it provides no fallback when the registration file is cross-checked against operating reality, because the mismatch is exactly what the current verification cycle is built to surface. None of this amounts to a closing door. Outside the negative list, full foreign ownership remains available, the fifteen-day statutory registration clock still runs on complete applications, and the 2026 instruments opened more activities than they closed. The verification push changes the evidence standard, not the permission standard: registrations now need a documented money trail, an ownership record that updates within seven days of any change, and a structure whose control matches its cap table. Files that arrive with those three elements complete move faster than they did before; files that rely on templates do not. Sources Sources: ACFTL, “Philippines Tightens Rules on Foreign Business Registration,” 2026-11-09. https://acftl.org/philippines-tightens-rules-on-foreign-business-registration-2/ Executive Order No. 113 (13th Regular Foreign Investment Negative List), signed 2026-04-13, via Official Gazette / Supreme Court E-Library. Republic Act No. 11595 (Retail Trade Liberalization Act amendments), 2021-12-10, Supreme Court E-Library. Republic Act No. 11647 (Foreign Investments Act amendments), 2022, Supreme Court E-Library. SEC Memorandum Circular No. 15, Series of 2025 (Revised Beneficial Ownership Disclosure Rules), effective 2026-01-01; HARBOR registry launched 2026-01-30. Korp.ph, “What Is the SEC HARBOR Registry?” and “Anti-Dummy Law guide for Philippine startups,” reviewed 2026-11-13. https://www.korp.ph/blog/what-is-the-sec-harbor-registry-a-simple-guide-for-philippine-business-owners Global Law Experts, “Using a Foreign Holding Company to Invest in the Philippines (2026),” reviewed 2026-11-13. https://globallawexperts.com/news/foreign-holding-company-philippines MyDavaoBase, “Registering a Company in the Philippines as a Foreigner,” reviewed 2026-11-13. https://mydavaobase.com/the-feed/register-company-philippines-foreigner This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Germany’s Checkout Is Split Three Ways: girocard, PayPal and a Cash Habit That Refuses to Die SeaPRwire

Germany’s Checkout Is Split Three Ways: girocard, PayPal and a Cash Habit That Refuses to Die

Bundesbank data for 2025 shows 45 percent of purchases still in cash, 25 percent of cashless attempts failing, and a mandate bill coming in 2027 Budget for 2027 now, because that is when the free option disappears. The German finance ministry is preparing a bill that would require merchants to offer customers an electronic payment option at the checkout; it goes to cabinet in this legislative year and, if the schedule holds, takes effect in 2027. Retail associations have already pushed back, warning that terminal purchases and per-transaction fees will fall hardest on small operators, and their objections are not cosmetic, because the fee spread between Germany’s payment instruments is among the widest in Europe. Any merchant entering the German market in 2026 inherits that spread, a cash habit that still covers 45 percent of transactions, and an online checkout dominated by one American company. The paths through this differ by months of setup and multiples of cost, and the order of decisions matters more than the order most market-entry checklists assume. The trouble starts with the numbers. Germany’s central bank published its payment behaviour study for 2025 based on roughly 6,000 respondents who kept a three-day payment diary between September and early December 2025. For the first time since the series began in 2008, cashless payments crossed half of all recorded purchases: 55 percent cashless, 45 percent cash by transaction count, down 6 percentage points from 2023. Debit cards, girocard above all, took 26 percent. Mobile payments took 10 percent, up 4 points. E-payment methods, the online checkout instruments, doubled their share to 6 percent. By value the picture inverts: debit cards lead with 28 percent of turnover, cash and credit transfers share second at 23 percent each, because cards absorb the larger purchases and cash the small ones. The scene you inherit Read the same study as an operations document rather than a trend report, because four of its findings change what a merchant must build. Payment instrument, Germany 2025 Share of purchases (by count) Share of turnover (by value) Cash 45% 23% Debit card (girocard dominant) 26% 28% Mobile payment methods 10% not broken out E-payment methods (online checkout) 6% not broken out Credit transfer counted in cashless totals 23% Source: Deutsche Bundesbank , payment behaviour study 2025 Cash is accepted in 94 percent of purchases at physical locations, and 80 percent of respondents say keeping the cash option is important regardless of personal preference. Older customers, lower-income customers and those with lower digital literacy use cash more; 12 percent say they would have serious difficulty running daily errands without it. A cashless-only store does not just lose sales in Germany, it loses the customers least able to switch. Cashless acceptance still fails. Around one quarter of respondents reported at least one moment in the past month when they wanted to pay cashless and could not. Cashless was possible in 86 percent of physical purchases, 5 points better than 2023 but nowhere near the 94 percent cash acceptance rate. Every percentage point of failed acceptance is a checkout queue that stalls. The dominant debit instrument is domestic. girocard, still called EC-Karte by half the population, is the debit scheme of record. In the first half of 2026 it processed 4.21 billion transactions worth EUR 151.9 billion, through 1.397 million acceptance terminals, a terminal count that grew 11.1 percent year on year. The average ticket fell to EUR 36.12 as contactless hit 92 percent of girocard use, which tells you girocard is absorbing the small, fast purchases cash used to own. Online, one instrument dominates twice over. PayPal holds about 86 percent of the e-payment methods market, and 28.7 percent of German online retail volume runs through it. Apple Pay is the most used mobile payment method at the physical point of sale, and the cards inside German digital wallets are mostly Visa and Mastercard. The fee structure underneath is where the spread lives. Industry cost comparisons recorded for 2025 put girocard transactions at about 0.2 percent, with all-in costs around 0.8 percent of turnover, the lowest per-value burden of any instrument. International debit cards run roughly 2.1 percent all-in and credit cards 2.4 percent. Cash, the instrument everyone assumes is free, carries a full economic cost around 2.3 percent once counting, guarding, transporting and shrinkage are priced. Per transaction rather than per euro, cash at about EUR 0.43 is the cheapest instrument of all for small tickets. The ranking flips depending on the denominator, and a merchant who optimizes for the wrong one pays for it for the life of the contract. Why the standard playbook fails The default market-entry playbook, sign with an international PSP, accept Visa, Mastercard and the local wallets, go live in a week, fails a specific German test at each step. Start with the cash question. A card-only checkout in 2026 is legal but loses the 45 percent cash habit where it is strongest, at small tickets, among older and lower-income customers, and in local transport and self-service settings where the study shows cashless acceptance lagging. The step people skip is the cash logistics decision: even with the 2027 mandate arriving, cash remains 94 percent accepted and 80 percent valued, so the question is not whether to take cash but how to cost it, and the answer, roughly 2.3 percent all-in, is a cost, not a saving. Next, the PSP fee table. International debit and credit cards at 2.1 to 2.4 percent all-in cost six to ten times what girocard costs per euro. Europe’s interchange cap, in force since 2015 at 0.2 percent for consumer debit and 0.3 percent for credit, constrains the interchange component, but scheme fees sit outside the cap, and European regulators are actively investigating whether card schemes are recovering margin through scheme-fee increases. Budget for the published rate, then budget for the scheme-fee line item that the published rate does not include. Then the online checkout. A card-plus-wallets stack without PayPal reaches less than a third of German online retail, because 28.7 percent of it runs through PayPal and about 86 percent of e-payment method users keep an account. PayPal’s merchant fees are their own line item, above girocard economics by a wide margin, and refusing to integrate it in Germany is a conversion decision, not a cost decision. Finally, the timing trap. The European alternatives that would reorder this market are not ready at the same speed the mandate is. Wero, the bank-backed European wallet, has about 58 million users as of September 2026 and launched e-commerce payments in Germany in late 2025, but point-of-sale payments are only rolling out in the second half of 2026, with Germany expected as the first market. The digital euro is further out: the ECB’s pilot is set for September 2027 with potential issuance not expected before 2029. A merchant who waits for European rails to mature before signing anything will run the 2027 mandate transition on whatever stack the old contract left them. Path one: girocard-first, with a German acquirer Start with the domestic scheme if the business is physical retail. Sign with a German acquiring bank, procure girocard-capable terminals, and price the stack around the 0.2 percent rate and 0.8 percent all-in burden, the lowest per-euro cost on the market. Terminals are not a scarce commodity, with the acceptance network growing 11.1 percent in half a year, and contactless support at 92 percent of girocard transactions means the same hardware takes Apple Pay and Google Pay without a second procurement. The costs are time and paperwork rather than percentage points. German acquiring contracts, merchant onboarding and dispute handling run on German-language processes with local documentation requirements; setup is measured in weeks, sometimes a quarter, against days for an international PSP. The path covers the physical mandate of 2027 almost by accident, since girocard IS the domestic electronic instrument the mandate contemplates. What it does not cover is online: girocard is a point-of-sale scheme, and an online checkout still needs PayPal, cards, or the European rails to capture the 6 percent e-payment share. Plan path one as the POS core and assume the online layer is a separate procurement. Path two: international PSP stack Start with an international PSP if the business is online-first or the timeline is measured in weeks. One integration delivers cards, Apple Pay, Google Pay and PayPal, covering the online checkout where 87 percent of German online shoppers used cards in 2025 and 28.7 percent of retail volume runs through PayPal. Speed is the product here, and the price of speed is the fee table: roughly 2.1 to 2.4 percent all-in on international cards, plus PayPal’s merchant rates, plus the scheme-fee exposure regulators are currently probing. The step people skip in path two is the POS bridge. An online-first stack does nothing for the 2027 in-store mandate, so a merchant on this path still needs a German acquiring relationship or a PSP add-on for girocard acceptance, procured under time pressure if it waits for the mandate. Budget the two procurements as one project and the sequencing stops being a trap. Path three: European rails, early Start with Wero and SEPA instant if the horizon is European and the merchant can tolerate immature tooling. Wero moves money account-to-account over SEPA instant rails, bypassing card interchange entirely, and it is backed by 16 major European banks with 1,100-plus participating institutions. The user base, 58 million as of September 2026, roughly tripled in organizational membership to 45 scheme members in a single year, with Worldpay, Mollie and N26 among the recent additions. The EuroPA interoperability agreement, signed in February 2026 with Spain’s Bizum, Italy’s Bancomat, Portugal’s MB WAY and the Nordic Vipps MobilePay, extends the reachable base toward 130 million users across 13 countries, with e-commerce and point-of-sale interoperability targeted for 2027. Germany launched Wero e-commerce in late 2025; POS follows in the second half of 2026; the Dutch iDEAL migration completes by end-2027, which will move one of Europe’s largest bank-based payment bases onto Wero rails. The costs are uncertainty and integration churn. Merchant tooling is young, features like subscriptions and refunds are only arriving from late 2026, and the political tailwind that drives adoption, payment sovereignty after two major European retailers cited international resilience as their reason for adopting Wero, does not lower a single fee. The digital euro adds a second layer: German banking industry estimates put the cost of implementation in Germany alone at around EUR 2 billion, against an industry-commissioned eurozone estimate of up to EUR 30 billion and the ECB’s rebuttal that real costs would land near EUR 5 billion. Whichever number is right, the pilot in September 2027 and potential issuance from 2029 mean the digital euro is a 2028 procurement question, not a 2026 one. An early-mover merchant integrates Wero as an additional method now and keeps the architecture open for the digital euro, accepting that today’s integration may be rebuilt once. The policy layer moves on its own schedule Two regulatory tracks move under this market regardless of what any merchant does, and both have dates attached that a 2026 entrant should put in the plan. The first track is the mandate itself, and its detail matters more than its existence. The draft rule would force merchants to offer an electronic payment option, closing the gap between the 94 percent cash acceptance rate and the 86 percent cashless rate from the demand side. Retail associations are lobbying to let merchants pass fees through to customers who choose cards, which would change the effective cost table by instrument; the industry argument, recorded in reporting on the draft, is that girocard is cheap for the merchant while Visa, Mastercard and credit cards are not, and a surcharge option would shift the difference onto the customer’s choice. Watch whether the final bill allows surcharging, because if it does, the all-in cost column in every fee table above becomes a merchant decision rather than a fixed burden, and the cheapest-instrument ranking starts to influence customer behaviour directly. The second track is the European payments architecture, which is reassembling itself around three layers at once. The Instant Payments Regulation adopted in 2024 requires eurozone banks to offer SEPA instant credit transfer since January 2025, with non-eurozone EU banks following by January 2027, and caps instant fees at the level of ordinary transfers, removing the price premium that suppressed adoption for years. PSD3, the third payment services directive, is in legislative progress through 2026 and strengthens open banking, creating a regulated framework for account-to-account payments to compete with card rails. On top of both sits Wero, which runs on SEPA instant and is the commercial face of the sovereignty push. The Bundesbank’s own strategy, stated by its board alongside the 2025 study, is explicit: develop the digital euro, support European methods like Wero, and encourage instant credit transfers, while preserving cash as a cost-effective and inclusive means of payment. Translated into merchant language: the regulatory direction favors the cheap domestic rail and the emerging European one, and penalizes nothing, but the fee advantage compounds year by year as instant rails spread. The central bank’s framing also contains the sharpest constraint on the cashless optimism. Complete freedom of payment choice, the Bundesbank noted alongside the study, does not yet exist in Germany, because acceptance gaps persist in local public transport and at self-service checkouts, and the cash supply infrastructure itself is thinning as banks close branches and dismantle ATMs, which makes cash harder to obtain in rural areas even as demand for the option stays at 80 percent. A merchant planning around a linear cash decline should price the reverse risk: the groups that rely on cash are precisely the groups whose alternative payment options are weakest, and the mandate of 2027 obliges acceptance without changing anyone’s habit of carrying it. What to choose, by what you are building Path Setup speed Per-euro cost Coverage Main risk girocard-first, German acquirer weeks to a quarter about 0.8% all-in (lowest) POS mandate covered; online needs separate layer setup friction; no online coverage alone International PSP stack days to weeks 2.1% to 2.4% plus PayPal online checkout covered; POS mandate open fee load; scheme-fee drift; PayPal dependency European rails early (Wero) months, tooling maturing bypasses card interchange, near-zero scheme cost partial; POS from H2 2026; interop 2027 immature tooling; integration rebuild risk Source: cost and coverage assessment compiled from the Bundesbank study, PSP-published rates and Wero programme disclosures as cited below Three selection rules fall out of the table. Physical retail with local customers: path one, with the online layer added later, because the mandate, the cash culture and the fee table all point domestic. Online-first: path two, with girocard added before the 2027 deadline rather than after it. Pan-European or sovereignty-sensitive: path three as a second method alongside one of the others, never instead, because a payment method with 58 million users cannot be a store’s only rail. The common mistake is treating these as replacements; in Germany’s split checkout they are layers, and the fee table above is the argument for layering deliberately rather than stacking accidentally. One action costs almost nothing today and improves every path: instrument the checkout. Before you sign anything, measure your own failed cashless attempt rate against the 25 percent national figure and your cash rejection impact against the 94 percent acceptance norm, because those two numbers, not the market-size headlines, decide what the mandate of 2027 will cost your specific store. Data basis Payment behaviour shares, acceptance rates, failure rates and attitude figures come from the Deutsche Bundesbank’s payment behaviour study for 2025, fielded from 8 September to 2 December 2025 with about 6,000 participants keeping three-day diaries. girocard volume, value, terminal count and contactless figures are first-half 2026 programme data as recorded in this project’s payments dataset from trade sources. Fee comparisons, 0.2 percent girocard, 2.1 to 2.4 percent international cards, 2.3 percent cash all-in, are 2025 industry cost-study estimates, not published tariff schedules. PayPal and wallet shares are from the same Bundesbank study. Wero user counts, membership and rollout dates are EPI and press disclosures from March to September 2026. The 2027 merchant mandate is from finance ministry planning as reported by Deutsche Welle; the bill’s final text was not available at writing. Limitations Cost figures are study estimates with unstated merchant-size assumptions. Wero user numbers are self-reported programme figures. The mandate bill is draft and its scope may change. Digital euro costs are contested between industry and ECB estimates. Sources Deutsche Bundesbank , Payment behaviour in Germany in 2025, press release, 2026 Deutsche Welle , Germany plans to mandate electronic payment options at the checkout, 2026 (in Chinese) Convera , The European Payments Initiative in 2026: what’s changed, 2026 ClearingPost , New merchant interest in Wero as EPI reaches 45 members, April 2026 Wero , iDEAL to Wero transition guide for merchants, 2026 The FinRate , Europe’s payment sovereignty problem: why the EU is building its own rails, 2026 About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
The Gulf Is Not a $585 Billion E-Commerce Market, and It Is Not a $22 Billion One Either SeaPRwire

The Gulf Is Not a $585 Billion E-Commerce Market, and It Is Not a $22 Billion One Either

IMARC pegs GCC e-commerce at $584.8 billion for 2025; SAMA’s own data shows why that figure and its low-ball rivals both fail A figure has been traveling through the Gulf e-commerce conversation for over a year now, and it has picked up authority with every hop. The IMARC Group’s GCC E-Commerce Market report, last updated 23 June 2026, states: “The GCC e-commerce market size reached USD 584.8 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 2,081.1 Billion by 2034, exhibiting a growth rate (CAGR) of 15.15% during 2026-2034.” Aggregator sites copy the sentence, strip the hedging, and produce headlines like “GCC e-commerce: a 585 billion market on the rise.” At the other end of the range sits a rival estimate from Eternity Insights, which puts the same market, same region, same base year, at $22.52 billion. If both figures were merely rough, they would not differ by a factor of twenty-six. One of them is not describing the market the others describe, and neither has ever been reconciled against the only institutions that count actual card transactions. Saudi Arabia’s central bank does count them, every month, and its numbers are public. Put the two research figures next to the transaction record and both collapse: the $585 billion claim fails upward, the $22 billion claim fails downward, and the defensible range sits in between, anchored by data nobody in the debate appears to have opened. The claim, as it circulates The IMARC number deserves the respect of exact quotation, because its circulation depends on paraphrase. The report page states a 2025 market of $584.8 billion, a 2034 forecast of $2,081.1 billion, and a 15.15 percent compound growth rate. It does not state a national breakdown on the public page, does not name a methodology, and does not reconcile with any central-bank series. The forecast is internally consistent arithmetic: 584.8 multiplied by 1.1515 to the ninth power gives 2,082, matching the published endpoint to the roundiess of a rounding error. The base, not the growth math, is the problem, and the base has never been shown working. The claim has traveled far enough to leave a trail. A September 2026 statistics roundup built its headline directly on it. Aggregators quote it without the forecast, as if $584.8 billion were an observed market size rather than one consultancy’s unreconciled estimate. Nothing in the public record shows the figure being retracted, revised, or defended with data. It simply repeats. Saudi Arabia’s own ledger The Saudi Central Bank publishes what market research firms estimate. Its 2025 payment statistics, as reported through financial-market channels, give the following record for the Kingdom: SAMA metric, 2025 Value Change vs 2024 E-commerce sales through Mada cards SAR 325.2 billion +65% E-commerce transactions through Mada 1.77 billion record level Point-of-sale sales SAR 707.2 billion +6% Cash withdrawals from ATMs SAR 537.5 billion -3% Total consumer spending (POS + e-commerce + withdrawals) SAR 1,569.9 billion +11% Bank cards issued 63.6 million expansion Source: Argaam , reporting Saudi Central Bank data for 2025 The first row is the one that matters. Mada is the domestic debit scheme, and its e-commerce series counts online purchases made with Mada cards on websites and apps, explicitly excluding Visa, Mastercard and credit-card networks. At the prevailing conversion rate, SAR 325.2 billion is about $86.7 billion of online spending through one domestic card scheme alone. That single figure exceeds the entire GCC market as estimated by Eternity Insights, by nearly four times, before any other country or any other card network is counted. A total-market estimate smaller than one country’s partial payment channel is not a conservative estimate. It is a broken one. The same ledger keeps the $585 billion claim honest from the other side. Add up what the Kingdom actually transacts: SAR 707.2 billion at point of sale, SAR 325.2 billion in Mada e-commerce, SAR 537.5 billion withdrawn in cash, for 1.57 trillion riyals of total consumer spending, about $418 billion across every channel including cash. E-commerce through Mada is roughly 21 percent of tracked consumer spending, and a slice of online spending runs through international cards not in the Mada series. For GCC-wide e-commerce to reach $584.8 billion, the five smaller Gulf states would need to out-consume Saudi Arabia several times over, or online spending would need to be running at levels the central bank’s own POS and withdrawal data make invisible. Neither is plausible on any public record. Sizing the region: floor, band and verdicts Estimate Value for 2025 Source type Verdict against SAMA data IMARC, GCC e-commerce $584.8 billion consultancy, unreconciled 4-5x the plausible GMV band Eternity Insights, GCC e-commerce $22.52 billion consultancy, unreconciled below Saudi’s Mada-only floor Saudi market, Statista-type figures $16.68 billion secondary aggregate below Saudi’s Mada-only floor UAE market, Statista-type figures $8.39 billion secondary aggregate plausible for a “revenue” scope Saudi Mada e-commerce alone about $86.7 billion central bank, transaction record hard floor for the Kingdom’s GMV Source: compiled from IMARC , Eternity Insights , Argaam and secondary aggregators as marked Build the range from the floor up, since floors survive scrutiny and estimates do not. Saudi Mada e-commerce gives the Kingdom at least $86.7 billion of online GMV in 2025. International card networks and credit cards add an unknown but positive amount, so Saudi Arabia’s true online total is higher, not lower, than the Mada floor. The UAE contributes a market that commissioned research puts between $8.4 billion and $12.3 billion depending on scope, and the remaining four Gulf states add something in the low tens of billions between them. The arithmetic lands the GCC’s defensible online GMV somewhere around $120 billion to $150 billion, possibly more if international-card e-commerce in the Kingdom is large. The honest statement is a band, not a point, and the band has a floor made of counted transactions and a ceiling constrained by the Kingdom’s entire tracked consumer spending. Which raises the question of what the $16.68 billion Saudi figure, the one circulating in investor decks as recently as this quarter, is actually measuring. A “market revenue” scope that counts platform commissions and net sales rather than gross card payments would sit far below GMV, and the Mada data makes the gap measurable: the Kingdom’s Mada-only online spend is roughly five times the widely copied national “market size.” That is a scope difference hiding inside a number that gets quoted as if it were one economy. Until a research firm publishes its reconciliation, each of these figures is a hypothesis about definitions wearing the costume of a measurement. The monthly ledger keeps scoring the same way The 2025 annual data is not a one-off print that a revision could flatten. The Saudi Central Bank’s August 2026 bulletin repeats the pattern at monthly frequency: Mada e-commerce sales reached SAR 36.95 billion in the single month, up 26 percent year on year, on 196.9 million transactions, up 27.3 percent. Point-of-sale sales grew about 5 percent in the same month, which means online spending through the domestic scheme is growing roughly five times faster than in-store spending. Electronic methods accounted for 85 percent of Saudi retail payments in 2025, up from 79 percent in 2024, and the Kingdom’s instant-payment system processed 93.7 million transactions worth SAR 96.87 billion in the bulletin month, with value up 21 percent. Every one of these numbers is a counted transaction, not a modeled one, and every one of them is inconsistent with a $22 billion regional market. Claims that survive contact with one month of central-bank data get tested again the next month; claims that have never survived contact with any month do not deserve the benefit of the doubt. The forward projections circulating alongside the market-size claims fail the same test from the other end. The Statista-type national figures project Saudi Arabia reaching $24.29 billion and the UAE $10.56 billion by 2029, which implies roughly 6 to 8 percent compound growth off their own 2025 bases. That growth assumption is defensible against a market whose central bank reports e-commerce transactions growing 27 percent a year, in fact it looks conservative, since 27 percent transaction growth at flat ticket sizes would outpace it. But pair those projections with a 2025 base of $16.68 billion and the models are projecting a market that the payment data says already exists today, at four times the size. The projection layer is fine; it is the base year underneath it that never got checked against the transaction record. How UAE shoppers actually pay, in the same record The payment-side data also matters to anyone sizing or serving this market, and it comes from commissioned research rather than central banks, which is exactly why it should be quoted with its denominator attached. For the UAE in 2025: Payment method (UAE online shoppers, 2025) Share of shoppers using it Prior year Credit or debit card 87% 93% in 2024 Cash on delivery 67% 70% in 2024 Digital wallet 52% 53% in 2024 Bank transfer 35% 37% in 2024 Source: Adjoltz , citing EZDubai and Euromonitor research, September 2026 (secondhand) Shoppers could select multiple methods, so the column sums past 100 percent by design, and the declines in card and wallet usage alongside a rise in COD’s persistence tell a story the single-number summaries miss: checkout is not converging on one method, it is fragmenting across four, with cash stubbornly attached to the delivery step rather than the payment step. Free delivery, wanted by 51 percent of UAE shoppers, outranks every payment feature; the option to pay cash on delivery, wanted by 36 percent, outranks 30-minute delivery. A market-entry plan that treats payment as a solved problem, either because a card network says COD is below 15 percent of transactions or because a wallet vendor says cards are at 87 percent, is solving a problem the shopper is not complaining about. Where the chain breaks The claim has three links and the first one is already broken. The IMARC base of $584.8 billion has no public methodology, no national breakdown, and no reconciliation with the transaction records of the region’s central banks. The second link, the 15.15 percent growth rate, is genuine arithmetic but compounds from the broken base, so it inherits the failure. The third link, the $2,081.1 billion 2034 forecast, is arithmetic on arithmetic. Nothing downstream of an unreconciled base can be rescued by clean compounding. The alternative explanations deserve listing, because one of them might have been true with better disclosure. The figure could include B2B e-commerce alongside consumer retail, which would inflate the total by tens of billions. It could include travel, food delivery and digital services, categories some research houses fold into “e-commerce” and others exclude. It could be a transcription error that metastasized, since the Middle East and Africa’s entire e-commerce for 2025 has been estimated at around $146.9 billion by other aggregators, and a figure six times the continent’s total would require the Gulf to be a statistical continent of its own. Each explanation is possible. None is checkable, which is precisely the objection: a claim that cannot be checked against the transaction record should not be quoted to three significant figures. What a defensible estimate would have to contain The criticism above is only useful if it names the standard the claim fails, so here is the standard. A defensible GCC e-commerce market estimate needs four things, none of them exotic. It needs a scope statement that says whether travel, food delivery, digital services and B2B transactions are inside the number. It needs a national breakdown, because the Gulf’s six economies do not move together and a regional total without country rows cannot be checked against any single central bank. It needs a reconciliation table, even one page long, showing how its totals relate to the transaction data the region’s central banks publish monthly. And it needs to state whether the figure is gross merchandise value or net revenue, since the Saudi evidence shows those two scopes differ by a factor of five within a single country. IMARC’s public report page contains none of the four. Eternity’s contains none of the four. That is not an accusation of fabrication; it is an observation that both documents ask to be quoted as measurements while omitting the disclosures that make quotation safe. The circulation pattern amplifies the problem. Aggregator sites strip the forecast and the hedge words, reducing a consultancy paragraph to a single number, then a second site cites the first, and within a season the number has the authority of common knowledge without ever having passed through a check. The Saudi figure has been through this cycle too, which is why both the inflated and the deflated versions feel familiar to anyone covering the region. Provenance does not survive aggregation, and in a market where the authoritative source is free, monthly, and public, quoting a paid estimate without reconciliation is a choice, not a necessity. The related misconceptions worth breaking The claim that cash on delivery is dead in the Gulf. Commissioned UAE research says 67 percent of online shoppers used cash on delivery in 2025, down from 70 percent in 2024, and 36 percent of UAE shoppers say the availability of COD influences where they shop. A separate survey commissioned by a major card network says COD has fallen to less than 15 percent of total e-commerce transactions. Both claims circulate; both can be simultaneously true, because the first counts people and the second counts transactions, two denominators that produce different numbers from the same behavior. If COD were actually dead, a third of shoppers would not be choosing stores by its availability. The claim that Saudi Arabia is 85 percent cashless and therefore payments are a solved problem. The 85 percent figure, up from 79 percent in 2024, is the central bank’s share of retail payment transactions made by electronic means, a POS-heavy metric that says little about the online checkout, where COD persists in the usage numbers above. Unless the metric being quoted matches the decision being made, the number flatters the infrastructure and misleads the operator. The claim that since every figure is an estimate, any figure is as good as another. The distinction that matters is not precision but provenance. Central-bank card data counts settled transactions and can be audited against its own monthly series. Consultancy market sizes are models that must be reconciled to those records before they deserve quotation. The Gulf debate keeps failing because it treats the second kind of number as if it had the properties of the first. What would prove this wrong A single document would settle this, which is why the claim is worth pressing rather than ignoring. If IMARC, or any research firm, publishes a national breakdown whose GCC sum reaches roughly $585 billion while reconciling with the Saudi Central Bank’s Mada e-commerce series and the UAE’s official market data, this article is wrong, and the interesting story becomes whatever definitions produce such a total. The check is cheap: the next edition of the report, due with 2026 base-year figures, should be opened against the central-bank series before its headline is quoted. The number that would settle this is a country table, and it has been missing from the public record since the claim started circulating. Computation SAR 325.2 billion at about 3.75 riyals to the dollar gives roughly $86.7 billion, the Mada-only floor for Saudi online GMV in 2025. Growth check: 1.1515 raised to the ninth power is 3.56, and 584.8 multiplied by 3.56 gives 2,082, matching the published 2034 forecast, so the growth arithmetic is sound and the base is the defect. Range check: Saudi floor $86.7 billion, plus UAE $8.4 billion to $12.3 billion, plus a low-tens allowance for the four smaller states, gives roughly $120 billion to $150 billion of plausible GCC GMV. IMARC’s figure sits 4 to 5 times above the band’s midpoint; Eternity’s sits below the Kingdom’s floor alone. Total consumer spending in the Kingdom, 1.57 trillion riyals or about $418 billion including cash withdrawals, caps what any all-channel estimate should imply. Limitations The riyal conversion uses an approximate peg rate. The Mada series excludes Visa, Mastercard and credit cards, so the Saudi floor understates total online GMV by an unknown margin. The UAE market figures are commissioned research and secondary aggregates, not official statistics. The Middle East and Africa total cited for scale is itself a low-confidence aggregate. No IMARC methodology was available at writing. Sources IMARC Group , GCC E-Commerce Market report, updated 23 June 2026 Eternity Insights , GCC E-Commerce Market report, 2026-2035 forecast Argaam , Saudi consumer spending rises 11% to SAR 1.57T in 2025, 2026 Arab News , 8 things SAMA’s latest report reveals about a changing Saudi Arabia, 2026 Adjoltz , UAE e-commerce statistics, citing EZDubai and Euromonitor, September 2026 (secondhand) AMC Insights , GCC e-commerce statistics 2026: a 585 billion market on the rise, 4 September 2026 (secondhand) About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
China’s Trade Grew 18.8 Percent. Its Surplus Grew 3.4: Reading the Q1-Q3 2026 Customs Ledger SeaPRwire

China’s Trade Grew 18.8 Percent. Its Surplus Grew 3.4: Reading the Q1-Q3 2026 Customs Ledger

Q1-Q3 2026 customs data: 39.94 trillion yuan traded, 6.46 trillion surplus, and why the two growth rates differ by 15 points 39.94 trillion yuan. That is the number China’s General Administration of Customs put on the board on 14 October 2026 for the first three quarters of goods trade, up 18.8 percent year on year, the fastest pace for the period in five years. Exports came to 23.2 trillion yuan, up 16.4 percent; imports came to 16.74 trillion yuan, up 22.3 percent. The headline circulated globally within hours, and most coverage stopped where the presser stopped. The ledger deserves one more pass, because the four published numbers do not all move together. 18.8 percent of total trade is not 18.8 percent of anything a trader or a policymaker actually pockets. The surplus, the number that dominates the political conversation, grew roughly 3.4 percent in yuan terms over the same period, computed from the customs totals themselves. Both figures are correct. They answer different questions, and the 15-point gap between their growth rates is where the actual story of 2026 sits. The official claim, verbatim At the State Council Information Office presser, customs deputy head Wang Jun stated: this year’s first three quarters, goods trade imports and exports 39.94 trillion yuan, up 18.8 percent year on year; exports 23.2 trillion yuan, up 16.4 percent; imports 16.74 trillion yuan, up 22.3 percent. He added that imports grew 5.9 percentage points faster than exports, that September alone reached 5.16 trillion yuan, the first month ever above the 5-trillion mark, up 27.5 percent, and that quarterly growth accelerated from 15.3 percent in Q1 to 18.3 percent in Q2 to 22.3 percent in Q3. All of that is quoted here as published. The task is to check whether the pieces cohere, which denominators each number silently assumes, and where two correct figures start to tell different stories. Checking the arithmetic: the base year holds Every growth rate customs published is year on year, in yuan terms, for the period January through September 2026. The 2025 base is therefore recoverable from the published figures themselves, by dividing rather than by hunting for last year’s presser. Divide 39.94 trillion by 1.188 and the implied base is 33.62 trillion. Divide 23.2 trillion by 1.164 for exports and the implied base is 19.93 trillion. Divide 16.74 trillion by 1.223 for imports and the implied base is 13.69 trillion. The three implied bases sum to 33.62 trillion, matching the total’s implied base to the second decimal. The ledger is internally consistent; no published rate contradicts another. Metric (Q1-Q3 2026) Published value Published YoY growth Implied 2025 base (computed) Consistency check Total goods trade 39.94 trillion yuan 18.8% 33.62 trillion yuan equals sum of parts Exports 23.2 trillion yuan 16.4% 19.93 trillion yuan sums to total base Imports 16.74 trillion yuan 22.3% 13.69 trillion yuan sums to total base Trade surplus (computed: exports minus imports) 6.46 trillion yuan about 3.4% (computed) 6.24 trillion yuan (computed) derived, not published September single month 5.16 trillion yuan 27.5% 4.05 trillion yuan first month above 5 trillion Source: computed from figures in the customs press conference transcript , 14 October 2026 One computed row needs its denominator flagged before anyone quotes it. The surplus line is not a customs-published growth rate; it is the difference of two published totals in each year, so its 3.4 percent inherits rounding from both. Roughly is doing real work in that row. The direction, however, is robust: imports outgrowing exports by 5.9 percentage points mechanically compresses surplus growth far below trade growth, and no plausible rounding reverses a gap that wide. Three denominators, three different stories The same 18.8 percent total decomposes very differently by partner block, and the presser’s own numbers supply the pieces. Trade with free-trade-agreement partners reached 19.55 trillion yuan, up 30 percent. Divide that by 1.30 and the base is 15.04 trillion, an increment of 4.51 trillion yuan. The total increment of trade across the whole ledger is 39.94 minus 33.62, which is 6.32 trillion. The FTA-partner increment is 71.4 percent of the total, which is what the presser means by the phrase that FTA partners contributed over seventy percent of the trade increase. The claim checks out, and it is the most consequential sentence in the release: growth is concentrated, not broad. Partner bloc (Q1-Q3 2026) Value YoY growth Implied increment Share of total increment (computed) FTA partners 19.55 trillion yuan 30% 4.51 trillion yuan about 71% ASEAN 6.84 trillion yuan 22.7% 1.27 trillion yuan about 20% APEC other economies 24.07 trillion yuan 23.9% 4.64 trillion yuan overlaps FTA figures EU 4.78 trillion yuan 8.4% 0.37 trillion yuan about 6% United States 3.18 trillion yuan 4.1% 0.13 trillion yuan about 2% Source: computed from the customs press conference figures as republished by People’s Daily Overseas Edition Read the last two rows against the first. The US line grew 4.1 percent in a year when total trade grew 18.8 percent, which means trade with the United States shrank as a share of the ledger for the fourth straight structural shift, and the phrase used in the official readout, that US trade “continued to recover”, is doing quiet work: 4.1 percent is recovery the way a tide recovering from low tide is high tide. The APEC row overlaps the FTA row, since several FTA partners are APEC members, so the two increments cannot be summed; the table computes each bloc’s share against the whole anyway, and the overlap is flagged in the row itself rather than hidden. The export-composition story is the same shape. Equipment manufacturing contributed nearly ninety percent of the export increment. Integrated circuit exports grew 99.1 percent. Electric vehicles grew 72.3 percent, lithium batteries 36.4 percent, wind turbine sets 22.4 percent. Robot components, electronic parts, computer parts and electrical equipment together crossed 10 trillion yuan in combined imports and exports, up 58.9 percent, and the presser credits that basket with 11.3 percentage points of the total trade growth, meaning two thirds of the 18.8 percent came from one basket of goods. That is a concentration ratio, and the denominator, total trade growth, is the same one the headline uses. The yuan-dollar seam 39.94 trillion yuan converts to “about 5.94 trillion US dollars” in Xinhua’s English dispatch. Divide 39,940 billion by 5,940 billion and the implied reference rate is 6.72 yuan per dollar. But customs also maintains a surplus series in dollars, and 938.11 billion dollars against a computed yuan surplus of 6.46 trillion implies 6.89. September’s single-month surplus of 133.53 billion dollars against a computed September surplus of about 0.90 trillion yuan implies 6.74. The range across the three implied rates runs from 6.72 to 6.89, roughly a 2.5 percent spread. This is not an error, and calling it one would be the classic mistake of treating a denominator difference as a contradiction. Customs’ dollar-denominated series is converted at period-average market rates transaction by transaction, while a single-point conversion of a trillion-yuan aggregate picks one rate for nine months of flows. The seam matters anyway, because anyone who computes “the surplus in dollars” by multiplying the yuan figure by a spot rate will land somewhere between 930 and 960 billion dollars depending on the week they pick. The defensible statement is the customs series itself: about 938.1 billion dollars of surplus for the first three quarters. Anything more precise than that is a rate assumption wearing a number’s clothes. What the ledger says against the plan targets The customs release lands in the opening year of the 15th Five-Year Plan, and the plan’s headline numbers share the ledger’s weakness for compressed denominators. Three of them repay the same arithmetic. About 3.8 percent. That is the 2026 annual target for cutting carbon dioxide emissions per unit of GDP, set in the government work report. Compound it: 0.962 to the fifth power is 0.824, so five consecutive years at 3.8 percent delivers a cumulative 17.6 percent reduction, comfortably clearing the plan’s binding 17 percent target for 2030 against 2025. The 3.8 percent itself is not arbitrary; the 14th plan period delivered about 17.7 percent cumulatively, which averages 3.8 percent a year, so the opening-year target extends proven pace rather than promising acceleration. The chain behind the 17 percent, from the 2022 carbon-intensity data through the Tsinghua estimate that 2025 landed near a 58 percent cumulative decline against 2005, leaves almost exactly the 17-point gap the plan commits to. The arithmetic is coherent at every link. About 7 percent. That is the plan’s required average annual growth for nationwide research and development spending, with the plan’s growth target expressed only as a “reasonable range” and major analysts working from a 4.5 to 5.0 percent GDP assumption. R&D growing 7 percent against GDP growing 4.75 percent compounds to a relative gain of about 11 to 13 percent in R&D intensity over the plan period, depending on where GDP lands in the range. The range is wide because the denominator is a forecast, not a target; the plan deliberately left GDP unquantified, so intensity outcomes will inherit whatever growth actually happens. About 10 percent, separately, is the plan’s cut in energy consumption per unit of GDP, against the 17 percent carbon-intensity cut, and the gap between those two numbers is the plan’s implicit bet on grid decarbonization: carbon falls faster than energy only if the fuel mix changes. Roughly 4 to 1. That is the ratio of trade growth to GDP growth in 2026, 18.8 percent against the 4.5 to 5.0 percent assumption. Trade has grown faster than GDP in most open economies, but a four-to-one multiple sustained for three consecutive quarters, with quarterly growth accelerating into the year rather than fading, raises the base-year question this article cannot resolve from the released figures: the 2025 comparison base would need its own full accounting to separate genuine acceleration from recovery arithmetic. The presser asserts the pace is the fastest for the period in five years, which implies the bases were not uniformly easy, but “fastest in five years” is a claim about rank, not about decomposition. Who actually holds the ledger The presser supplies one more decomposition that rarely makes it into the coverage: who the traders are. Private enterprises ran 22.73 trillion yuan of trade, up 19.1 percent, holding 56.9 percent of the total, which keeps them the largest trading entity in the country. Foreign-invested enterprises ran 11.69 trillion yuan, up 19 percent, and state-owned enterprises ran 5.46 trillion yuan, up 17.8 percent. Three ownership classes, three growth rates, and the spread between the fastest and the slowest is only 1.3 points, which is itself informative: the 18.8 percent total is not an artifact of one class surging while another shrinks. Roughly the same speed applies across all of them, so the concentration story told above is about products and partners, not about who owns the freight. Ownership class (Q1-Q3 2026) Trade value YoY growth Share of total Private enterprises 22.73 trillion yuan 19.1% 56.9% Foreign-invested enterprises 11.69 trillion yuan 19.0% about 29% State-owned enterprises 5.46 trillion yuan 17.8% about 14% Source: computed shares from the customs press conference transcript , 14 October 2026 The geography row of the release splits the same way. Central region trade grew 20.5 percent and the western region 25.7 percent, both faster than the national total, which the presser attributes to the China-Europe freight trains and the New Western Land-Sea Corridor. A coastal-concentrated trade boom would look different in the interior lines than what was published; the interior is growing faster than the coast, or at least faster than the national average, which narrows one common objection, that the 18.8 percent is a port-volume illusion confined to a few coastal hubs. Two more facts from the same release belong in any quotation of the headline. The first: exports of intermediate goods exceeded half of total export value, which the presser frames as the stabilizing anchor of global supply chains, and which is the structural reason the trade number moves with global manufacturing demand rather than with final consumer sentiment. The second: monthly growth stayed in double digits for six consecutive months through September, with the September single month at 5.16 trillion yuan, up 27.5 percent, and September exports alone at 3.03 trillion yuan, up 29.6 percent. Quarterly acceleration from 15.3 to 18.3 to 22.3 percent is therefore not a rounding artifact of one strong month; the September peak sits on top of a rising quarterly path. Any reading that treats the 18.8 percent as a fluke of the September print has to explain away five earlier months at the same order of magnitude. Verdict: what holds and what does not Everything customs published coheres. The implied bases sum correctly, the FTA increment share recomputes to 71.4 percent against the claimed “over seventy percent”, the monthly and quarterly acceleration figures stack, and the plan’s carbon arithmetic compounds to clear its binding target with margin. None of the four checked number groups contains a mathematical contradiction, and the one seam that exists, the yuan-dollar conversion spread, is a denominator choice rather than a mistake. What the release does not advertise is composition. About 71 percent of the trade increment came from FTA partners. About two thirds of the growth came from one basket of tech-heavy goods, inside which integrated circuits doubled. The surplus, the number that dominates foreign-policy coverage, grew about 3.4 percent in yuan terms while the headline grew 18.8 percent, because imports outgrew exports by 5.9 points. A reader who takes only the headline will overestimate the surplus story and underestimate the concentration story, and both errors push in the same direction: toward treating a broad-based boom from a narrow-based one. The ledger supports the narrower reading. Whether the narrow base can keep compounding at 99.1 percent annual rates for integrated circuits is the question the fourth quarter will start answering. Methodology Source hierarchy: customs presser and People’s Daily first, Xinhua second, plan analyses third. Denominators: all growth rates year on year, yuan terms, January-September 2026 unless stated. Derived values: 2025 base = 2026 value divided by (1 + growth); surplus = exports minus imports, yuan terms; increment shares against total increment. USD series treated as customs’ own dollar statistics, not conversions of the yuan series. Conversion checks: implied rate = yuan value divided by dollar value, across total, Q1-Q3 surplus and September surplus. Cross-validation: FTA increment share recomputed against the official “over seventy percent” claim; component bases summed against total base. Plan checks: the 3.8 percent carbon target compounded against the 17 percent binding cumulative target; R&D intensity growth computed across the GDP assumption range. Falsification: any recomputation changing a verdict, or a later base-period revision, overturns this audit. Limitations The 2025 base is recovered arithmetically and inherits rounding from four published figures. Surplus growth is computed, not published. “Fastest in five years” is accepted on rank authority. Plan-target arithmetic assumes annual rates persist uniformly. Sources General Administration of Customs of China , Press conference transcript, imports and exports of the first three quarters of 2026, 14 October 2026 (in Chinese) People’s Daily Overseas Edition, via China Customs , Goods trade near 40 trillion yuan in the first three quarters, 16 October 2026 (in Chinese) Xinhua , China’s foreign trade maintains sound momentum in first three quarters, 14 October 2026 Gov.cn , Reading the 2026 Government Work Report: main indicators of the 15th Five-Year Plan, March 2026 (in Chinese) Securities Times , Answering the 15th Five-Year Plan’s dual carbon-control exam paper, 13 November 2026 (in Chinese) Chinese Embassy in Singapore , National Day op-ed in Lianhe Zaobao on the 15th Five-Year Plan, 1 October 2026 (in Chinese) About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
The Philippines Will Spend $2.45 Billion on Telecoms in 2026. Watch Where It Doesn’t Go SeaPRwire

The Philippines Will Spend $2.45 Billion on Telecoms in 2026. Watch Where It Doesn’t Go

DICT counts $2.21 billion in 2026 telecom capex; DITO pulls back as the Konektadong Pinoy Act’s February rules open the last mile The announcement landed in early September 2026 with the confidence of a milestone: the Department of Information and Communications Technology confirmed that the Philippines’ three largest network builders had collectively committed about $2.21 billion in capital expenditure for the year, a figure that rises to $2.4 billion to $2.45 billion once DITO Telecommunity’s projected spending is added. Secretary Henry Aguda framed the number as a vote of confidence, crossing the $2 billion mark, he said, means the industry believes in the country. The statement was accurate and, in the way official statements usually are, incomplete. A capital expenditure total is a headline, not a forecast. What determines whether this round of spending actually changes the market is not the sum but its composition, and the composition has shifted in two directions at once: the challenger is spending less than it did last year, while a law passed in 2025 has quietly converted the last mile of the network from a franchise-controlled asset into something any qualified company can register to build. On paper, $2.45 billion of telecom investment in a country of 114 million people looks like an expansion cycle. In practice, two variables decide what this money does: the direction of DITO’s build-out, and the pace of registrations under the Konektadong Pinoy Act’s new data transmission framework. This article takes each variable apart, checks what the disclosed numbers actually support, and names the signals that would show the reading is wrong. What the $2.45 billion actually buys The Department’s figures rest on company disclosures and earnings briefings available as of August 2026. Three operators account for the confirmed portion: Operator 2026 capex guidance (peso terms) Dollar equivalent Notes PLDT Inc. about PHP 55 billion roughly $930 million largest single commitment Globe Telecom below PHP 59.4 billion $950 million to $970 million capped guidance Converge ICT PHP 17 billion to 20 billion about $310 million midpoint basis DITO Telecommunity projected $170 million to $250 million included in the $2.4-2.45 billion range below its 2025 level Confirmed total (PLDT + Globe + Converge) about $2.21 billion disclosures as of August 2026 Industry total incl. DITO and others $2.4 billion to $2.45 billion DICT estimate Source: Newsbytes.ph , reporting the DICT statement of 1 September 2026 Three reading notes before the number gets quoted further. First, the $2.21 billion is guidance, not audited spend, the DICT itself flags that the figures “remain subject to changes in the telcos’ spending plans.” Second, the dollar conversions are the Department’s own, at peso-dollar rates that were not published alongside the announcement; the peso ranges (PHP 55 billion, PHP 59.4 billion, PHP 17-20 billion) are the firmer numbers. Third, DITO’s portion is a projection, not a commitment, which is exactly why the spread between the confirmed $2.21 billion and the projected $2.45 billion matters. If DITO spends at the bottom of its range, roughly $190 million of the headline figure is inference. Variable one: DITO is spending less, not more The most telling line in the DICT statement is the one about the challenger. DITO Telecommunity, the third player that entered the market in 2021 and broke the PLDT-Globe duopoly, is projected to invest between $170 million and $250 million in 2026, below the PHP 15 billion to PHP 18 billion (roughly $260 million to $310 million at prevailing rates) it spent in 2025. A challenger cutting capex in its sixth year is not a detail; it is a phase change. DITO’s build-out followed a pattern familiar from other markets with a state-backed entrant: heavy early spending on towers and spectrum to hit coverage obligations, then a taper as subscriber growth must start paying for itself. The 2026 guidance says the taper has arrived. Two consequences follow, and they do not require inside knowledge of DITO’s books to state. The first is competitive. A challenger that stops expanding coverage competes on price with a fixed network. That is good for consumers in the short run and corrosive for everyone’s revenue per user in the medium run. PLDT and Globe are simultaneously being asked to spend at record levels, PLDT’s PHP 55 billion is its largest annual commitment, while a rival whose growth thesis required sustained capex now has room to undercut on price. On paper the industry is investing heavily. In practice, the pricing pressure that follows a challenger’s capex holiday can consume more margin than the capex itself. The second is structural. DITO’s retreat shifts the incremental-coverage burden to the government’s own programs: the National Fiber Backbone rollout and the accelerated implementation of the Konektadong Pinoy Act. The DICT statement lists both alongside the operators’ commitments, and the pairing is not rhetorical. When private capex concentrates in dense, profitable corridors, the unprofitable edges are left to state-funded backbone and to whatever new entrants the open-access regime attracts. Whether the edges get served in 2026-2028 depends far more on those two mechanisms than on the headline number. Variable two: the last mile is now a registration, not a franchise The Konektadong Pinoy Act, Republic Act No. 12234, was passed in 2025; its Implementing Rules and Regulations followed in November 2025. The operational hinge came on 2 February 2026, when the National Telecommunications Commission signed Memorandum Circular No. 002-02-2026, the registration and authorization framework for Data Transmission Industry Participants (DTIPs). The framework’s core move is the abolition of the legislative franchise requirement for data transmission: entities that move data commercially register administratively with the NTC instead of needing a bespoke act of Congress. The circular splits the industry into four segments, each with its own asset floor, and the floors are calibrated to let small players in at the edge while keeping the core capitalized: Segment Minimum asset requirement Certificate validity International Gateway Facility (IGF) PHP 1 billion (about $16 million) up to 15 years Core / Backbone network PHP 100 million up to 15 years Middle mile PHP 10 million up to 10 years Last mile PHP 500,000 (about $8,000) 5 years Source: eLegal Philippines , on NTC Memorandum Circular No. 002-02-2026 A half-million-peso asset floor for last-mile operation is a deliberate policy choice: it prices community networks, cooperatives and small ISPs into the market. The circular adds a “Green Lane” for applications from micro-entities and community-based providers targeting rural and underserved areas, and requires all authorized participants to meet cybersecurity standards, publish annual transparency reports on rates, and file yearly reports, covering investments, coverage, network maps and pricing, to the NTC and the Philippine Competition Commission by 30 April each year. Registrants must also keep a debt-to-asset ratio of no more than 70 percent. In practice, the framework’s first year has produced friction rather than a flood. The DICT issued the IRR in November 2025 and the NTC began transitioning existing licensees in the first quarter of 2026, requiring public telecom entities to declare which segments they occupy. By the third quarter of 2026 the Commission was still running focus-group discussions on where the boundary sits between DTIP-regulated data transmission and the older value-added services (VAS) regime, a boundary question that matters because, as one Manila law firm reviewing the year’s developments put it, potentially most VAS providers necessarily involve data transmission, yet the NTC currently treats internet access and VoIP as DTIP matters while leaving other VAS under the old regime. The precise line remains unsettled. So the second variable is live but unproven. The law has removed the franchise barrier; the registration thresholds are published; the transition clock is running. What has not yet been demonstrated is volume: how many new last-mile registrants have actually appeared since February, and whether any of them are building outside the corridors the big three already serve. That number is the single most informative statistic in Philippine telecom right now, and it is not in the DICT’s capex announcement. The other levers inside the Implementing Rules Registration is the provision that gets the headlines, but the Implementing Rules bundle several mechanisms that bear directly on how the 2026 capex converts into coverage. Each works on a different constraint, and each has a different failure mode. Mandatory infrastructure sharing. Access providers and owners of passive infrastructure, towers, ducts and fiber, must make essential facilities available on fair and non-discriminatory terms. The aim is to stop duplicate builds and lower the capital cost of rollout. The failure mode is pricing disputes: determining what “fair” access costs where the incumbent controls the asset, which is why the rules require published Reference Access Offers and an access list rather than leaving terms to negotiation. A “Dig Once” policy requiring conduit installation during roadworks. Boring fiber ducts while a road is already open is the cheapest civil-works moment a network builder will ever get. The mechanism is cheap on paper and depends entirely on coordination between the Department of Public Works and the telecom side, a coordination the IRR assigns but cannot force. Spectrum reform through a Spectrum Management Policy Framework. The framework must guide allocation, assignment and recall of frequencies, with periodic review and competition-sensitive allocation, and it introduces mechanisms to reclaim underutilized spectrum and reassign it to more efficient users. This is the provision with the longest shadow over the incumbents, because “underutilized” is a judgment an incumbent can dispute but cannot ignore. Fiscal incentives for investment, including tax holidays, duty exemptions and VAT zero-rating, aimed at pulling private capital into underserved and unserved areas. Cybersecurity as a licensing condition rather than a best practice. Registrants must implement recognized frameworks, ISO/IEC 27001, NIST or CIS, establish incident-response protocols, and report major incidents to the national CERT. Compliance is a condition of continued operation. Taken together, the rules try to attack the cost side of rural coverage from four directions at once: cheaper civil works, cheaper access to existing infrastructure, cheaper spectrum, and cheaper taxes. Whether that adds up to cheaper rural networks depends on implementation details the IRR only sketches. BusinessWorld’s legal analysis of the law notes the obvious risk: increased participation does not automatically translate into effective competition, and market fragmentation or continued dominance by incumbents may persist without strong regulatory oversight. The same analysis flags overlapping roles across the DICT, the NTC and the Philippine Competition Commission as a coordination hazard that could fragment regulation. The honest summary of the framework’s first year is therefore asymmetric. The cost-reduction levers are live and do not need new legislation; a new entrant digging once, leasing ducts and claiming incentives can already bank the savings. The competition-creating lever, registration itself, is live but its volume is unproven. That asymmetry is why the registration count, not the incentive take-up, is the variable worth watching. The enterprise revenue line is the quiet tell There is a third, less advertised explanation for why incumbents are willing to spend at record levels while the challenger retrenches: the demand mix has rotated from consumer subscriptions to enterprise data. PLDT’s first-half 2026 results carry the signal. Enterprise revenue reached PHP 24.8 billion, with corporate data and ICT services contributing PHP 18.4 billion of it, and PLDT Global’s revenue grew 30 percent year on year as the company expanded its role in regional connectivity. Growth of that shape is not driven by household broadband plans; it tracks data-center traffic, cloud interconnection and the AI build-out that the DICT’s own announcement cites as downstream beneficiaries of better networks. PLDT metric, first half 2026 Value Enterprise revenue PHP 24.8 billion Corporate data and ICT revenue PHP 18.4 billion PLDT Global revenue growth, year on year 30 percent Source: figures as recorded from PLDT disclosures; see Light Reading for the 2026 capex context The enterprise tilt also explains the international-infrastructure line item that gets least attention: a proposal for a $500 million domestic subsea cable, with an expected completion window of 24 months once begun. Domestic subsea capacity is an odd-sounding priority for an archipelago until the demand mix is considered, inter-island enterprise backhaul between Luzon, Visayas and Mindanao data centers is exactly the constraint that consumer-facing metrics never surface. A 24-month build clock means a decision taken in 2026 lands in 2028, which makes the capex-guidance number for this year a poor predictor of what the network looks like when the AI and data-center demand actually arrives. It depends on which revenue line you believe is permanent. If enterprise data growth is a durable rotation, incumbent capex at PHP 55 billion-plus levels is rational maintenance of a margin engine, and the headline $2.45 billion is not expansion so much as re-platforming. If it is a cycle peak, AI infrastructure demand cooling the way it has cooled elsewhere, the same spending becomes stranded-capacity risk, and DITO’s caution starts to look like the sharpest read in the market. Who gets hit first, and in what order The restructuring does not land on all participants at once. Ordering the exposure by mechanism rather than by size: VAS providers face classification risk first. The unsettled DTIP/VAS boundary means companies that thought they were lightly regulated content or platform service providers may wake up registered as data transmission participants, with asset floors, cybersecurity certification and annual reporting attached. The Q3 2026 focus-group process will decide how wide that net is cast. Incumbent last-mile operators in dense urban districts are exposed second, and only if registration volume materializes. A PHP 500,000 threshold invites entrants precisely where revenues are richest; in provincial markets, the Green Lane’s community-network track is the realistic challenger, and its pace is grant-dependent. DITO’s own retail position is exposed third, from the opposite direction: a challenger freezing network growth while rivals monetize enterprise demand will either need a price war, which its cut capex suggests it is preparing for, or a niche strategy the guidance does not reveal. Spectrum holders are exposed last and most slowly, through the Spectrum Management Policy Framework the IRR mandates, including mechanisms to recall underutilized frequencies and reassign them. Recall authority changes behavior long before it is used. Two leading indicators carry most of the information. The first is the NTC’s registration count by segment, ideally published monthly: a registry that crosses even a few dozen last-mile registrants within a year of the circular would validate the open-access thesis; a registry that stays in single digits by mid-2027 would show the threshold was not the binding constraint. The second is DITO’s 2027 guidance: another year of sub-$300 million spending confirms the taper as strategy rather than timing, and forces a repricing of the competitive intensity every incumbent model assumes. The reading fails under two conditions This conclusion fails when either variable moves the other way. If DITO’s 2027 guidance reverses, a return to PHP 15 billion-plus spending, presumably tied to new funding or a coverage mandate, the “challenger retrenchment” leg collapses, and the capex composition argument inverts into a renewal of the build-out race. If the NTC’s DTIP registry shows hundreds of active last-mile operators serving areas the big three had abandoned, the “friction rather than flood” leg collapses, and the Konektadong Pinoy Act becomes the story rather than the footnote. Both numbers are public or will be; neither requires special access to check. Anyone quoting the $2.45 billion headline without them is quoting a milestone, not a trend. Data basis The capex figures come from the Department of Information and Communications Technology’s statement of 1 September 2026, which consolidated company disclosures and earnings briefings as of August 2026; they were cross-checked across five independent reports of the same announcement (Newsbytes.ph, Telecom Review Asia, Communications Today, Developing Telecoms, Context.ph), which agree on all figures. The regulatory framework rests on Republic Act No. 12234, its Implementing Rules and Regulations of November 2025, and NTC Memorandum Circular No. 002-02-2026 signed 2 February 2026, as summarized by two Philippine legal analyses. PLDT’s first-half 2026 enterprise figures and the subsea cable proposal are as recorded in the project’s telecom metrics dataset from trade-press reporting. The DITO 2025 spending range is the DICT’s own comparison figure. No operator financial statements were read directly; all numbers are second-hand from disclosure-based reporting. Limitations Dollar conversions are the DICT’s and vary by report. DITO’s 2026 spending is a projection, not a disclosure. The DTIP registration count, the analysis’s key leading indicator, was not available at writing; the registry-based claims are therefore forecasts, not findings. The VAS boundary outcome depends on a regulatory process still in consultation. Sources Newsbytes.ph , PH telco capital spending seen reaching $2.45 billion in 2026, 1 September 2026 Telecom Review Asia , Philippine Telco Sector Lines Up USD 2.2B in 2026 CapEx, September 2026 BusinessWorld Online , Konektadong Pinoy Act: Expanding access, redefining competition, 2026 eLegal Philippines , NTC Sets New Guidelines for Konektadong Pinoy Act, February 2026 Law.asia , Philippine digital regulation: Connectivity, fintech developments, 22 October 2026 Light Reading , Philippine telcos set $2.2B for infrastructure investment in 2026, 2026 About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
Malaysia E&E supply chain: what stays local in 2026 SeaPRwire

Malaysia E&E supply chain: what stays local in 2026

Penang’s new air cargo park is built on a 42-hectare site, with main construction scheduled for the first quarter of 2027 and a Free Commercial Zone warehouse targeted for 2029. The Malaysian Investment Development Authority published those dates on 29 October 2026 in its description of the Penang International Logistics Aeropark (PILA). The project is an institutional response inside the malaysia e&e supply chain: a cargo facility, a digital single window and a dedicated heavy-vehicle lane, all designed around high-value, time-sensitive electronics. Dates here matter more than adjectives. Ground works are under way. The master plan approval is already in hand. The 42-hectare node and its dates PILA was formally established through a joint venture agreement signed on 13 April 2026 between Penang Development Corporation and Malaysia Airports Holdings Berhad, with the first phase executed by Penang International Logistics Aeropark Sdn. Bhd. The published scope gives a first-phase air cargo warehouse inside a Free Commercial Zone, adding 100,000 tonnes of annual handling capacity on completion in 2029. Full build-out is described as more than 2 million square feet of warehouse space with total handling capacity up to 500,000 tonnes per year. Those are engineering figures from an agency page, and they belong in a site file as dated milestones. The supporting systems are as specific. A single-window digital logistics platform is listed for paperless processing. A 24-hour express lane is reserved for strategic cargo tied to new product introduction. A dedicated heavy-vehicle lane is included to cut road vibration that can damage shock-sensitive electronic components. MIDA also lists two incentive instruments in the same description, the Smart Logistics Complex incentive and International Integrated Logistics Services status. Together they tell a freight forwarder what the malaysia e&e supply chain is trying to shorten: transfer time, damage exposure and cost risk on high-value shipments. None of these items requires a company name. Why 30 to 40 per cent of air cargo still moves by road The agency page states that 30 to 40 per cent of air cargo generated in Penang currently moves by road feeder to external hubs before onward flight, because long-haul freighter services to North America and Western Europe are limited. That is a routing fact. It explains why a local cargo park has a business case without requiring any judgement about another market’s policy or efficiency. For the malaysia e&e supply chain, the extra road leg is a cost line before it is anything else. For a logistics planner the number is a baseline: roughly a third of volume carries an extra handover and an extra dwell window. Each handover adds a handling event. Shock-sensitive semiconductor and assembly output is the cargo type the project is designed around, which is why the heavy-vehicle lane and vibration control appear next to the warehouse capacity in the same source. A 24-hour express lane for new product introduction sits on the same logic: a sample or a first batch loses value when it waits for a consolidated flight. The published description frames the project’s objective as shorter transfer time, lower damage exposure and lower freight cost risk. The 2027 Q1 main construction date and the 2029 warehouse target are therefore planning inputs, not available capacity. A team quoting malaysia e&e supply chain capacity from the 500,000 tonnes figure is reading a full-build-out design number as a current operating number. The first-phase commitment is 100,000 tonnes at 2029 completion. What the malaysia e&e supply chain already holds A capability list is more honest than a migration story. The Star’s 31 October 2026 industry account, using official statistics, describes the sector moving from assembly, test and packaging into advanced packaging, equipment, materials, automation, research and IC design. JTM Asia’s 2026-2027 manufacturing overview adds a local automation and inspection equipment cluster around Penang, and records approved investment in machinery and equipment of RM11 billion in 2025 and RM7.5 billion in the first half of 2026. MIDA figures cited there put electrical and electronics, machinery, chemicals, transport equipment and food at 76.9 per cent of approved manufacturing investment in the first half of 2026. On the ground, the segments that can be named from these sources are assembly, test and packaging, printed circuit board and electronics assembly, automation and inspection equipment, precision parts, and warehousing with third-party logistics. Two 2026 facility openings appear in the same overview, one advanced packaging plant commissioned in February at about RM800 million and one wafer-equipment supercentre first phase opened in June with a planned investment above RM400 million. Neither company is named in the summary used here, and no endorsement is implied by listing the amounts. These are capability statements, not company claims. The New Incentive Framework took effect on 1 March 2026, with incentives tied to technology development, skilled employment, local supply chain participation and sustainability metrics, according to the same manufacturing overview. For a supplier deciding whether to qualify locally, that effective date is the line between an older incentive conversation and the current one. It is also the kind of dated rule that belongs beside the engineering milestones in a file on the malaysia e&e supply chain. Where the chain is not local The question behind this topic asked which supporting segments remain local and which have left. The published material contains no direct statistic on facilities relocating out of the country, and no such claim is made here. What the sources do support is a list of chain stages that are not localised, which is where the malaysia e&e supply chain still stops short of a complete stage set: front-end advanced-node wafer fabrication, long-haul intercontinental freighter routes, and a skilled-worker gap. The National Semiconductor Strategy figures in The Star’s account put trained high-skilled workers at more than 18,000 with a target of 60,000, and approved investment at over RM91 billion as of the first quarter of 2026. The 30 to 40 per cent road-feeder figure is the logistics form of the same gap. A cargo park and an FCZ warehouse address handling and customs geography. They do not create a long-haul freighter schedule. A site-selection file that treats the 2029 capacity number as a substitute for route availability has confused a facility with a network. A capability gap is not a departure. Three readings of the export share Electrical and electronics exports rose 42.5 per cent year on year to a record RM467.9 billion in the first half of 2026, close to half of national exports, according to official figures quoted on 31 October 2026. Two other numbers circulate for September 2026. A second-hand account of a monthly external trade release dated 19 October 2026 puts that month’s E&E exports at RM110.23 billion, up 69.2 per cent and equal to 51.2 per cent of total exports. The Ledger Asia’s 30 October 2026 report gives September domestic exports up 54.7 per cent, with E&E products near 46 per cent and up 72.5 per cent. These are three different measurements. The first is a half-year cumulative figure. The second is a single month on a total-export basis. The third is a single month on a domestic-export basis. Publishing bodies and release dates differ as well. Keeping them in separate rows is the minimum standard for anyone quoting malaysia e&e supply chain concentration in a client memo, and the second-hand monthly figure should not carry weight as a load-bearing fact. Read as structure, the numbers still say something useful. When one product category accounts for roughly half of an export base, a change in that category’s order book moves the aggregate without any other sector moving. That is a concentration mechanism, not a forecast. The same 31 October 2026 account records RM6 billion of approved E&E investment in the first quarter of 2026, the highest among manufacturing subsectors, and RM319 billion cumulatively from 2021 to 2025. Both are period-labelled approval figures. What a site-selection file should carry Put the dated items first. The 13 April 2026 joint venture agreement, the master plan approval, the 2027 Q1 main construction slot, the 2029 FCZ warehouse target, the 100,000 tonnes first-phase capacity and the 500,000 tonnes full-build-out design number each need their own row. The 1 March 2026 incentive framework effective date goes in the same table. A file organised this way survives a schedule slip without a rewrite. Then keep the capability list and the gap list separate. Local assembly, test and packaging, board assembly, automation equipment, precision parts and third-party logistics sit on one side. Front-end wafer fabrication, intercontinental freighter routes and the 18,000 to 60,000 skilled-worker gap sit on the other. Neither list is a claim that firms have moved. That is what the malaysia e&e supply chain looks like when the published sources are read as an inventory of stages. Finally, attach the export-share rows with their periods and definitions, and mark the September monthly figures derived from a second-hand account as such. A planner who can point to which half-year or single-month series a percentage came from will not be caught mixing a cumulative rate with a monthly share. For freight forwarders, industrial park teams and equipment suppliers, that discipline is the practical output of this malaysia e&e supply chain review. Sources Malaysian Investment Development Authority (MIDA), “Penang International Logistics Aeropark (PILA)” (29 October 2026). https://www.mida.gov.my/penang-international-logistics-aeropark-pila-powering-the-make-in-penang-fly-from-penang-revolution-in-global-ee-and-semiconductor-logistics The Star, “Advancing Silicon Malaysia” (31 October 2026). https://www.thestar.com.my/starpicks/2026/10/31/advancing-silicon-malaysia JTM Asia, “Malaysia Manufacturing Landscape 2026-2027: Major Industries, Developments & Outlook”. http://jtmasia.com/en/news/malaysia-manufacturing-landscape.html The Ledger Asia, “Malaysia Semiconductor Upcycle Lifts Export and Growth Outlook” (30 October 2026). https://theledger.asia/?p=43493 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Southeast Asia ecommerce GMV: how channels split in 2026 SeaPRwire

Southeast Asia ecommerce GMV: how channels split in 2026

Three published readings of southeast asia ecommerce gmv are routinely placed in the same chart, and they do not describe the same thing. e-Conomy SEA 2026 puts digital economy GMV at US$368 billion for 2026, up 17 per cent, with ecommerce at US$226 billion, up 18 per cent. Momentum Works records 2025 platform ecommerce GMV at US$157.6 billion, up 22.8 per cent, and forecasts content commerce at US$77.9 billion for 2026. This article takes five Southeast Asian markets as its subject and does not assess any single market. The ten-economy coverage of e-Conomy SEA 2026 and the six-market coverage of Momentum Works are cited only as statements of statistical scope. Indonesia, Malaysia and Thailand are within that subject scope. Vietnam and the Philippines complete the five. Neither coverage line is used here to assess a single market. A 2026 forecast and a 2025 actual are different periods. A platform figure and a digital-economy figure are different boundaries. Content commerce is a subset of platform GMV. Where the three channels actually sit The working split in the published material is functional. Shelf-based platform search handles demand that already exists, where a shopper arrives with a product category in mind. Content commerce covers livestreams, short video and affiliate marketing, and it generates demand before a search happens. Owned storefronts appear in the reporting as a retention and inventory-synchronisation requirement, without a separate GMV line. Tech Collective’s 5 November 2026 account of 2027 planning describes three formats with distinct jobs: short video builds awareness, livestreams carry demonstration and question handling, and affiliate links reach audiences a brand already has. That division explains why the phrase channel split misleads when it is read as a market-share table. A single order can pass through a short video, a livestream, a product page and an affiliate link, with the reporting system assigning the sale to one of them. Momentum Works’ 8 September 2026 note on Live Commerce in Southeast Asia 2026 states that not all livestream GMV is incremental, since part of it moves from product pages, short video and affiliate traffic. It asks operators to measure incremental revenue, conversion and acquisition cost instead of view counts or livestream GMV alone. Attribution is an accounting choice, not a new pool of demand. For a team building a 2027 budget, the practical consequence is that southeast asia ecommerce gmv cannot be rebuilt by adding the three channel labels. The US$226 billion line is an economy-wide ecommerce measure. The US$157.6 billion line is platform GMV for 2025 across six markets. The 37 per cent figure is a share of platform GMV in the first half of 2026, up from 20 per cent in 2024. Each carries its own denominator. What the denominator changes Three boundaries separate the numbers. The first is coverage: e-Conomy SEA 2026 expanded to ten Southeast Asian economies in this edition, while the Momentum Works platform series covers six markets. The second is period: US$157.6 billion is a full-year 2025 actual, US$33.8 billion is first-half 2026 content commerce, and US$226 billion is a 2026 full-year forecast. The third is the measured object: digital economy GMV also includes online media at US$44 billion, online travel at US$59 billion and transport and food delivery at US$40 billion. CRN Asia’s 26 October 2026 summary of the eleventh e-Conomy SEA report, published jointly by Google, Temasek and Bain, adds the surrounding categories. Digital financial services gross transaction value is put at US$1.65 trillion, up 16 per cent, with digital lending balances at US$116 billion, up 22 per cent. The same report projects digital economy GMV above US$1 trillion by 2035 and ecommerce at US$409 billion in 2030 and US$820 billion in 2035, implying a compound annual growth rate near 15 per cent from 2026 to 2035. A separate 23 October 2026 account puts 2025 digital economy GMV at US$315 billion and 2030 at US$620 billion. Used carefully, southeast asia ecommerce gmv is a label for three separate series. None of those lines is a platform channel. The 37 per cent share is where most misreading starts. Its denominator is platform ecommerce GMV in the first half of 2026, and the numerator is content commerce within that same platform boundary. A reader who divides US$77.9 billion by US$226 billion has mixed a platform subset with a ten-economy ecommerce total. A reader who compares 37 per cent with the 22.8 per cent growth rate has mixed a share with a year-on-year rate. The published material supports a functional conclusion about how discovery happens. It does not support a claim that shelf listings or owned storefronts lost a measurable GMV amount. This is the first place where southeast asia ecommerce gmv needs a written denominator attached to every use. A share without its base, a half-year figure without its period and a forecast without its scope belong in separate columns of an internal model. Interfaces, documents and where the money is recorded Channel labels become operational only at the interfaces. Payment is one. Xendit’s E-comms Momentum Report surveyed 6,000 online shoppers across six markets and found that about 51 per cent of respondents in Indonesia and 41 per cent in the Philippines had abandoned a cart in the previous three months because a preferred payment method was unavailable. On the same platform, QRIS transaction volume grew 142 per cent between January 2025 and April 2026, while QR Ph and InstaPay volumes in the Philippines grew 198 per cent. The report marks these as single-platform data. Fulfilment is a second interface. Tech Collective’s 2027 outlook says platform commissions, advertising, fulfilment, discounting and returns compress margin, and that profitable growth is taking priority over headline sales. It lists retention, inventory synchronisation and fulfilment efficiency as the areas of focus. Inventory synchronisation is the only published signal in these sources that points at owned storefronts, since a brand running its own site alongside marketplaces needs stock figures that agree across both. Attribution is the third. An AI-hosted livestream is reported to cost roughly 20 to 25 per cent of a human-hosted stream and to generate about 80 per cent of its GMV per hour. Momentum Works marks those ratios as selected cases without general applicability. The number is useful for a cost model and unusable as a market average. Anyone quoting southeast asia ecommerce gmv in a client deck should attach the coverage line before applying a case-study ratio to a regional total. The owned-channel gap No report in the source set publishes a standalone GMV line for direct-to-consumer sites. That absence should be recorded as an absence. Platform share cannot be reverse-engineered to fill it, because a platform share is computed inside the platform boundary and says nothing about sales that never entered a marketplace. The visible signals sit at the payment end, in the abandonment and QR volume figures, and on the merchant side, in the inventory synchronisation requirement. The gap is a measurement gap. It is not evidence of decline. For an agency running cross-border brands, the working answer is to keep a fourth column in the model that stays empty until a client supplies its own first-party order data. That keeps southeast asia ecommerce gmv from being presented as a complete channel map when the published material covers platform and content commerce only. What changes in 2027 planning The e-Conomy SEA 2026 material records 243 million people using generative AI, equal to 58 per cent of the workforce, with 69 per cent of shoppers using AI to compare complex products and 31 per cent of searches being multimodal. It reports that 75 per cent of AI-using respondents would let an agent find the best price and place an order, subject to safeguards, while 72 per cent already use everyday automation and 62 per cent trust it more than a year earlier. The same survey puts privacy protection at 44 per cent and reversibility at 30 per cent among stated conditions. The ASEAN Digital Economy Framework Agreement is expected in November 2026. An agent that places an order changes where attribution lands. Discovery, comparison and checkout can happen away from a product page, which makes the interface question a documentation question. Consent settings, reversal rules and an order record a merchant can reconcile become part of the channel definition. None of these figures is a GMV forecast. Momentum Works’ Ecommerce in Southeast Asia 2026 frames the competitive question as control over demand generation, fulfilment and profit, with 2025 platform GMV close to three times the 2020 level. That framing fits the numbers above. A team that can state which denominator it is using, which period it covers and which interface recorded the sale can compare the three reports without forcing them into one table. How to read southeast asia ecommerce gmv without a false sum A practical reading order helps. Start with the coverage line, then the period, then the measured object. Only after those three are fixed does a comparison between two figures mean anything. Label the US$226 billion forecast as ten-economy ecommerce for 2026, the US$157.6 billion as six-market platform GMV for 2025, and the 37 per cent as a first-half 2026 share inside platform GMV. Then keep the functional map separate from the arithmetic. Shelf search, content discovery and owned storefront retention describe jobs in a chain. The published southeast asia ecommerce gmv figures describe pools of recorded transactions with different boundaries. Adding the three channel labels produces a category error, not a market size. Finally, carry the gaps forward. No source in this set publishes a standalone owned-storefront GMV line, no source publishes a regional average for AI-hosted livestream economics, and the payment abandonment figures come from a single platform’s survey. A 2027 plan that records those three gaps explicitly will survive the next report release with its denominators intact. That is the useful output of reading southeast asia ecommerce gmv across three different reports. Sources Tech Collective, “5 e-commerce trends to watch in Southeast Asia in 2027” (5 November 2026). https://techcollectivesea.com/2026/11/05/e-commerce-trends-southeast-asia-2027/ Momentum Works, “Southeast Asia’s content commerce on track to reach US$77.9B in 2026” (8 September 2026). https://thelowdown.momentum.asia/new-report-southeast-asias-content-commerce-on-track-to-reach-us77-9b-in-2026/ Momentum Works, “Ecommerce in Southeast Asia 2026” (report overview). https://momentum.asia/insights/detail/ecommerce-in-southeast-asia-2026 CRN Asia, “e-Conomy SEA 2026: Southeast Asia’s digital economy to hit US$368bn” (26 October 2026). https://www.crnasia.com/news/2026/artificial-intelligence/e-conomy-sea-2026-southeast-asia-s-digital-economy-to-hit-us Xendit, “E-comms Momentum Report” (survey of 6,000 online shoppers). https://www.xendit.co/en/ecomms-momentum-report/ This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Indonesia PT PMA minimum capital: the 2026 rules SeaPRwire

Indonesia PT PMA minimum capital: the 2026 rules

Under Pasal 26(10) of BKPM Regulation No. 5 of 2025, the pt pma minimum capital floor for a foreign-investment limited liability company in Indonesia is Rp2.500.000.000,00 per company, recorded in the official 698-page PDF as modal ditempatkan/disetor. Pasal 26(2) of the same regulation sets a separate investment-value test above Rp10,000,000,000, computed per five-digit KBLI and per project location with land and buildings excluded. Readers who collapse the pt pma minimum capital figure and the Rp10 billion investment plan into a single number will misread both tests. The two figures come from different paragraphs, answer different questions and carry different filing consequences, so a checklist that tracks only one of them is incomplete from the day the company is registered. A notary working from an older template will also find the paid-up number changed, which is why the article numbers matter as much as the amounts. Who the capital rules apply to Any shareholding by a foreign party makes the vehicle a PMA company, and Law No. 25 of 2007 Article 5(2) requires foreign investment to take the form of a limited liability company incorporated under Indonesian law with its domicile in Indonesia. Article 33 of the same law voids nominee shareholding arrangements, so a local name on the share register does not turn a foreign-funded entity into a domestic one. The pt pma minimum capital rules attach to the company form itself, independent of the nationality printed on a single document. That point is practical, since a nominee agreement gives no fallback when the capital filing is checked against the share register. BKPM / Minister of Investment and Downstreaming Regulation No. 5 of 2025 was promulgated on 2025-10-02 and repealed BKPM Regulations No. 3, 4 and 5 of 2021 at the same time. Under the repealed BKPM 4/2021 the paid-up threshold was Rp10 billion, which is why older checklists still quote that figure. The 2025 text lowered the company-level paid-up floor to Rp2.500.000.000,00 while keeping the Rp10,000,000,000 investment-value test intact. A reader comparing an old engagement letter with a current one will therefore see two different paid-up numbers, and the operative one is the 2025 figure. Law No. 25 of 2007 Article 5(2) also fixes the domicile requirement, which interacts with the project-location test in Pasal 26(2). The company is a single legal entity, yet the investment value is measured per five-digit KBLI and per location, so one company can carry several location-level calculations at once. This is a counting rule, leaving the company-level floor where it is. Two separate capital tests Pasal 26(2) and Pasal 26(9)(10) govern two independent figures. The investment-value test is above Rp10,000,000,000, excluding land and buildings for the business premises, measured per five-digit KBLI and per project location. The paid-up test is the pt pma minimum capital of Rp2.500.000.000,00 per company, unless a sector rule provides otherwise. One test sizes the project, the other sizes the company, and nothing in the text merges the two. The word per in Pasal 26(2) ties the threshold to each KBLI-location pair, so a single company can face the test more than once. A concrete sum shows why the pt pma minimum capital figure cannot stand in for the investment plan. A company that deposits Rp2.5 billion in paid-up capital clears the company-level test. An investment plan totalling Rp9 billion still fails the above-Rp10 billion test, because Rp9 billion sits below the required threshold. Passing one gate says nothing about the other. The deposit is a balance-sheet item, while the investment plan is a project commitment, and the OSS filing asks for both. Both tests must be satisfied on their own terms. Pasal 26(3) and 26(5) change the counting unit by sector. Wholesale and construction use the first four KBLI digits, food and beverage uses the first two digits plus location, while real estate, accommodation, agriculture, plantation, livestock and aquaculture count land and buildings toward the investment value. The pt pma minimum capital floor itself stays at Rp2.500.000.000,00 per company across these variations, so the sector rules move the investment-value total and leave the paid-up floor where it is. The obligation checklist Compliance is a fixed sequence rather than a set of informal practices. A notarial deed establishes the company, the OSS system then issues the NIB, and the company sponsors the investor ITAS, with the KBLI checked in OSS for foreign-investment openness before filing. The pt pma minimum capital deposit, the pernyataan mandiri self-declaration in the OSS format of Attachment I, and the 12-month lock sit inside that sequence as documentary steps. Checking KBLI openness first avoids a filing that has to be rebuilt after the NIB is issued. Pasal 27(1) locks paid-up capital in the company account for at least 12 months from the date of deposit, with exceptions limited to asset purchase, building construction and business operations. Pasal 27(2) and 27(3) set the form of compliance: a self-declaration, or pernyataan mandiri, filed inside the OSS system in the format given in Attachment I. The declaration is a mandatory filing duty under the primary text, and the 12-month lock is a mandatory holding duty, so neither step is left to the discretion of the shareholder. Art. 286 adds a recurring duty, since the LKPM investment activity report is filed quarterly, due by the 15th of the following month for medium and large companies. JCSS Indonesia, reviewed on 2026-10-20, lists the quarterly filing dates as 15 April, 15 July, 15 October and 15 January. The LKPM obligation continues after incorporation and is separate from the one-time capital deposit. Checking the pt pma minimum capital text A secondary source checked on 4 November 2026, published on 5 November 2026 and updated on 10 November 2026, worked without the official text of BKPM Regulation No. 5 of 2025. Its article numbers came from Hukumonline dated 2025-07-18 and Prolegal, and the page carried a note to confirm details with a notary before any transfer. That describes retrieval conditions at the check date and leaves the content of the articles untouched. This batch retrieved the 698-page official PDF directly from the BKPM regulation library and verified the Rp2.500.000.000,00 wording in Pasal 26(10) and the 12-month lock in Pasal 27(1) against the primary text. The pt pma minimum capital figure, the 12-month lock and the pernyataan mandiri form all carry primary-text support, and the self-declaration and the lock are obligations under that text. The official article numbers take precedence over the secondary citation, and the gap is one of access at the original check date. The label Art. 26(9)(10) used in the main source and the Art. 26(10) label used here differ only in citation granularity, since paragraph (9) introduces the minimum-capital rule and paragraph (10) supplies the Rp2.500.000.000,00 amount. The kecuali ditentukan lain wording carries a second consequence: a sector-specific regulation may set a different amount, so the pt pma minimum capital floor operates as a default subject to override. A notary confirming a transfer should therefore read the sector rule alongside the general article. Deadlines, filing windows and the 2026 fee bands Three clocks govern a PMA file. The 12-month lock on paid-up capital runs from the deposit date. The LKPM report falls due by the 15th of the month after each quarter, with 15 April, 15 July, 15 October and 15 January as the filing dates. Government Regulation No. 30 of 2026 took effect on 2026-08-01 and changed incorporation fees to a banded scale based on authorized capital. The four bands are Rp300,000 for authorized capital up to Rp25 million, Rp600,000 above Rp25 million to Rp1 billion, Rp1,500,000 above Rp1 billion to Rp5 billion, and Rp5,000,000 above Rp5 billion. Notary and professional coordination fees commonly run Rp20-60 million, and the 2026 corporate income tax rate is 22 percent. The bands are assessed on authorized capital, which is a figure the parties declare at incorporation. The pt pma minimum capital amount is a deposit into the company. The incorporation fee is assessed on authorized capital as a separate figure, so the two are different line items on a setup budget under the pt pma minimum capital rules. JCSS Indonesia, in the review dated 2026-10-20, records that Government Regulation No. 28 of 2025 replaced PP 5/2021 from 2025-06-05, that the KBLI 2025 transition under BPS Regulation No. 7 of 2025 needs no licence swap, and that foreign ownership caps follow Perpres 10/2021 and 49/2021. These are framework references and sit outside the capital calculation. The paid-up deposit does not set the ownership cap, and the ownership cap does not change the deposit floor. Grey areas to confirm in writing Three grey areas remain. First, a sector rule can set its own amount under kecuali ditentukan lain, so the pt pma minimum capital default must be checked against the KBLI-specific regulation before a transfer. Second, the counting unit shifts: five-digit KBLI for the general case, four digits for wholesale and construction, two digits plus location for food and beverage. Third, multiple project locations and multiple business lines are measured per location and per five-digit KBLI under Pasal 26(2), while real estate, accommodation, agriculture, plantation, livestock and aquaculture pull land and buildings into the investment value. Where these units differ, the safe step is to obtain written capital and fee confirmations per line and to avoid assuming one consolidated figure. A file that records the article numbers, the deposit date, the self-declaration format, the LKPM dates and the applicable sector rule gives a notary and a company secretary a checklist they can verify line by line. Sources Minister of Investment and Downstreaming / BKPM, “Regulation No. 5 of 2025 on Risk-Based Business Licensing and Investment Facilities through OSS” (2 October 2025, official text). https://jdih-storage.bkpm.go.id/jdih/jdih/2025Permeninvesthil005-.pdf Government of Indonesia, “Government Regulation No. 28 of 2025” (peraturan.go.id). https://peraturan.go.id/eng/pp-no-28-tahun-2025 JCSS Indonesia, “Foreign Companies in Indonesia: Examples, Legal Forms and Requirements” (reviewed 20 October 2026). https://jcss.co.id/en/insights/foreign-companies-in-indonesia 3E Accounting Indonesia, “When a Local PT Is Not Enough: 7 Foreign-Ownership Scenarios That Require PT PMA Registration”. https://www.3ecpa.co.id/?p=46778 AccessiaPass, “PMA Capital Rules 2026” (checked 4 November 2026). https://accessiapass.com/tl/blog/bolehkah-turis-asing-buka-usaha-di-bali-modal-pma-2026 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Vietnam industrial park costs: North vs South in 2026 SeaPRwire

Vietnam industrial park costs: North vs South in 2026

CBRE put the average asking rent for northern industrial land at US$143 per square metre per lease cycle in Q2 2026, up 2.9% year on year, against US$185 in the south, up 3.7%, and that north-south split is the only published anchor for a vietnam industrial park cost model. Net absorption in the north reached about 217 hectares in the same quarter, the highest single-quarter figure since the 218 hectares of 2024 Q1, up from 134 hectares in Q1 2026. The south absorbed about 67 hectares, against 57 hectares in Q1 2026 and 10 hectares a year earlier. A team that signs a lease on these two rent lines alone will be pricing one line of a much longer schedule. Market entry thresholds and the paperwork to request Entry paperwork is set by policy before it is set by price. Resolution No. 10-NQ/TW, dated 2026-06-08, and the revised Investment Law provide for simplified administrative procedures, the promotion of eco-industrial parks, and the delegation of approval to local authorities. These provisions fix which authority approves a project and which environmental standard a park has to meet. A tenant should request the written approval chain and the land-use documents before it requests a quotation. One tariff clause belongs in the same entry check. Vietnam applies a 12.5% additional import tariff under Section 301, against 10% for Bangladesh, India and Indonesia. The same material lists textiles, footwear and wood products as labour-intensive sectors whose expansion plans may be affected. That line belongs in a cost model as a neutral statement of the clause. The scale of new entry appears in the VGP figures dated 4 October 2026. Registered FDI for the first nine months of 2026 was US$50.36 billion, up 76.4% year on year, while disbursed FDI was US$21.07 billion, a five-year high for the period. Newly licensed projects numbered 3,108, with registered capital of US$29.24 billion. The project count was up 6.2% and the capital was 2.4 times the prior-year figure. Manufacturing and processing drew US$13.38 billion, or 45.8%. Invest Vietnam carries a second cut of the same nine-month flow from Foreign Investment Agency data. New and expanded manufacturing capital combined reached US$21.82 billion, or 50.3%, with 948 capital-increase items worth US$14.15 billion and 2,335 equity-investment and share-purchase deals worth US$6.97 billion. Manufacturing accounted for 82.6% of disbursed FDI, or US$17.40 billion. Request the written fee schedule, the land-use documents and the approval chain before any price is compared. Land rent and the published price lines Of the whole vietnam industrial park cost stack, land rent is the only line with a published, comparable figure. The CBRE series for Q2 2026 puts the northern average asking rent at US$143 per square metre per lease cycle, up 2.9% year on year, and the southern average at US$185, up 3.7%. Both are whole-market asking prices quoted per lease cycle, not transacted rents. VARS data for Q3 2026 add the occupancy and rental movement behind those quotes. Occupancy stood at 92% in the south and 85% in the north, park rents were up about 5-10% against 2025, and industrial-cluster rents were up 10-20% year on year. Ready-built factories absorbed 0.5 million square metres in the quarter at 90.2% occupancy. These are stock and absorption measures, not a per-hectare land price. Input costs sit on the developer side of the same stack. Building-material prices for sand, stone, cement and levelling material were up about 20% year on year, and margins at new parks may fall from above 50% at established parks to 30-35%. For 2026 H1, sector net revenue fell 20.2% to about VND 38,000 billion and net profit fell 40% to about VND 4,000 billion. Net profit for 2027 across park developers and rubber companies involved in land conversion is projected at VND 22,300 billion, up 12.4%. A vietnam industrial park cost sheet built only from these lines is still incomplete. Ask each park for a written quotation that states the unit, the lease term, the period and every recurring charge. Why the two northern rent figures cannot be averaged Two published northern figures look almost identical and measure different things. In the CBRE series for Q2 2026, the northern average asking rent was US$143 per square metre per lease cycle, up 2.9% year on year, covering the whole market. In the VARS Q3 2026 report, the CBRE figure for the northern primary market was about US$144 per square metre per remaining lease term, up 0.8%. The two figures differ in period, sample and quote unit. Q2 2026 is set against Q3 2026. Whole-market asking prices are set against the primary market only. Price per lease cycle is set against price per remaining lease term, and those two units are not equivalent. Averaging them would produce a northern benchmark that matches no published series. A vietnam industrial park cost comparison that averages US$143 and US$144 into one line erases those three separators. The two figures cannot be compared directly. A lease should be signed against a written park quotation that states its own period, sample and unit, and the definitions should be recorded next to the number. Both figures are CBRE numbers. The mismatch is in what each one measures. Costs that require a written park-by-park schedule Electricity tariffs, distance to port and labour-recruitment difficulty are the three lines a site-selection team most wants and the three lines no comparable public English-language source supplies. No figure for any of them appears in the sources behind this assessment, and none should be invented for a vietnam industrial park cost model. The usable conclusion is procedural: each has to be requested from each park as a written charge schedule. The reason those three lines are not comparable across parks is structural. EVN electricity pricing is time-of-use, so a single tariff figure would hide the peak and off-peak split. Port distance is measured from a specific park to a specific berth, not from a province, so a provincial average carries no usable meaning. Recruitment difficulty depends on the process step and the shift pattern, so one hiring figure cannot be compared between two parks with different product mixes. Ask for the time-of-use tariff table, the named berth and the haulage distance from the specific plot, and the wage and shift schedule for the intended process. A vietnam industrial park cost sheet without those three written annexes is an estimate, and internal approvals should label it that way. Supply timing and the lease calendar Absorption sets the clock. Net absorption in the north was about 217 hectares in Q2 2026, the highest single-quarter reading since the 218 hectares of 2024 Q1, up from 134 hectares in Q1 2026. The south absorbed about 67 hectares in Q2 2026, against 57 hectares in Q1 2026 and 10 hectares a year earlier. The two regions sit on different bases. New supply is dated. CBRE projected about 1,347 hectares of new industrial land from Q4 2026 to 2027, split as 664 hectares in the north and 683 hectares in the south. Northern supply is concentrated in Bac Ninh, Thai Nguyen, Hai Phong, Hung Yen and the area around Hanoi. Southern supply is listed for Dong Nai, Binh Duong, Long An, Tay Ninh and Ba Ria-Vung Tau. CBRE also projected that about 2,700 to 3,200 hectares of industrial land and 1.7 to 2 million square metres of ready-built factory and warehouse space would be added by 2028. New lease and MOU area for 2027 is projected to rise 18.6%, mainly in Tier 2 parks. Infrastructure in progress includes the North-South expressway, the Long Thanh-Dau Giay expressway expansion, the Bien Hoa-Vung Tau expressway, and Ring Roads 3 and 4. A vietnam industrial park cost decision has to fix the period before the price. Q2 2026 absorption, Q4 2026 to 2027 supply and 2028 capacity are three separate dates, and a rent quoted for one of them has to be restated before it is carried into another. Three traps in the published numbers The first trap is mixing definitions. A vietnam industrial park cost model that blends the US$143 whole-market Q2 2026 quote with the US$144 primary-market Q3 2026 quote produces a number that matches no published series. The two periods and the two samples have to stay labelled. The second trap is reading occupancy as available area. The VARS Q3 2026 figures of 92% in the south and 85% in the north, and the 90.2% ready-built factory occupancy, describe how much stock is taken, not how many hectares a tenant can lease next quarter. A vietnam industrial park cost sheet needs the park’s own written plot inventory, because a headline occupancy rate says nothing about the size, shape or servicing of the remaining plots. The third trap is treating registered FDI as disbursed capital. Registered FDI of US$50.36 billion for the first nine months of 2026 sits alongside disbursed FDI of US$21.07 billion for the same period, and the 3,108 newly licensed projects with US$29.24 billion of registered capital are commitments, not cash on site. A vietnam industrial park cost case built on the larger number will overstate the flow that has actually arrived. The documents to hold before signature are specific. They include a written quotation stating unit, lease term, period and sample, a time-of-use tariff table, a named-berth haulage distance, a process-level wage and shift schedule, a written plot inventory, and the approval chain under Resolution No. 10-NQ/TW. A vietnam industrial park cost file assembled from those annexes can be audited line by line against the written park quotation. Sources Vietnam Government News (VGP), “Disbursed FDI volume in Jan-Sept period reaches five-year high” (4 October 2026). http://news.gov.vn/disbursed-fdi-volume-in-jan-sept-period-reaches-five-year-high-111261004144218691.htm Vietnam.vn, “With accelerated FDI, Vietnam’s industrial real estate sector is poised for a new growth cycle” (SSI Research 2027 Investment Strategy Outline; CBRE data). https://www.vietnam.vn/en/fdi-tang-toc-bat-dong-san-cong-nghiep-viet-nam-dung-truoc-chu-ky-tang-truong-moi Invest Vietnam, “FDI tops US$50 billion in nine months, disbursement hits five-year high” (Foreign Investment Agency data). https://investvietnam.vn/fdi-tops-us-036-50-billion-in-nine-months-disbursement-hits-five-year-high-n4150.html This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More
Thailand’s Senior Care Boom Has a Billing Problem: Who Pays When 45 Percent Retire With Nothing SeaPRwire

Thailand’s Senior Care Boom Has a Billing Problem: Who Pays When 45 Percent Retire With Nothing

Nursing homes ran at 81 percent occupancy in 2025 while the state allowance pays 600 baht a month. An arithmetic check on Thailand’s silver economy. The lobby of a mid-range nursing home in Chiang Mai does not look like the site of a funding crisis. The intake paperwork is thorough, the nurses are certified, the monthly invoice is printed in clean type. But run the arithmetic that sits underneath that invoice and a mismatch appears that no amount of interior design can hide. In 2025 a basic private nursing home bed in Thailand starts at about 15,000 baht a month, according to cost data compiled by SEA Weekly. The state old-age allowance for a Thai aged 60 to 69 is 600 baht a month. The gap between those two numbers, a factor of 25, is the single most important fact about Thailand’s senior care economy, and almost nothing in the market’s glossy growth narrative acknowledges it. A Market That Looks Healthy on Every Line On the supply side, Thailand’s senior care sector has spent the last decade building out with genuine speed. Data from the Government Housing Bank’s Real Estate Information Center (REIC), reported through the Bangkok International Times in 2025, put the country at 1,040 senior housing projects with 33,149 rooms, alongside 944 nursing home projects offering 17,349 beds and roughly 15,800 units of premium senior apartments. Utilization, the number every operator quotes first, is strong: nursing homes ran at 81 percent occupancy in 2025 and senior housing at a 82 percent rental rate. The service layer beneath the property layer is equally busy. Thailand’s Department of Business Development (OTPS) counted 2,331 registered senior care businesses in 2025, of which 1,475 were home care operators and 810 provided long-stay arrangements. The care services market itself was valued at 2.57 billion baht in 2023 by the same department. Layered across the whole sector is a foreign demand component that the domestic numbers rarely separate out: Thailand’s retirement visas, the O-A and O-X categories and the Long-Term Resident visa introduced in 2022, have made the country one of Asia’s standard destinations for affluent foreign retirees, and expatriate demand concentrates in exactly the premium apartment and full-service nursing segments where monthly invoices can reach five to ten times the domestic basic rate. The following table sums up the physical supply side as it stood in 2025. Segment Projects Units or beds Utilization in 2025 Senior housing 1,040 33,149 rooms 82 percent rental rate Nursing homes 944 17,349 beds 81 percent occupancy Premium senior apartments n/a 15,800 units not published Source: REIC figures via Bangkok International Times; Department of Business Development data via Pattaya Mail (no public link) Read as a whole, the table describes a market that has figured out how to build beds and fill them. What it does not describe is a market that has figured out who pays for them once the customer is Thai rather than foreign. Two Variables Are Stacking, and Only One of Them Is Being Managed The analytical mistake most coverage of this sector makes is treating Thailand’s ageing wave as a single variable, population, moving at a single speed. In fact two separate structural variables are moving at once, and their interaction is what makes the Thai case unusual. The first variable is demographic speed. Kasikorn Research Center, in a report covered by China News Service in October 2026, noted that Thailand crossed into aged society status at the end of 2023, when the population aged 60 and above reached about 13 million, one fifth of the national total. The same center projects that by 2029 the share of Thais aged 65 and above will pass 20 percent, which would make Thailand the first developing country in Asia to reach so-called super-aged status. The working age share, 62 percent of the population in 2023, is projected to fall to around 50 percent by 2050. REIC’s own 2025 count puts the 60-plus population at 13.99 million, 21.3 percent of the country, which means the 2029 milestone is less than one election cycle away. The second variable is funding capacity, and here the numbers stop flattering anyone. SEA Weekly’s 2025 reporting found that 45 percent of older Thais have no savings at all and 30 percent live below the national poverty line. Against a basic nursing home fee of 15,000 baht a month, the state’s old-age allowance of 600 baht for those aged 60 to 69, rising only modestly with age brackets, functions as a rounding error. The contributory pension system offers little more. Under the Social Security Office’s rules, an insured worker who contributes the full 15 years qualifies for an old-age pension starting at 20 percent of average wages, and the wage ceiling for contributions rose to 17,500 baht in January 2026, which caps the maximum monthly contribution at 875 baht per side. Legal summaries of the scheme published in 2026 put the minimum pension at 3,500 baht a month for 15-year contributors, rising to 6,125 baht for those with 25 years under the revised schedule that took effect in January 2026. Even the most generous rung of that ladder, 8,050 baht a month from 2032 for the longest contributors, covers barely half of a bottom-tier nursing home bed. The following table lines up the monthly money against the monthly bill. Monthly amount 2025 or 2026 level (THB) What it covers Old-age allowance, aged 60 to 69 600 under 4 percent of a basic nursing bed Minimum SSS pension, 15 years contributed 3,500 (from January 2026) about 23 percent of a basic bed SSS pension, 25 years contributed 6,125 (from January 2029) about 41 percent of a basic bed Basic private nursing home bed from 15,000 the bill itself Source: SEA Weekly cost and poverty reporting, 2025 (no public link); Social Security Office benefit schedules via LegalClarity ; IBC contribution guide, 2026 Two factors are therefore stacking: a demographic clock that is running faster than almost anywhere else in the developing world, and a payment architecture in which neither the state nor the contributory system comes close to the market price of care. Occupancy of 81 percent hides this because the current occupants, disproportionately expatriate retirees and affluent urban Thais supported by family transfers, are not the median future customer. The median future customer is the 45 percent. Where the Two Variables Go From Here Projections for the demand side are the one place where Thai officialdom and independent researchers agree, and the agreement is loud. The Thailand Development Research Institute (TDRI) has projected that elderly consumer spending will reach 3.5 trillion baht by 2033, with 6.6 million people aged 60 and above, about 37 percent of that cohort, remaining active in the labor market, generating employment income of 880 billion baht in 2033, up from 640 billion baht in 2024. Kasikorn Research Center adds a fiscal warning: as the workforce shrinks, tax revenue flattens while pension and medical outlays climb, a scissors motion that the center flagged as a balance risk for the state budget in its October 2026 report. The supply side response so far has been organizational rather than financial. Dr Ekachai Piensriwatchara, a senior Thai geriatrician involved in the national planning process, told Nation Thailand in 2026 that Thailand has trained caregivers and care managers along Japanese lines for about 12 years but has not yet introduced a long-term care insurance system, and he expects one to be introduced. A five-year national action plan built after a Tokyo exchange meeting sets six priorities, including screening for falls and dementia, integrating health and welfare services, home medicine delivery, and income promotion with Finance Ministry involvement. The country’s assets here are real: more than one million village health volunteers, a universal health coverage scheme with international standing, and nearly 20,000 nurses trained as care managers. Private capital is moving into the vacuum the state has left. Bangkok Life Assurance restructured its product line in 2025 and 2026 around long-duration care payouts, and industry reporting from Hey Thailand News in 2026 values the private long-term care insurance market at 1.3 billion US dollars in 2025, expected to reach 2.3 billion US dollars by 2031. Muang Thai Life, AIA Thailand and Thai Life are bundling home health services and annuities into competing products. The private LTC insurance market, in other words, is being built at roughly the same moment the public one is still being debated. The arithmetic of the next decade follows from these curves. Demand in baht terms grows along the TDRI line toward 3.5 trillion baht of elderly spending by 2033. Public supply grows along the administrative line, allowance top-ups, volunteer networks, pilots. Private supply grows along the insurance line, currently 1.3 billion dollars and compounding. Which curve bends fastest is the question that determines whether the 15,000 baht bed has a mass market or a niche one by 2030. What the Private Market Is Selling Under the Counter The insurance products now arriving on Thai shelves deserve a closer look, because their structure reveals how the industry itself prices the gap calculated above. Bangkok Life Assurance, one of the country’s largest life insurers, retired the phrase insurance agent in 2026 and rebranded its field force as Life Care Partners, with more than 65 percent of agents completing a training program called Agents of Care that covers nutrition routines, medication reminders and social isolation alongside policy servicing. The flagship structure, BLA Long Life Care, pays out 10 percent of the policy value every year upon diagnosis of any of eight chronic neurological conditions, Alzheimer’s and Parkinson’s among them, and keeps paying until age 99. A companion product, Pension and Care 888, begins with a 30 percent upfront payout at age 60 and then pays 8 percent annually to age 88, with an additional 8 percent per year triggered by any critical illness diagnosis from the policy’s start date. A third bundled plan, Huangrak Sood Khoom, wraps 25 critical illnesses, accident cover and life coverage to age 99 into a single whole-life contract aimed at middle-income households. The design logic is easy to state: traditional critical illness cover assumes the financial shock is a spike, one hospitalization, one claim, one settlement. Chronic care is not a spike. It is a decade-long annuity running in reverse, and a market where 45 percent of elders hold no savings cannot self-insure against it. The insurer’s own balance sheet adjustments confirm the direction: BLA reduced equity exposure and shifted into Thai government and state enterprise bonds, lengthening asset duration to match payout obligations that may run three decades past retirement. Muang Thai Life’s competing Flexi Retire annuities couple lump-sum options with direct access to 44 senior living facilities nationwide, which turns the insurer into a distribution channel for the very beds counted in the table above. Set this beside the informal economy and the picture rounds out. The People’s Daily reported in December 2025 that Thailand’s elderly services sector had passed 140,000 registered companies by the end of 2023, that the silver industry reached 100 billion baht in 2022, and that the Public Health Ministry has begun allowing small nursing homes to register as companies, a rule change that pulls informal operators into the formal economy where they can be priced, taxed and eventually insured against. TDRI researchers group the sector’s potential into four industries: senior housing and accessibility retrofit, nutrition and texture-modified food, health care and companionship, and leisure and social services. One comparative note keeps the Thai case honest. Japan, the society Thailand has studied most closely, runs a compulsory long-term care insurance scheme whose 2025 care budget reached 12.2 trillion yen for 5.78 million benefit recipients, figures from Japan’s own social security statistics. Thailand’s entire care services market, 2.57 billion baht in 2023, is smaller than a rounding error on that line item. A town like Minamiboso in Chiba prefecture, visited by Thai planners during the Tokyo exchange, identifies residents at risk of dementia or falls and places them in three-month multidisciplinary rehabilitation before they become bedridden, with care homes nearly full and the system pushing care back into homes. That is what a funded system looks like from the inside. Thailand’s five-year plan borrows the screening and case-management architecture, but as of 2026 it still lacks the funding spine that pays for it, and every product described above is, in effect, a private subscription for that missing spine. Who Gets Hit First Structural forecasts are abstract until you sort the population by exposure. In this market the sorting produces four groups, in descending order of vulnerability. Middle-income elderly with no savings: the 45 percent with zero savings sit outside both the contributory pension system and the private insurance market, and family support is their only remaining buffer. Rural two-generation households: where the adult children have migrated to Bangkok or abroad, the 600 baht allowance and patchy community services must cover what an urban family would absorb privately. The care workforce pipeline: the sector counted 2,331 registered care businesses in 2025, and a system that has not decided how care is paid cannot decide what caregivers are worth, which keeps wages and retention structurally weak. Small operators in the middle price band: homes priced between the allowance-and-family segment and the expatriate premium segment face the sharpest exposure if public funding rules change abruptly. The labor market twist deserves its own paragraph. Nearly 40 percent of Thais aged 60 and above are still working, according to the Department of Older Persons statistics cited in the People’s Daily report of December 2025, and the government is considering raising retirement ages for some occupations. The Bangkok Mass Transit Authority employs crews of whom about 10 percent are over 60. TDRI’s forecast has 6.6 million older Thais, 37 percent of the cohort, in the labor market by 2033. This is usually framed as a burden, but in billing terms it is also the only large-scale self-funding mechanism currently operating at scale: an elder who earns keeps paying rent, food and family obligations without touching the care budget. Every percentage point of elderly employment is, in effect, a subsidy the state does not have to legislate, and the four sectors above compete with it for the same households. None of these groups appears in the occupancy statistics. That is precisely the point: occupancy measures the people who already made it through the door, not the ones the pricing excludes. The Signals That Would Prove This Reading Wrong A claim that rests on two variables should name, in advance, the evidence that would break it. Three leading indicators do that work here, and each is independently observable. LTC insurance uptake: if the private long-term care insurance market stalls near its 2025 level of 1.3 billion dollars instead of tracking toward the 2.3 billion dollar 2031 forecast, the private funding curve is failing and the billing problem hardens. Occupancy inversion: a sustained drop in nursing home occupancy below 75 percent, or a flattening of senior housing rental rates from their 2025 level of 82 percent, would signal that demand at current price points is thinner than the build-out assumed. A legislated public LTC scheme: if Thailand passes a social long-term care insurance law before 2029, on the schedule Dr Ekachai expects, the second variable changes category entirely and the gap analysis above must be rebuilt from the new benefit schedule. There is a fourth, quieter signal: the TDRI employment income curve. If income of Thais aged 60 and above grows faster than the projected path from 640 billion baht in 2024 to 880 billion baht in 2033, self-funding capacity is improving faster than assumed and the mismatch narrows from the income side instead. Anyone tracking this market should watch those four numbers, because the glossy ones, project counts and occupancy, will stay pretty long after the underlying equation has tipped. Data Basis Supply figures (1,040 senior housing projects, 33,149 rooms, 944 nursing projects, 17,349 beds, 15,800 premium units, 81 percent occupancy, 82 percent rental rate) come from REIC 2025 data via the Bangkok International Times. Business counts (2,331 care firms, 1,475 home care, 810 long-stay) and the 2.57 billion baht 2023 market value come from the Department of Business Development via Pattaya Mail. Cost and poverty figures (15,000 baht fees, 600 baht allowance, 45 percent no savings, 30 percent below the poverty line) come from SEA Weekly, 2025. Pension schedules follow the Social Security Office as summarized by LegalClarity and IBC in 2026. Macro projections come from Kasikorn Research Center (October 2026), TDRI (2025) and Nation Thailand (2026). Data as of November 2026. Limitations Occupancy and rental figures cover registered formal supply only; informal family care is invisible in them and unquantified here. Expatriate demand is not broken out in any series used, so the Thai-versus-foreign payer split is inferred from price points. The private LTC insurance market size rests on a single industry report; pension figures follow the January 2026 schedule and will shift again in 2029 and 2032. Sources Nation Thailand – national ageing action plan, 2026 Hey Thailand News – private LTC insurance market, 2026 LegalClarity – Social Security Office benefit rules, 2026 IBC Firm – 2026 contribution schedule, 2026 China News Service – Kasikorn Research ageing report, October 2026 (in Chinese) Tibet.cn – TDRI elderly economy projections, December 2025 (in Chinese) REIC (Government Housing Bank) – senior housing survey 2025 (no public link) Department of Business Development (OTPS) – care business registry 2023 to 2025 (no public link) About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
The UAE Put AI in Every Public School Classroom and Four Myths Spread Faster Than the Curriculum SeaPRwire

The UAE Put AI in Every Public School Classroom and Four Myths Spread Faster Than the Curriculum

From kindergarten stories to Grade 12 prompt engineering: what the 2025-2026 UAE AI curriculum requires, and what it never promised. Walk into a Year 3 classroom at Dubai British School Jumeira Park on an ordinary weekday and you will see a seven-year-old chatting with an AI-generated Willy Wonka, while another child interviews a virtual polar bear about its favorite food. You will also see a small traffic-light card on the wall. Red means no AI, the homework is done alone. Yellow means only the tools the teacher named. Green means free exploration under supervision. Brendon Owens, the school’s digital strategy lead, described exactly this system to UNESCO’s reporters in 2025. That card, taped up by a school for its own reasons, is a better entry point into the UAE’s AI education story than most of the headlines, because almost everything that travels internationally about this policy is one shade more dramatic than the record supports. Four beliefs in particular deserve to be taken apart with the documents in hand, and each one can be checked in under a minute by anyone who knows where to look. Myth 1: The UAE Was the First Country in the World to Do This The claim circulates constantly, and it is one notch stronger than what the government itself announced. On 4 May 2025 the Emirates News Agency (WAM) reported that the Ministry of Education would make artificial intelligence an official subject across all public schools, kindergarten through Grade 12, starting from the 2025-2026 academic year. The same release, and the Minister of Education Sarah Al Amiri in her quoted remarks, used a precise phrase: the UAE becomes one of the first countries to introduce AI in school curricula. That phrase survived into the Arabic-language regional coverage and the international wire copies. Somewhere in the reposting chain, among the first became the first, and the superlative version now outranks the original in search results. The check takes one minute. Open the WAM release and read the phrasing. The Ministry’s own English materials say among the first. Whether the UAE is literally first depends on definitions the official record never settles: Estonia had announced AI learning programs for schools, China had run AI pilot curricula in provinces for years, and Singapore had computing syllabus strands with AI components. What the UAE did that is genuinely distinctive is different: it mandated a dedicated AI subject across every year of public schooling at once, nationwide, with named delivery partners. The Ministry attached an institutional bench to the rollout: Presight, the analytics company under the G42 group, AI71, the Mohamed bin Zayed University of Artificial Intelligence, and the Emirates College for Advanced Education were all named in the May 2025 announcement as partners for accelerating adoption in classrooms. Reading that roster operationally, the state was not buying a textbook, it was wiring four different kinds of capacity, applied analytics, applied model development, academic research and teacher training, into one implementation chain. That is a genuine achievement and it needs no inflation. The precise claim is worth defending precisely, because every inflated claim hands skeptics an easy target and distracts from the thing that is genuinely hard: teaching 13 years of AI concepts to a national student body in one school year. Myth 2: It Is a ChatGPT Class The second myth shrinks the curriculum into a tool-training seminar. The record says otherwise, and the structure is public. The UAE AI curriculum spans seven areas, and the list itself answers the tool-training myth before any argument starts. Foundational concepts, the vocabulary of what models are and are not Data and algorithms, where the logic under the interface lives Software use, deliberately fourth, not first Ethical awareness, an examinable strand rather than a poster Real-world applications, tied to the student’s own environment Innovation and project design, where students build rather than consume Policies and community engagement, the civic layer of the technology It does not add teaching hours; it rides inside the existing Computing, Creative Design and Innovation subject, delivered by designated teachers with lesson plans the Ministry publishes as adaptable guides. Minister Al Amiri’s own framing, quoted by WAM in May 2025, pushed back on the tool-seminar reading directly: the goal is a generation with tech ethics awareness that can build locally relevant solutions, not a generation that knows one app. The age-band structure is the fastest way to verify this in a classroom. Kindergarten children meet AI concepts through visual and interactive play, stories and games, not keyboards. In Cycle 1, primary students compare machines to humans and build digital thinking habits. In Cycle 2, roughly ages 10 to 14, students design and evaluate AI systems and study bias, which means the curriculum treats ethics as examinable content, not an assembly-day poster. Cycle 3, the secondary years, is where prompt engineering and simulated real-world scenarios appear, and even there the framing is command design and evaluation rather than app mastery. A visitor who wants one concrete contrast should hold the kindergarten unit against the Cycle 3 unit: the same subject family spans from a five-year-old meeting the idea of a machine that talks through a storybook character, to a seventeen-year-old writing and critiquing prompts against a simulated scenario. That span, thirteen years of one subject, is what a national mandate means in operational terms, and it is also why the tool-seminar reading fails on contact: no single product teaches that range. The following table compresses the ladder as the Ministry published it. Stage What students do Where it appears in the record Kindergarten meet AI through stories, games and interactive visuals WAM curriculum release, May 2025 Cycle 1 compare machines and humans, build digital thinking WAM curriculum release, May 2025 Cycle 2 design and evaluate AI systems, study bias and ethics WAM and UNESCO reporting, 2025 Cycle 3 prompt engineering and real-world scenario simulation WAM curriculum release, May 2025 Source: Ministry of Education curriculum materials via WAM, May 2025 (no public link) An operator reading that table should notice what it implies for procurement: any vendor pitching an AI product to a UAE public school on the grounds that the national curriculum requires that specific product is misdescribing the mandate. The Ministry publishes guides and models; it does not publish a shopping list. Myth 3: Every School in the Country Must Follow It The third myth quietly universalizes a public-sector mandate. The May 2025 decision covers public schools under the federal Ministry of Education. Dubai’s private sector, which is enormous, sits under a different regulator with its own rules: the Knowledge and Human Development Authority (KHDA). The scale matters here. KHDA’s own landscape publication for 2025-26 counts 227 private schools in Dubai carrying 388,731 students, with enrolment growth of 0.33 percent for the year, and a higher education layer of 50,690 students across 41 private institutions licensed by KHDA, up 20.6 percent overall, with international branch campus enrolment up 29.5 percent and Emirati student numbers up 24 percent. The following table lines up the private landscape that the myth wrongly folds into the mandate. Segment 2025-26 figure Change published by KHDA Dubai private schools 227 schools stable base Private school students 388,731 enrolment up 0.33 percent Private higher education students 50,690 up 20.6 percent International branch campus enrolment part of the 50,690 up 29.5 percent Emirati students in private higher education part of the 50,690 up 24 percent Source: KHDA Dubai private school landscape 2025-26 and KHDA higher education publication What private schools are doing with AI is genuine but voluntary, and it looks nothing like a single template. Saeed Kharbash, KHDA’s director of policy, research and programs, told UNESCO that AI is a government priority and that Dubai wants a system balancing innovation and safety. The delivery, though, is school by school: Dubai British School Jumeira Park gates general AI tools until Grade 9, gives younger students a curated platform with built-in guardrails running on the school domain so usage can be audited, and writes its own traffic-light policy. Another school down the road will make different choices. The higher education half of the KHDA numbers adds a second layer: 37 of the 41 private institutions are international branch campuses, and the fastest-growing student groups are international students at 29.5 percent and Emirati students at 24 percent, which makes Dubai less a school system than a talent interchange, and explains why the emirate’s AI education conversation runs several lanes wide of any single federal memo. A parent relocating to Dubai should not assume the federal syllabus applies to the school they are touring, and a vendor should not pitch a public-school mandate to a KHDA-regulated school, because the two conversations follow different rulebooks. The KHDA rulebook has teeth of its own, mandatory curriculum requirement guides, guidance on national mandatory subjects, and published policies on Arabic language provision, so voluntary does not mean unregulated. It means the AI question is answered in a different folder. Myth 4: This Is Screens Replacing Teachers The fourth myth is the doom-flavored one: AI class means children alone with screens while teachers fade into supervision. The reporting from inside classrooms shows a design that pushes the opposite way, and a principal evaluating the risk can see the whole control stack in one visit. The UNESCO feature on UAE classrooms describes teachers running the traffic-light system as an explicit authority structure over AI use, teachers choosing the yellow-list tools, and the curriculum itself sitting inside subjects taught by designated teachers with Ministry-issued lesson plans. The UNESCO feature on UAE classrooms describes teachers running the traffic-light system as an explicit authority structure over AI use, teachers choosing the yellow-list tools, and the curriculum itself sitting inside subjects taught by designated teachers with Ministry-issued lesson plans. The guardrails pattern repeats across the private sector examples: younger students get a closed platform on the school domain, audit logs included, and broader general-purpose tools only from Grade 9. Owens made the mechanism explicit in the UNESCO interview: because the tools run under the school’s domain, the school can review and manage them. There is a second, quieter piece of evidence: what the curriculum chose to examine. Bias, ethics, evaluation of AI systems, and community impact are examinable strands, which means the system is spending assessment time on judgment, the part a screen cannot supply. A country that wanted teachers out of the loop would not have built an ethics strand into a national syllabus, and would not have needed thousands of school-level decisions about which tools sit on a yellow list. The teacher is not being phased out of this design; the teacher is the enforcement layer of it. Why These Myths Travel Faster Than the Memos None of the four beliefs appeared out of thin air, and each has a transmission mechanism that is worth naming, because the mechanism predicts the next distortion too. Superlative drift: official phrases like among the first lose their qualifier in reposting chains, because first is shorter, and search engines reward the shorter version. Tool bias: readers map any AI policy onto the one AI product they know, so a seven-strand curriculum becomes a ChatGPT class in the retelling. Scope flattening: a federal public-school mandate and a city’s private-school landscape get welded into one story, because both are summarized with the same two words, UAE schools. Anxiety projection: the teacher-replacement story arrived pre-loaded from other sectors and attached itself to the first education announcement it met. The fourth mechanism has a regional footnote. Because the announcement travelled in three languages within a week, WAM’s English and Chinese wires, Huanqiu’s syndication, Gulf outlets, each hop stripped a qualifier. By the time a claim returns to the region from an international aggregation site, it can carry authority the original never had, and correcting it locally means arguing with a version of your own government’s announcement. The pattern to watch is that every myth makes the policy simpler and louder than the record. The record, a seven-area curriculum inside existing hours, a public-school scope, voluntary private adoption, and a traffic-light card on a classroom wall, is more boring and more interesting at the same time. The Rollout Calendar, Read From the Ground Because the mandate started with the 2025-2026 academic year, the second year of implementation is the one worth watching, and the observable checkpoints are public enough to monitor from outside. The Ministry promised comprehensive guides, activity models and adaptable lesson plans, which means a shortage or a surplus of published materials in year two is itself a signal. Teacher readiness is the second checkpoint: a subject that rides inside existing hours without added staffing stands or falls on designated teachers’ confidence, and the Ministry’s choice to route training through the Emirates College for Advanced Education is the institutional tell for where that investment lands. The third checkpoint is private-sector drift: KHDA publishes mandatory curriculum requirements for private schools, and if AI content migrates from recommended to required in a future update, the third myth, universal scope, will have stopped being a myth. Anyone running a school, an agency or an edtech product in the region can put those three checkpoints in a calendar and wait for evidence instead of rumor, which is the entire difference between monitoring a rollout and merely reacting to its headlines. What a Parent or Principal Should Check First The operational value of tearing down four myths is the checklist it leaves behind, and this one is short enough to run before a school tour or a product meeting. Read the source announcement, not the repost: the Ministry’s May 2025 release says among the first, mandates public schools only, and names the seven curriculum areas. Ask which cycle a product or lesson targets: kindergarten through Cycle 3 have different content, and a vendor who cannot answer in the curriculum’s own stages is selling outside the mandate. Ask a Dubai private school who regulates them: KHDA schools set their own AI policy, so the question is the school’s written policy, not the federal syllabus. Ask to see the traffic light: whether a school uses that exact system or another, the existence of a written AI-use policy with named tools is the sign of governance, and its absence is the sign to keep asking. Watch the assessment, not the brochure: bias and ethics strands in the syllabus mean a school taking the mandate seriously will be teaching judgment, not just usage. A closing observation for anyone running a classroom audit: the strongest evidence in this file is the shape of the small decisions. A school domain that logs AI use, a wall card that names three modes, a syllabus that examines bias, these are cheap, boring, checkable mechanisms, and they did not have to exist. Five checks, one minute each, and the difference between the story and the policy is visible from the corridor. That is the point of taking myths apart in this order: the demolition is only worth doing if it leaves a working instrument behind. Data Basis The curriculum mandate, its seven areas, its integration into the Computing, Creative Design and Innovation subject without additional teaching hours, and its May 2025 announcement date come from the Ministry of Education release carried by WAM on 4 May 2025. The Dubai British School Jumeira Park classroom example, the traffic-light system and the school-domain guardrail practice come from UNESCO’s 2025 feature, including the quotes from Brendon Owens and KHDA’s Saeed Kharbash. Dubai private education figures (227 schools, 388,731 students, 0.33 percent growth) and higher education figures (50,690 students, 41 institutions, 20.6 percent, 29.5 percent and 24 percent changes) come from KHDA’s 2025-26 landscape publications. Data as of November 2026. Limitations The classroom observations come from two reported schools and do not constitute a survey of UAE classroom practice. Implementation quality across all public schools is not publicly measured, so this piece verifies scope and structure, not teaching outcomes. Private school AI adoption is voluntary and unenumerated; no public registry of school-level AI policies exists. The cycle-band ages are approximate. Higher education growth rates cover one year and mix branch campuses with domestic institutions. Sources WAM Emirates News Agency – AI curriculum announcement, May 2025 (in Chinese) Huanqiu Global Times – cabinet approval of AI classes, May 2025 (in Chinese) UNESCO – AI in UAE classrooms feature, 2025 (in Chinese) KHDA – Dubai private school landscape 2025-26 KHDA – Dubai higher education hub data, 2025-26 Ministry of Education (UAE) – AI curriculum guides and lesson plans (no public link) About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More
Global Wealth Added 89 Fortunes a Day. The Door to Professional Money Management Has a Queue. SeaPRwire

Global Wealth Added 89 Fortunes a Day. The Door to Professional Money Management Has a Queue.

713,626 UHNW individuals in 2026 and Singapore family office approvals at 10.5 months: three paths into wealth infrastructure and what each truly costs. Walk the corridor of any family office gathering in Singapore this year and the same queue shows up in conversation after conversation. A founder who sold a logistics business in 2024 is waiting on a tax exemption application. A second-generation heir from Jakarta has been interviewing multi-family offices since March and has three shortlists and no decision. A lawyer from Hong Kong is fielding two calls a week from families who assumed an office could be stood up in a quarter. Down the hall, a service provider is giving the same answer five times before lunch: the paperwork is ready, the people are hired, the approval is the part no one can accelerate. No one here is shopping for returns; they are shopping for capacity. No one in that corridor is short of money; they are short of processing capacity, and the queue is not a Singapore quirk. It is the visible edge of a global arithmetic problem: the number of very rich families is compounding much faster than the infrastructure built to serve them, and every family now entering that queue has to choose between three doors, each with its own bill. The Queue Has a Number, and So Does the Crowd Behind It Start with the size of the crowd, because it explains the queue. Knight Frank’s global wealth tracking, as compiled in this desk’s database, counted 551,435 ultra-high-net-worth individuals worldwide in 2023 and 713,626 in 2026, growth of 32.9 percent in three years, equal to about 89 net new UHNW individuals every day. The firm’s own forecast puts the global count at 948,241 by 2030, which would lift the daily net addition to 129 people. The regional texture matters for the corridor conversation: North America’s UHNW population grew 53 percent over the tracked period and still holds 37 percent of the global total, Asia-Pacific grew 24.3 percent to a 31 percent share, and the Middle East grew 32.1 percent. Every one of those people is a potential candidate for the same three doors, and the doors have not widened. The forecast deserves a pause, because 948,241 by 2030 is not just more of the same: it means the global system would need to absorb onboarding demand at 129 new fortunes a day, a 45 percent increase over the 2026 pace, while the professional infrastructure, the licensed professionals, the compliance staff, the experienced directors, grows by no comparable schedule. Now look at the door itself. Singapore’s tax-incentivized single family office population reached about 2,000 offices in 2026, up from 400 in 2020 and 1,400 in 2023, and the measurable symptom of that success is processing time: an application that took weeks in the early years now averages 10.5 months in this database’s Singapore figures, with practitioner reporting in 2026 describing total decision-to-operational timelines of 6 to 12 months under the 13O and 13U schemes. Hong Kong answered in 2023 with its Family-owned Investment Holding Vehicle concession, which qualified structures without pre-approval, and the result was a genuinely two-door region. But neither jurisdiction added capacity in proportion to the crowd. Singapore’s growth from 400 incentivized offices in 2020 to 1,400 in 2023 and about 2,000 in 2026 is a fivefold expansion in six years, and yet the processing average stretched rather than shortened, which tells you demand arrived faster than the service bench could professionalize. Every new office needs a director familiar with MAS expectations, investment professionals willing to anchor a one-family mandate, and service firms that know the scheme’s audit rhythm. Those inputs take years to train, and the queue in the corridor is what that mismatch looks like from inside. Why the Standard Answers Stop Working The conventional wisdom that served the previous generation of wealth fails at this scale for three separate reasons, and it is worth naming them before pricing the alternatives. First, the private bank relationship, the default of the 2000s, no longer covers what these families hold. A modern fortune is a mess of illiquid positions: operating companies, private fund commitments, real estate in three countries, a tokenized allocation, and equity with lockups. Private bank reporting assumes custody-able assets and produces a portfolio view with the messiest third missing. Second, the DIY answer, the family’s accountant and a lawyer on retainer, worked when the fortune was one company. After a liquidity event the family is running, in effect, an unregulated investment firm with employees in multiple countries and no one whose full-time job is the whole picture. Third, waiting is not neutral. Wealth transfer is already in motion: PwC’s global family business survey, cited in 2026 setup guidance, finds fewer than 30 percent of family businesses survive into the second generation, and every month a structure waits in a queue is a month the founding generation ages without governance in place. The cost of the queue is not the fee schedule; it is the unfilled succession window. Three Doors, Three Bills Against that backdrop there are three credible paths into professionalized wealth management, and the honest comparison is a cost comparison. The first door is building a single family office, typically in Singapore under the 13O or 13U tax exemption schemes or in Hong Kong under the FIHV concession. The second door is joining a multi-family office, a shared platform that spreads its investment, tax and governance staff across dozens of families. The third door is the hybrid many families now run: a lean outsourced core, a virtual family office coordinated by one senior adviser, with specialists pulled in per need. The following table prices all three as the 2026 market quotes them. Path Setup cost Annual cost Typical minimum Time to operational SFO in Singapore (13O/13U) S$150,000 to S$400,000 S$500,000 to S$1.35 million in year one S$20 million (13O) or S$50 million (13U) in AUM 6 to 12 months, approvals averaging 10.5 months SFO in Hong Kong (FIHV) US$50,000 to US$150,000 US$300,000 to US$600,000, HK$2 million minimum spend HK$240 million (about US$30.7 million) in AUM weeks to qualify, 4 to 6 months to staff MFO or virtual office minimal structuring 0.40 to 1.00 percent of AUM, plus retainers about US$25 million; some minimum fees near US$250,000 a year weeks Source: Singapore scheme cost breakdowns via Wealth Management Singapore , jurisdiction comparison via Tax.HK , SFO and MFO cost surveys via Atlatl Advisers and Value Add VC , 2026 Read the fine print under each bill because the fine print is where families get surprised. Singapore’s local spending requirement is tiered by asset size: S$200,000 a year below S$250 million of AUM, S$500,000 from S$250 million, S$1 million from S$2 billion, and salaries of the required investment professionals count toward it. The staffing bar is hard: two investment professionals under 13O, three under 13U, and Singapore compensation for credible candidates runs S$300,000 to S$800,000 a year per head. Hong Kong’s regime is cheaper and faster, two employees and HK$2 million of annual operating expenditure against a HK$240 million asset threshold, and it attaches no local-investment requirement, but its concession dates from May 2023 and its ecosystem of peer offices and service firms is shallower than Singapore’s 2,000-office bench. The MFO door has its own fine print: minimum annual fees commonly start between US$250,000 and US$500,000 in Asia, and the family trades bespoke control for a shared framework. In Singapore the trade has a regulatory shape as well, because a multi-family office managing assets for unrelated families is a licensed fund management business under the Capital Markets Services regime, subject to capital adequacy, fit-and-proper testing and conduct rules that a single family office, exempt as a related-party manager, never touches. That asymmetry cuts both ways: the MFO carries the compliance weight, and the family carries the platform’s decisions. Services are tailored within the MFO’s established playbook rather than bespoke, pooled access to private deals replaces direct deal control, and reporting follows the platform’s calendar rather than the family’s. The hybrid third door deserves its own inspection, because it is the one most families will use first. A virtual family office keeps little or no internal staff and coordinates a network of outsourced specialists, often with one MFO seat or a trusted senior adviser acting as the integrating hub. Its economics are the cheapest of the three, its governance is the thinnest, and its failure mode is well documented in the guidance: when the integrating person leaves, the network collapses into disconnected vendors. The structure works exactly as long as the family writes down who integrates, and re-writes it when that changes. What the Doors Cost in Basis Points Fixed fees and percentage fees only become comparable when you divide by the size of the fortune, and that division produces the cleanest decision instrument in the whole file. Value Add VC’s 2026 synthesis of the J.P. Morgan and industry cost surveys expresses both paths in basis points of assets per year, and the resulting table shows the crossover with unusual clarity. Size of fortune SFO cost in basis points MFO cost in basis points Cheaper path US$25 million about 800 about 90 MFO, by a wide margin US$100 million about 200 about 75 MFO US$250 million about 90 about 65 MFO, marginally US$500 million about 55 about 60 SFO, marginally US$750 million about 47 about 55 SFO Source: Value Add VC 2026 cost synthesis , drawing on the J.P. Morgan Global Family Office Report 2026 and industry cost surveys The crossover sits between US$250 million and US$500 million, which is materially higher than the marketing threshold that the single family office industry habitually quotes. Below that line, the SFO is not a status symbol, it is a cost leak: a US$2 million annual budget on a US$50 million fortune consumes 400 basis points a year, a permanent drag that no investment strategy reliably out-earns. Above it, control, privacy and the ability to hold illiquid and direct investments inside the taxed structure start to justify the fixed base. The hybrid third door exists precisely for the families in between: a US$60 million fortune paying 0.6 percent to an MFO costs about US$360,000 a year, buys institutional reporting, and leaves the family free to build its own office later, once the assets, the complexity and the second generation justify it. Succession: The Cost No Fee Schedule Shows Every path’s bill has a line item missing, and it is the one the corridor conversations circle back to. The purpose of all three doors is not this year’s return; it is the durability of decisions past the founder. PwC’s survey finding, fewer than 30 percent of family businesses surviving into the second generation, is the backdrop number, and the 2026 setup guidance draws the operational conclusion bluntly: a family office without a documented governance framework and succession protocol loses its core purpose within one generation. The structures differ in what they do about it, and the difference is easiest to see at the moment of the first board meeting. Under 13O or 13U, or inside an FIHV entity, the family discovers quickly whether its investment committee has real minutes, real dissent and a real conflict process, because the family wrote the charter and must now live inside it. Under an MFO, the equivalent meeting runs on the platform’s governance calendar, professionally minuted and documented, and the family’s own constitution can wait a year without anything visibly breaking, which is both the comfort and the trap. A 13U or FIHV entity puts the governance burden on the family, who must write the charter, define distributions and discipline their own board meetings. An MFO absorbs key-person risk institutionally, the platform survives staff turnover, but the family inherits the platform’s framework rather than writing its own. The hybrid path defers the question, which is legitimate only if the deferral is written down as such. Experience across the three doors suggests the sequence matters more than the choice: families who treat the first structure as a training ground for their own governance tend to graduate to the expensive door successfully, and families who buy the expensive door first tend to discover, around month eighteen, that they purchased infrastructure without ever drafting the constitution that would operate it. The paperwork that matters most in this file costs no fee at all: a one-page distribution policy, a named successor for the integrating role, and a written answer to the question of what happens to the structure if the founder stops showing up. Choosing in Practice Compressing the file into a decision rule is possible, and it fits on one screen. Below roughly US$100 million: the MFO or virtual path wins on arithmetic alone, 75 to 90 basis points against 200 to 800, and buys time to organize the family’s own governance. Between US$100 million and US$250 million: run the hybrid, outsource the core, and spend the fee savings on the governance documents that no vendor sells. Above US$250 million, especially with illiquid and direct holdings: the SFO door starts earning its fixed costs, and the jurisdiction question, Singapore’s ecosystem against Hong Kong’s speed and lower threshold, becomes the real decision. If the founding generation is past 65: the queue logic reverses. The right door is the one that opens soonest, because the succession window, not the fee schedule, is the binding constraint. Whatever the door: write the succession protocol before hiring anyone. It is the only line item that appears on none of the three bills and decides whether the structure outlives its founder. The corridor queue will keep growing as long as the daily net addition of fortunes keeps outrunning the supply of approvals, seats and staff. The families who handle that queue best are the ones who stop asking which structure is most impressive and start asking which bill, in basis points and in governance homework, they can genuinely pay. Data Basis Global and regional UHNW counts (551,435 in 2023, 713,626 in 2026, 948,241 forecast, 89 and 129 daily net additions, and regional growth rates) come from Knight Frank data compiled in this desk’s database. Singapore family office counts (2,000 incentivized offices in 2026, from 400 in 2020 and 1,400 in 2023) and the 10.5-month average application processing time come from the same compiled series. Scheme parameters (S$20 million and S$50 million thresholds, tiered local spending, staffing requirements, HK$240 million threshold, HK$2 million spending, two employees) come from Wealth Management Singapore and Tax.HK summaries of the MAS circulars and the 2023 FIHV ordinance. SFO and MFO cost ranges and the basis-point crossover table come from Value Add VC and Atlatl Advisers 2026 cost surveys. The succession figure comes from PwC’s Global Family Business Survey as cited in 2026 guidance. Data as of November 2026. Limitations The basis-point table blends cost surveys with differing methodologies and should be read as ranges, not quotes. Singapore processing time reflects this database’s compiled average rather than an official MAS statistic. Knight Frank counts define wealth thresholds on its own criteria, and regional growth rates cover its reporting period, not calendar years. MFO minimum fees vary widely by scope and region, and the hybrid path’s costs are indicative because no standardized price series exists for virtual family offices. Tax treatment of structures changes with each budget cycle and is not restated here. Sources Value Add VC – SFO and MFO cost crossover, 2026 Atlatl Advisers – SFO versus MFO costs and thresholds, June 2026 Wealth Management Singapore – 13O and 13U scheme cost breakdown, 2026 Tax.HK – Hong Kong and Singapore family office comparison (in Chinese) Aster of Asia – Asia family office setup guide, 2026 Knight Frank – global UHNW counts and forecasts (no public link) Singapore family office registry compilations (no public link) About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. This article was prepared by our expert team using insights and data provided through our MCP platforms. Contact: support@globalinfinitylabs.com
More

Indonesia import regulation 2026: what each change punishes

Three amendments to the Indonesia import regulation in 2026, dated 8 May, 4 June and 9 October, do not point the same way. One added commodities to the licensed list. One loosened a deadline that was holding cargo at the port. One opened a single narrow channel for used electronics and left the rest closed. Each amendment punishes a different mistake, and what now applies is three regimes stacked on one border. Preparing for the wrong one leaves the container where it is. Imports reached USD 210.63 billion in the first nine months of 2026, up 19.67% year on year, according to Statistics Indonesia. Raw and intermediate materials accounted for USD 150.57 billion and capital goods for USD 41.55 billion, roughly 91% of the total between them. Those two categories are what the licensing regime governs. 8 May: six commodities moved onto the licensed list Minister of Trade Regulation 11/2026, the first of the three Indonesia import regulation changes this year, was signed on 24 April and took effect on 8 May. It amends the 2025 rules on agricultural and livestock imports, adding feed wheat, soybean meal, mung beans, peanuts, broken rice for feed and pears to the commodities that require an import approval, and it requires a technical recommendation from the Ministry of Agriculture before that approval is issued. Two of the six carry an extra condition. Broken rice for feed needs a commodity balance document inside the application. Pears need proof of cold storage capacity and a surveyor report. The stated purpose is food self-sufficiency and price stability for domestic growers. Andri Gilang Nugraha, the ministry’s Director of Imports, said at the launch that mung beans and peanuts had been entering without volume or timing limits and that the absence of limits had reduced planting among local farmers. The operational effect is that the queue now starts in a different ministry from the one that issues the approval. A technical recommendation is a step with its own internal review, and the importer has no visibility into how long that review takes until the first application clears. The two May and June regulations are often read together because they landed six weeks apart. They amend different instruments. Regulation 11/2026 amends the 2025 rules covering agricultural and livestock goods. Regulation 18/2026 amends the 2025 rules covering imports in general. They are administered by different units, they fail in different places, and a fix applied to one does not travel to the other. 4 June: the deadline got flexible, the reporting got automatic Regulation 18/2026 is the second amendment to the 2025 general import framework, following an earlier one in 2025. The customs directorate’s regulation index dates it to 3 June and gives 4 June as the day it took effect. Three of its provisions entered force on 4 July and the fourth applied from 4 June. Article 29 allows a surveyor report to be issued after the import approval has expired, provided the pre-shipment verification was completed while the approval was still valid and the goods had already reached Indonesia. Before this, cargo that cleared inspection but missed the paperwork window was re-inspected, and re-inspection lands on the importer as cost and delay. Article 31 adds a matching requirement. The approval number in the surveyor report must match the one in the customs declaration, and the check runs electronically across INATRADE and the national single window. Articles 69 and 70 change what happens when an importer does not file the import realisation report. The ministry issues an electronic warning, the importer has 30 days, and after that the approval for the same commodity category can be suspended. The report records how much of an approved volume was actually imported. The ministry uses it to test whether the approval volume still matches demand, which is why the sanction attaches to the approval and why a shipment with a clean file can still trigger it. The suspension attaches to the category rather than to the shipment. An importer holding one approval across several product lines loses all of them over a report about one consignment, and the warning itself can go unread if nobody is monitoring the INATRADE account. Article 91A gives the government a route to override the regime when goods stop moving, on grounds of national interest, public welfare, a government programme or a presidential instruction. That provision took effect on 4 June, ahead of the rest. The same regulation also sets a review deadline for licence applications and authorises the system to issue an approval automatically once that deadline passes without a decision. Read with Article 29, the direction is consistent. Delay risk is being moved off the importer’s file and onto the ministry’s own clock, and the reporting side is where the discretion now sits. 9 October: one channel for used electronics Regulation 23/2026, the narrowest of the three Indonesia import regulation changes, amends the 2025 rules on non-new goods and non-hazardous waste and took effect on 9 October. It covers 136 tariff lines of used electronic goods and permits them only as raw material for designated processing industries inside the Batam free trade zone. Four conditions run together. The importer must hold a business identification number functioning as a producer import licence, which excludes trading companies operating under the general licence. An import approval and a surveyor report are both required, and technical verification has to be completed in the country of origin before shipment. The goods may not leave Batam for the rest of the customs territory. Monthly realisation reports go through the national single window. The rule establishes a legal route that did not previously exist for this class of goods. Equipment that arrives damaged, obsolete or intended for disposal falls under separate waste rules, and the framework does not cover electronic waste under another name. Batam’s status as a free trade zone is what makes the restriction workable. Goods enter without the duties that apply elsewhere in the country, so the line between the zone and the rest of the customs territory has to be enforced by document, which is why the conditions are documentary and why the monthly reporting is written into the authorisation itself. Three mistakes the Indonesia import regulation now punishes The first is treating an import approval as a one-off permission. The realisation report is a recurring obligation attached to the approval, and Regulation 18/2026 made the consequence automatic. The second is assuming a mismatch can be fixed at the counter. Validation reads the record, so an explanation offered at the port does not reset a field that the system has already compared. The third is using a trading licence for a production purpose. Regulation 23/2026 requires the producer form of the import licence, and the general form does not open the Batam channel. Scale decides how much each mistake costs. Raw and intermediate materials rose 21.11% in the first nine months of 2026 and capital goods 16.49%, both faster than consumer goods at 15.54%, so the licensing regime sits on the categories that are growing fastest. China supplied USD 76.16 billion of non-oil and gas imports in the same period, 42.77% of the total, ahead of Japan at 5.64% and Australia at 4.53%. Mechanical machinery, electrical machinery and plastics together made up about 37.95% of non-oil and gas imports, which is where a classification error reaches furthest. Before the next shipment Four checks follow from the three regulations, and between them they cover most of what the Indonesia import regulation now asks of an importer booking a first shipment. Match the classification against the licensed list in force now, not the list that applied when the order was placed. The commodity list changed on 8 May, and the framework for used equipment changed on 9 October. Confirm the approval number reads identically in the surveyor report and the customs declaration before the vessel arrives. The comparison happens on the record. Put the realisation report on a calendar with the same weight as the shipping schedule. The 30-day warning runs from an electronic notice, and missing the notice does not pause it. For used equipment, confirm the producer form of the import licence before booking freight. The general form does not reach the Batam channel. What is not published Three gaps affect a booking decision and none of them has a published answer under the Indonesia import regulation as it stands. The ministry has not issued average processing times for technical recommendations under Regulation 11/2026, so the queue length for the six new commodities is unmeasured. Customs reports inspection outcomes in aggregate but not by importer, so the share of a given company’s consignments routed to physical inspection cannot be benchmarked against a peer group. And the implementing guidance for the Batam framework has not appeared, which leaves the definition of designated processing industries to be settled case by case. The next signal is that guidance. Until it is issued, the Batam channel exists as an authorisation, and the Indonesia import regulation for used equipment will be defined by the first approvals granted under it. This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More

Bangkok trade fair 2027: Informa merges three shows

ProPak Asia left BITEC in June 2026 after more than a decade in Bang Na and grew by 5,000 square metres in the move, the largest single change behind the Bangkok trade fair 2027 calendar. The 2025 edition used 55,000 square metres at BITEC with 2,000 exhibiting brands from 42 countries and 72,000 visitors. The 2026 edition opened at IMPACT Challenger in Muang Thong Thani on 10 June across 60,000 square metres, listing 2,500 brands, 13 national pavilions and more than 80,000 visitors in the organiser’s post-show release. The 2027 edition goes further. ProPak Asia runs 9-12 June 2027 at IMPACT alongside ASEAN Paper Bangkok and LOUPE Southeast Asia, with floor space up a further 15% and more than 80% of advance space reserved, according to Informa Markets Thailand’s announcement. Three shows, one week, one venue. That is the shape of the June block, and it changes what an exhibitor gets for one trip. What moved, and what it displaced ProPak Asia had run at BITEC every year from 2007 to 2025, according to its published edition history. Its footprint reached 55,000 square metres, close to the limit of a single BITEC hall block. The arithmetic behind the move is visible in the two floor plates. A show that grows every year eventually runs out of contiguous space in a hall it has already filled, and the alternative is splitting exhibitor categories across a second block. A single level of 60,000 square metres removes that choice for one edition and leaves room for the 15% increase booked for 2027. IMPACT offered that floor plate without internal columns. Challenger Halls 1 to 3 cover 60,000 square metres, measuring roughly 131 by 459 metres under a 25.7 metre ceiling, and the wider complex adds another 47,000 square metres across Halls 5 to 12. The label show moved too. Labelexpo Southeast Asia ran at BITEC from 8 to 10 May 2025, its most recent edition under that name. It now trades as LOUPE Southeast Asia, and the 2027 edition sits inside the ProPak week at IMPACT rather than on its own dates in Bang Na. The 2025 edition listed 6,019 visitors, 195 exhibitors and 5,459 square metres, according to the show’s published statistics. Food and agriculture shows moved in the same direction. VIV Asia 2027 runs 10-12 March at IMPACT with 38% more exhibition space than its previous edition, expanding into Halls 1 to 7. The 2027 layout adds Hall 5 for country pavilions, Hall 6 for feed and grain technology and Hall 7 as a meeting area, and it co-locates with Meat Pro Asia and HortiAgri Next Asia. BITEC held the industrial block. Manufacturing Expo still runs there with InterPlas Thailand, InterMold Thailand, NEPCON Thailand, Surface and Coatings, Automotive Manufacturing and Assembly and Automation Technology, all dated 16-19 June 2027. METALEX returns in November. The 2027 calendar, venue by venue The Bangkok trade fair 2027 calendar divides along a clean line once the moves are mapped. BITEC’s year opens with two small logistics shows sharing EH100 on 4-5 March, Thai Cargo Expo and Smart Delivery Expo. Food Pack Asia and Thailand Industrial Fair follow on 10-13 March in Halls 101 and 102. The automation and subcontracting block runs 12-15 May with Subcon Thailand, InterMach and MTA Asia. June is thinner at BITEC than it was in 2025. Thailand Franchise and Business Opportunities runs 10-13 June, and the Manufacturing Expo group takes 16-19 June. Food Ingredients Asia follows on 1-3 September, with FHT and the hospitality technology show on 15-18 September. IMPACT has published a shorter list. Beyond VIV Asia in March, it has ABEE, ASEE, AWE and ARHC running together on 17-19 March, four energy and cleanroom events that share one visitor badge. LIFT EXPO Thailand runs 28-30 April, and the ProPak block takes 9-12 June. Dates for the second half of its 2027 calendar were not listed at the time of publication. The one date collision left March is the only month where the Bangkok trade fair 2027 calendar stacks two competing food and packaging shows into one week. Food Pack Asia runs at BITEC from 10 to 13 March and VIV Asia runs at IMPACT from 10 to 12 March. They overlap for three of the same four days, and both carry processing and packaging equipment. The two shows differ in scale and in ownership. Food Pack Asia is organised by Digiview Advertising Group and its 2027 factsheet lists Halls 101 and 102 at BITEC. VIV Asia covers animal protein from feed to processing and now fills seven halls. For a food manufacturer sourcing a filling or packing line, both are relevant, and they cannot be covered in sequence. For a regional distributor with four days in Bangkok, the calendar forces a choice. June no longer produces that problem. What used to be two separate trips, ProPak in June and Labelexpo in May, is now one week in one venue. Whether that is better depends on what the exhibitor sells. What a square metre costs Space rates are published unevenly across the Bangkok trade fair 2027 season, and BITEC’s are the easier to check. The rate card for a 2026 BITEC industrial show lists raw space at THB 13,000 per square metre, or USD 380, with a 24 square metre minimum. Shell scheme runs THB 16,000 per square metre, or USD 465, with a 9 square metre minimum. A THB 2,500 application fee applies per exhibiting company, and all rates exclude 7% VAT. At those rates a 24 square metre raw space booking costs THB 312,000 before VAT, and a 9 square metre shell stand costs THB 144,000. Build, freight, rigging and staff costs sit on top and usually exceed the space charge for a custom stand. Those figures come from one show’s brochure and move by event and by year. They still indicate the order of magnitude for an industrial hall at BITEC. On cost alone, shell scheme carries a smaller minimum at a higher rate, while raw space starts at 24 square metres at a lower one. Machinery exhibitors take raw space because floor loading and rigging rule out a packaged stand. Build-up rules differ from venue to venue. At BITEC the build-up and dismantling windows are set by each show organiser in the exhibitor manual rather than by the venue, and custom stand contractors normally get earlier access than shell scheme exhibitors. The binding deadline is the organiser’s manual date, not the venue’s calendar. IMPACT quotes space show by show, and the constraint that matters there is distance. Challenger Halls 1 to 3 sit in one continuous block, while Halls 5 to 12 sit elsewhere on the site, which changes freight routing, build-up windows and how long a visitor needs to cross the show. Choosing on buyer type The Bangkok trade fair 2027 split maps onto buyer type more closely than the calendar suggests, which makes the venue decision simpler than it looks. If the target buyer is a plant manager sourcing machine tools, moulds, automation or surface treatment, the BITEC calendar concentrates those shows into May and June with METALEX in November. Three trips cover the industrial year. Visitors can check the fit before booking. Most Thai industrial shows publish a post-show report listing visitor numbers by job function and by country, and the useful filter is whether procurement, production engineering or plant management titles appear at all. A show that reports only a total attendance figure leaves an exhibitor unable to tell whether the people walking the aisle sign purchase orders. If the target buyer sits in food, beverage, agriculture, paper or packaging, the 2027 dates put those shows at IMPACT in March and June. Two trips cover it, and the June block now holds upstream and downstream in one site. Access differs. BITEC sits on Bang Na-Trat Road around 20 kilometres from central Bangkok and about 15 kilometres from Suvarnabhumi Airport. IMPACT sits in Nonthaburi to the north and is served by the MRT Pink Line at two stations, MT01 at the venue and MT02 at the lake. What is still unpublished Two gaps affect Bangkok trade fair 2027 planning. IMPACT has not listed the second half of its calendar, so any exhibitor targeting November or December has no confirmed dates yet. BITEC has dated most of its 2027 shows but has not published hall allocations for them, and the hall determines ceiling height, rigging limits and whether a two-storey stand is possible. The March collision could still dissolve. Organisers move dates before exhibitor manuals are issued, and neither show has published a final floor plan. What is fixed is the direction of travel. The multi-hall shows have moved to the site with 60,000 square metres on one level, and the industrial shows have consolidated at the site with the older hall inventory. Any Bangkok trade fair 2027 booking made on 2025 assumptions is being made against a calendar that no longer exists. This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com To share industry insights, report corrections, or submit story tips: editors@globalinfinitylabs.com or https://www.globalinfinitylabs.com/submit.
More