The $100 Bet: Moomoo’s Binary Options Push Is a Gamble on Retail Discipline Business

The $100 Bet: Moomoo’s Binary Options Push Is a Gamble on Retail Discipline

(SeaPRwire) - The core issue is simple. Binary Return Options strip away nuance. They reduce a market view to a binary outcome: right or wrong. Moomoo, claiming over 31 million users worldwide, is pushing this product to U.S. retail investors as a way to "broaden access." But access is not the same as wisdom. This isn’t just a new ticker symbol. It’s a shift in how everyday traders think about risk. The product promises clarity. In practice, it invites a casino-like mindset. When the payout is fixed at $100 and the loss is the premium, the psychology changes fast. The facts are specific. Moomoo is one of the first U.S. retail brokerages to offer these contracts at launch via NYSE American. The initial lineup covers twelve securities. Six are stocks: AAPL, AMZN, NVDA, ORCL, SPCX, and TSLA. Six are ETFs: GLD, IBIT, IWM, SLV, SPY, and TLT. Investors get five consecutive weekly expiration series. The contract is European-style. It expires worthless if the condition isn’t met. This structure removes the ability to exit early. It locks in the position. For traders used to dynamic hedging, this rigidity is a significant change. The commercial logic is clear. Neil McDonald, CEO of Moomoo U.S., frames this as making it easier to translate a market view into a trade. Kevin Tyrrell, Chief Product Officer at NYSE, cites volume growth and interest in newer products. Moomoo pairs this with tools like the P&L Simulator and Strategy Builder. These are paid features under Moomoo Engine, costing $3.99 a month. The goal is retention. By offering a simplified, high-stakes product, Moomoo attracts traders who want institutional-grade insights without the complexity. The subscription model ensures a recurring revenue stream. The product drives the subscription. The subscription drives the tool usage. It’s a closed loop. Watch the next twelve months. The real test isn’t adoption. It’s whether Moomoo can manage the churn and the complaints. If retail traders lose money rapidly, the platform becomes a liability. The risk is not just financial. It’s reputational. Moomoo needs to prove that these tools educate, not just entice. If the user base treats this as a slot machine, the "smart trading" narrative collapses. The market will judge Moomoo not by the launch, but by how many users walk away profitable after a year. Until then, it’s a bet on discipline that hasn’t been proven.
More
They’ve Built Your AI Model For Free. Arca Just Put A Price Tag On It. Business

They’ve Built Your AI Model For Free. Arca Just Put A Price Tag On It.

(SeaPRwire) - [Paragraph 1]Every knowledge worker feeding a prompt into an AI tool overnight is quietly donating material. Back-and-forth threads, dead ends corrected, fixes that held — that stack sits idle on your hard drive until you purge it. Nobody gets paid. Nobody even sees it has value. That changes now, and the shift matters far more than any single user wallet will admit.[Paragraph 2]Arca went public on November 11 after an invite-only window that began October 13. You install the desktop app. It scans the sessions Claude Code, Codex, Cursor and Claude Desktop already store locally. You pick what to upload. Arca strips names, file paths, account details and keys right on your machine. A quote range returns. Confirm and it goes to review. Withdraw and the upload vanishes. Approved sessions pay out weekly.[Paragraph 3]Under the hood sits Brevis technology, including the open-source Pico zkVM, which lets applications prove computation results without exposing the underlying data. That is the verifiable-computing layer carrying over from Brevis into a consumer data-purchase model. Short sessions don't qualify. Every submission is reviewed before payment clears. Connecting a GitHub profile can raise session value, though it isn't mandatory. During the Launch Challenge through November 30 an additional $10,000 in prizes sits on top of normal payouts.[Paragraph 4]From a unit-economics vantage point the play is elegant. User-generated session data becomes a commodity input. Each verified, cleaned, de-identified thread can feed downstream models or fine-tuning pipelines. Arca takes the margin between what it pays per approved session and what resellers or training clients ultimately bid for aggregated data bundles. No upfront data purchase. No licensing negotiations with individuals. Just organic accumulation priced at the lowest acceptable yield.[Paragraph 5]Where the loop strains is trust architecture and compliance friction. Anonymisation happens locally before upload, but every participant still routes personal work habits through a new desktop agent with background-scanning behaviour. The longer the program runs, the heavier the dependency on clean provenance to sell to serious buyers. One mislabelled session leaking corporate references inside approved uploads erodes that trust instantly and spreads fast through buyer channels.[Paragraph 6]Sign up during the current $10,000 bonus window if you want exposure, but treat it as temporary upside rather than income. After the promotional period closes the real question is whether enough sessions clear verification at yields that make repeated participation worth the privacy tradeoff.
More
Paws, Push Notifications, and Platform Gatekeepers: The Quiet Battle for Real-Time Pet IoT Business

Paws, Push Notifications, and Platform Gatekeepers: The Quiet Battle for Real-Time Pet IoT

(SeaPRwire) - Every cat visit at a smart feeder lasts only tens of seconds. If the notification lags, the live stream opens to an empty bowl. This narrow window of real-time interaction is the ultimate bottleneck for IoT pet care platforms. Most people think push notifications are just marketing spam. They are actually the critical infrastructure keeping physical and digital worlds in sync. Purrrr understands this brutal truth. The platform relies on split-second alerts to drive remote feeding and community engagement. Without millisecond-level reliability, the entire user loop collapses. This is the unspoken reality of real-time consumer IoT. Aurora Mobile's EngageLab AppPush is now powering Purrrr's global cat rescue network. The platform has deployed over 20,000 smart feeders across 200 cities in more than ten countries. This massive physical footprint demands a highly resilient digital notification layer. Purrrr integrated AppPush to solve the chaos of global network inconsistencies. The system prioritizes cat visits and device alerts to handle sudden traffic spikes. It delivers sub-second push notifications even under peak loads. Multi-channel routing ensures messages reach users on any handset model. This technical backbone supports the app's rapid global expansion. The results speak volumes. Purrrr surpassed 1.75 million global downloads and hit number one on Thailand's iOS social chart. A single-day peak of 44,000 downloads proves the market demand. EngageLab's time-zone-aware engine keeps the experience humane. It silences non-urgent night alerts while keeping critical device warnings immediate. The platform also uses multidimensional user tags to customize messages. Volunteers get food replenishment alerts and healthcare tips. This shifts the app from a simple hardware controller to an active pet care network. User retention is the real metric here. The broader tech industry is quietly fighting a battle over engagement infrastructure. Every enterprise now competes for user attention in a saturated digital space. The difference between a successful app and an abandoned one often comes down to notification latency. Aurora Mobile is positioning EngageLab as the universal pipeline for these real-time interactions. By offering an AI-first engagement platform, they target the core pain of customer churn. This goes far beyond a simple cat feeder app. Any business relying on real-time events, like ride-hailing or logistics, needs this infrastructure. The gatekeeper of push notifications holds immense power over app retention. Many growing startups initially try to build their own push channels to save costs. They quickly run into network fragmentation and low delivery rates. EngageLab leverages direct integrations with FCM, APNs, and major device manufacturers. This multi-channel routing is incredibly hard to replicate individually. It provides reliable coverage even in weak connectivity zones like Southeast Asia. For global enterprises, outsourcing this complexity to a specialized SaaS platform is a no-brainer. The economics of maintaining proprietary infrastructure simply do not justify the overhead. Third-party platforms win by offering superior reliability at a fraction of the cost. The future of mobile interaction will not rely on manual app opens. Autonomous AI agents will trigger real-time actions directly through these notification layers. Platforms that fail to build low-latency, intelligent engagement pipelines will face immediate user decay. The next wave of tech valuation will center on who owns the real-time interaction gateway. Companies must prepare for a world where the notification bar is the primary interface. The silent infrastructure battle is already underway, and the losers will be invisible. The push notification layer will become the primary operating system for enterprise retention. Late adopters will face immediate obsolescence.
More
Pivot or Peril: How Sono Traded Solar Dreams for a Micro-Bitcoin Balance Sheet Business

Pivot or Peril: How Sono Traded Solar Dreams for a Micro-Bitcoin Balance Sheet

(SeaPRwire) - Sono Group just posted a net income of $0.6 million for the third quarter of 2026, pivoting cleanly away from its old identity as a struggling solar vehicle pioneer. Compared to the $1.4 million loss recorded back in Q3 2025, the ledger looks remarkably green. Yet this sudden turnaround is not born from selling hardware. It stems entirely from a complete corporate reconstruction centered on holding digital assets and monetizing volatility through structured options. The company unloaded its legacy solar business on May 4, 2026, leaving behind the heavy industrial burns of automotive manufacturing. By September 30, 2026, the balance sheet held precisely 53.40 Bitcoin valued at $4.4 million, alongside a cash reserve of just $0.5 million. Operating income crawled to a modest $0.1 million, while total Q3 digital asset treasury income hit $0.7 million. This figure combined a $1.5 million fair-value gain on the crypto holdings with $0.2 million of gross covered-call option income, offset by $1.0 million in losses from written covered calls that finished in the money and required physical delivery of the underlying coin. Beneath the headline profitability, the capital structure remains highly vulnerable to external pricing shocks and pressing debt obligations. General and administrative expenses dropped 24% to $0.6 million, trimming corporate fat, but management simultaneously disclosed substantial doubt regarding the enterprise's ability to continue as a going concern. A principal amount of $5.05 million in convertible debentures matures between January and April 2027. To survive the coming quarters, the firm relies on a mix of further debt or equity raises, selective Bitcoin liquidation, and ongoing premium yields generated via its institutional framework with Blockchain.com. Meanwhile, corporate restructuring moves forward on two distinct fronts. Shareholders will vote on December 11, 2026, to redomicile the legal seat from the Netherlands and Luxembourg to Delaware, simplifying compliance and aligning the domicile with leadership's U.S. base. Additionally, a non-binding letter of intent signed on August 31, 2026, outlines a potential business combination with Sports One, a newly formed entity targeting minority stakes in major professional sports franchises. Whether this sports venture materializes depends on definitive agreements and a separate shareholder vote, keeping the future trajectory tied directly to speculative market appetite and continuous capital inflows.
More

Charming Medical Drops Off Nasdaq: The TCM Hype Meets The Reality Check

(SeaPRwire) -Nasdaq just pulled the plug on Charming Medical. The delisting is now official. The company failed to request a hearing by the November 5, 2026 deadline. Trading halts at the open on November 9, 2026. This is not a standard compliance miss. It smells like a total failure of basic market hygiene. Look at the SEC files. From November 12 to November 25, 2025, trading was suspended. The reason? Unknown persons recommended buying or holding shares via social media. They asked for transaction screenshots. It was a classic pump-and-dump play. Nasdaq halted trading on November 26, 2025. That halt never ended. The stock never recovered. The delisting relies on Listing Rule IM-5101-4. This rule grants Nasdaq broad discretion to delist companies involved in potential misconduct. The key trigger here is the SEC’s temporary suspension for manipulation. The company claims its operations remain normal. But the market signal is clear. Investors have lost trust. Where does this leave the TCM-inspired wellness sector? It is a graveyard for speculative micro-caps. Without a verifiable price discovery mechanism, these stocks become tools for manipulators. For anyone holding MCTA, check the OTC availability. Liquidity will be thin. Volatility will be high. Protect your capital. The era of easy tech listing for niche lifestyle plays is over. Nasdaq is cleaning house.
More

The Anti-CTLA-4 Safety Paradox: Why Adagene’s Dosing Gamble Defines the Next Immunotherapy Wave

(SeaPRwire) -MSS colorectal cancer has been a dead zone for checkpoint inhibitors. PD-1 blockers work in MSIs, not MSS. Adding CTLA-4 creates dose-limiting toxicity. Adagene argues their masked antibody solves this. Peter Luo, Adagene’s R&D chief, claims the trial identifies the right dose for Phase 3. He highlights Sanofi’s equity investment as validation. The goal is to unlock value where legacy CTLA-4/PD-1 combos already hold FDA approval. This positions muzastotug as a backbone for early and late-line treatments. Adagene completed enrollment in its randomized Phase 2 trial on November 9, 2026. Sixty patients participated. The trial tests muzastotug with Merck’s Keytruda in late-line MSS colorectal cancer without liver metastases. It follows a 2025 FDA meeting. The primary endpoint is overall response rate. Secondary metrics include duration of response, progression-free survival, and overall survival. Initial results are expected in the first half of 2027. This data will inform the Phase 3 dose regimen. Two arms compete for the optimal protocol. Arm A uses 10 mg/kg every three weeks for four doses. It switches to 10 mg/kg every six weeks for maintenance. Arm B starts with 20 mg/kg every six weeks for two doses. Maintenance follows at 15 mg/kg every six weeks. Both use induction to activate the drug in tumors. Then maintenance sustains exposure. The FDA agreed with Adagene’s design. They accepted a standard-of-care control arm. No muzastotug monotherapy arm is required. The Phase 3 primary endpoint will be overall survival. Adagene owns worldwide commercial rights to muzastotug. This asset targets a unique CTLA-4 epitope in regulatory T cells. The SAFEbody technology masks the binding domain. It activates only in the tumor microenvironment. This minimizes on-target off-tumor toxicity. The company leverages its Dynamic Precision Library platform. It combines computational biology and AI. The design addresses global unmet needs in solid tumors. The strategy avoids the toxicity traps of traditional CTLA-4 therapies. The market implication is stark. MSS colorectal cancer lacks effective immunotherapy options. Legacy combinations struggle with toxicity and efficacy in this setting. Adagene’s approach targets the safety bottleneck directly. If the 1H 2027 data validates the dose, the path to Phase 3 is clear. The FDA endorsement of the trial design reduces regulatory risk. Investors should watch for the specific dose regimen selected. This choice dictates the future commercial viability and combination potential of the drug.
More

Playing Both Sides of the Street: Diginex Prepares for a Post-Deal World While Keeping Resulticks Alive

(SeaPRwire) -Diginex is navigating a high-stakes corporate tightrope. The London-headquartered RegTech firm has pushed its deadline to acquire Resulticks. This extension is not just a minor administrative step. It exposes the deep friction in technology M&A. The core contradiction is clear. Diginex wants to complete this transaction, but it cannot wait indefinitely. Meanwhile, the company is preparing its house for a potential storm. It is convening a major shareholder meeting to overhaul its capital structure. This restructuring is entirely independent of the acquisition. Investors are watching closely. Can the firm balance these two paths without losing confidence? The amended share purchase agreement was signed on August 14, 2026. The Long Stop Date has shifted to November 19, 2026. It originally expired on October 30, 2026. No termination notice has been delivered by either side. Shareholders previously approved the acquisition on October 8, 2026. The board has now scheduled an EGM for November 20, 2026. The record date is November 6, 2026. The main proposals are bold. First, an increase in authorized share capital. The limit rises from US$200,000 to US$520,000. This creates 800,000,000 new ordinary shares. Second, a ten-for-one share consolidation. The consolidation will create 129,500,000 ordinary shares. Crucially, these proposals are not conditional on the acquisition. They will take effect even if the deal fails. If the transaction closes first, the October consolidation will be implemented instead. This avoids a double consolidation. Decoupling the share consolidation from the M&A closing is a smart commercial move. It allows Diginex to clean up its capital structure without waiting for the Resulticks deal. A ten-for-one consolidation changes how the market perceives the stock. It moves the share price into a more institutional-friendly range. This attracts serious capital and improves liquidity over time. The capital increase also provides a financial cushion. Diginex can use this dry powder to fund organic growth or future acquisitions. The RegTech sector is highly competitive. Firms need operational flexibility to survive. By preparing for both outcomes, the board shows true corporate discipline. The end-game is a leaner, more resilient entity. Operational discipline will define the next chapter for this London-based tech player.
More

The 1-Millisecond Bet: Why LUXEED’s “Emotionless” Tech Stack Might Save It From Being Just Another Chinese Luxury Brand

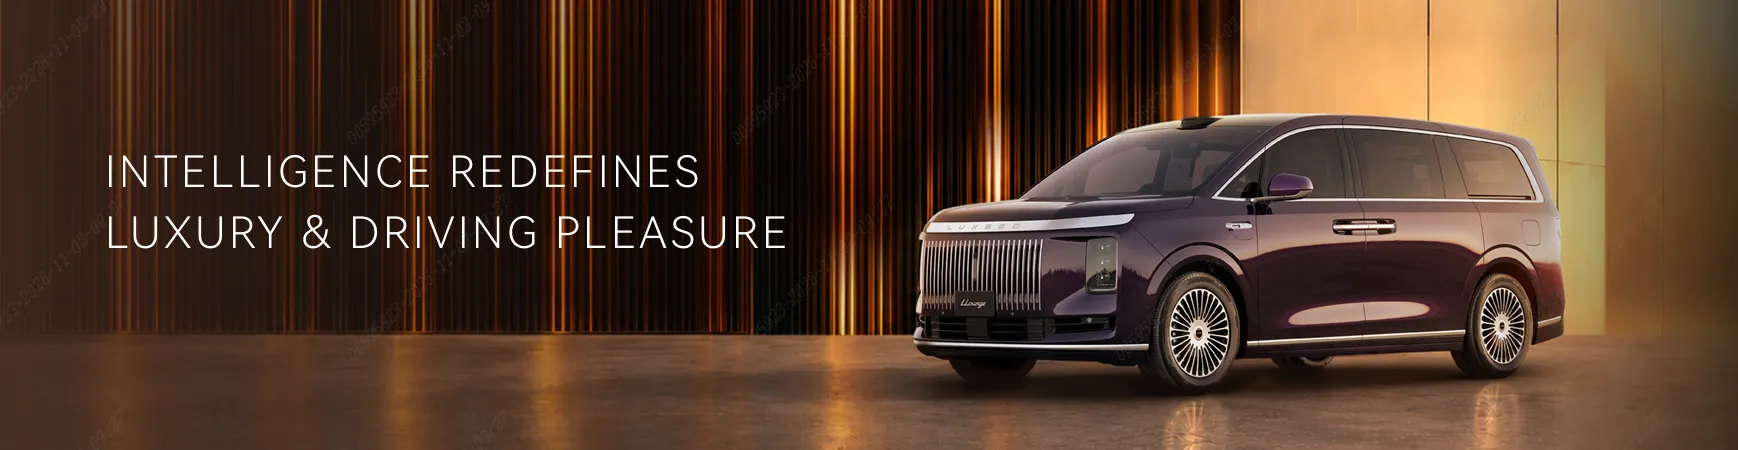
(SeaPRwire) - Wuhu isn’t where you expect a global luxury debut. LUXEED chose a valley in China’s Anhui province for its global launch on October 21, 2026. This choice signals a specific strategy. They want to be recognized at 100 meters. The slogan is loud. But the hardware is the real argument. You can’t fake a 5.3-meter turning radius on a car that long. The press release touts “TIANDIRENHE” design philosophy. That is poetic filler. The truth lies in the sub-millisecond decision latency of their Vehicle Motion Control system. Luxury buyers don’t care about heaven, earth, and humanity. They care about whether the car feels alive when you twist the wheel. LUXEED is betting that engineering precision will override traditional brand mystique. Look at the models. LLounge targets executive poise with vertical L-shaped headlamps. Stormax goes sporty with horizontal dual-L lights. The distinction is clear. The interior follows a “Clear Architecture” and “Living Aura” approach. They mention 3,600 MPa steel. Actually, the text says 2,400 MPa steel. That is a significant figure for crash strength. They pair this with a “3-6-0” safety system. The cabin uses an 8397 intelligent chip. This is not a new SoC. It is a mature Snapdragon 8 Gen 1 variant. Using a slightly older flagship chip in a new luxury model is a calculated move. It lowers the bill of materials while maintaining sufficient compute for the onboard AI model. The 33-speaker audio system and one-second adjustable-tint glass are standard luxury features. But they are the expected baseline, not the differentiator. The intelligence layer is where the subtext gets interesting. They cite three pillars: one-stage end-to-end learning, reinforcement learning, and world models. This is standard AI boilerplate for autonomous driving. The “world model” claim is particularly vague. It suggests the car anticipates scenarios rather than just reacting. The 8397 chip handles multimodal sensing. It recognizes occupant states. This allows for proactive interactions. However, the real value proposition is the Vehicle Motion Control. Sub-1-millisecond latency between decision and actuation is a massive engineering win. Most modern cars operate in the 5 to 10 millisecond range for chassis adjustments. LUXEED claims they orchestrate core subsystems with that speed. If true, the car will feel unnaturally responsive. It will move before your brain fully processes the input. That is a sellable feature. It creates a visceral connection to the machine. The supply chain implications are hidden in the specs. Dual-chamber air suspension and ±7° rear-wheel steering are complex, expensive hardware. These components are usually reserved for top-tier European models. LUXEED is integrating them into a platform that also uses older-generation SoCs. This suggests a hybrid approach. They are spending money on the chassis where the driver feels it. They are saving money on the compute stack where the driver interacts via a screen. This is a smart allocation of capital. It signals that LUXEED views the chassis as the primary luxury experience, not the infotainment system. The global debut at Shenshan Intelligent Valley reinforces this. They are building a hardware-first identity. The brand is not about the screen. It is about the steel, the suspension, and the speed of the reflexes. Expect the competition to focus on the AI claims. But the market will judge the car on how it drives. The sub-millisecond control loop is the real product.
More
OMODA X and the 1,015-Kilometer Truth: What Wuhu Actually Proved Business

OMODA X and the 1,015-Kilometer Truth: What Wuhu Actually Proved

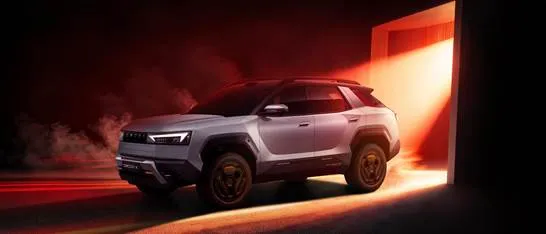
(SeaPRwire) - The Wuhu summit had plenty of lifestyle gloss. Miss World guests walked a runway. Owners from four continents sang the brand's theme song. OMODA X, a new "crossover" vehicle, made its global debut. But behind that spectacle sits an industry pain point: can the hardware survive the marketing? Automakers love to talk about "vibes" and creativity. Real engineers care about numbers. This event offered both, which is uncommon. The real test, however, was the hybrid marathon results. The official story says OMODA X is a CROSS OFF-ROAD VEHICLE, blending SUV practicality, off-road capability, and sports car character. That hybrid positioning is smart, but the real novelty is how the company used it. Four users from Indonesia, Brazil, South Africa, and Poland each created custom concepts. One tailored the car for outdoor gear. Another leaned into music and local culture. The industry subtext here is that "crossover" is a broad label meant to capture multiple buyers. But by letting users reinterpret the platform, OMODA moved from spec-sheet marketing to actual co-creation. That is a genuine shift in how a global car brand listens. The second half of the event was harder data. The new 5-kWh HEV system introduced Super Quiet Mode and Super Life. Then the OMODA Super Hybrid Marathon put three models on real roads, mixing urban, highway, and lakeside routes. The OMODA 5 NEXT SHS-H recorded 4.5 L/100 km and traveled 1,015 km on a single tank. The OMODA 4 SHS-H managed 4.9 L/100 km and 911.3 km. Those numbers are the proof. The Super Intelligent Experience Lab also showed SIVP valet parking and SIAS natural language interaction. The subtext is clear: these features work outside the showroom. Chery's broader portfolio, including LUXEED and AiMOGA's MOBO robot, hints at a wider tech push, but the focus here stays on real-world driving. The blunt supply chain assertion is this: OMODA & JAECOO has expanded to 79 markets, including 23 European countries, with over 1.4 million cumulative sales. That global footprint is the moat. But the durability of that moat depends on whether the hybrid system can be scaled consistently. If the 1,015-km result holds up across different markets, OMODA has a real shot at owning the crossover niche. If not, the "vibe" is just noise.
More

SDA’s $10M Buyback: A Liquidity Lifeline or Long-Term Confidence Bet?

(SeaPRwire) - SunCar Technology Group, trading under the ticker SDA, just announced a share repurchase program. The board authorized buying back up to $10 million worth of Class A ordinary shares. This move is framed as a signal of confidence in long-term growth prospects. For a company with a relatively small market cap, $10 million is not a trivial sum. It represents a meaningful portion of available cash reserves. The timing matters. The program is expected to execute within the next three months. This short window suggests urgency. The company intends to fund these repurchases through cash on hand and cash generated from operations. No new debt issuance is mentioned. No equity dilution is planned. This is a pure balance sheet exercise. The announcement details specific mechanics. Shares will be repurchased from time to time on the open market. Alternatively, privately negotiated transactions may occur. The company cites compliance with Rule 10b5-1 and Rule 10b-18 of the Securities Exchange Act of 1934. These rules provide safe harbors for buyback timing and volume. They minimize market impact. The timing and actual number of shares repurchased depend on regulatory restrictions. Market conditions also play a role. Price, manner, and volume are all regulated factors. The goal is to avoid suppressing the stock price during the purchase period. This is standard corporate finance hygiene. It is not innovative. However, for a company listed on NASDAQ, adherence to these rules is non-negotiable. The release emphasizes minimizing impact on the market for Class A Ordinary Shares. SunCar positions itself as a leader in China’s auto eInsurance market for electric vehicles. It also claims leadership in the B2B auto services market. The company was founded in 2007. It operates cloud-based platforms connecting drivers with auto services and insurance. A nationwide network of sales partners supports this model. The company’s intelligent cloud platform allows enterprise customers to manage auto eInsurance and services. Drivers access tens of thousands of independent providers through a single application. The forward-looking statements section highlights plans for AI-powered services. It mentions expected improvements in customer experience. It also cites potential cost reductions. These are standard growth narratives. They aim to offset the immediate capital outflow of the buyback program. The core tension here is between short-term shareholder returns and long-term operational needs. A $10 million outflow reduces the cash buffer. This matters if SunCar faces unexpected economic downturns. It also matters if growth initiatives require heavy upfront investment. The release notes risks associated with raising additional funding. It mentions dependence on key personnel and ability to attract talent. Buying back shares now signals that the board sees the stock as undervalued. Or it signals that the company has excess cash relative to its immediate operational needs. There is no explicit mention of dividend policy. The buyback is the chosen mechanism for returning value to shareholders. Investors should watch the execution pace. If the company rushes to complete the $10 million target in three months, it may move the market. If it spreads purchases slowly, the impact is muted. The release explicitly states an effort to minimize impact. Regulatory constraints like Rule 10b-18 limit daily purchase volumes. The company must balance speed against market disruption. Investors holding SDA should track the number of shares repurchased monthly. This data will reveal the true urgency behind the program. The gap between stated confidence and actual cash utilization is where the real signal lies. Expect the stock to react cautiously to the buyback announcement. The $10 million cap sets a ceiling on support. If the share price falls, the buyback provides a bid. If the share price rises, the company may slow down or stop buying. This asymmetric behavior creates a floor for the stock price in the near term. The company’s reliance on operational cash flow to fund this means it is not depleting long-term strategic reserves aggressively. The end state is a smaller share count and a tighter float. This often leads to higher earnings per share. The immediate impact is psychological. The longer-term impact depends on whether SunCar can sustain its growth narrative while reducing its capital base.
More

2.56 Million Cars Sold, and JETOUR’s Real Product Is a Crowd in Rio

(SeaPRwire) - Selling SUVs is a solved game. Building a tribe around them is not. That gap is where most young car brands stall out, especially overseas. JETOUR, founded only in 2018, is betting that the answer is fan culture, and it is staging that bet loudly. On November 18 to 19, the brand takes over Rio de Janeiro's Estádio Olímpico Nilton Santos, the athletics venue of the Rio 2016 Olympics, for its 2026 Global Fan Festival. Owners and off-road enthusiasts from five continents are flying in under the theme "Journeyed by Passion." The numbers behind the pageantry matter more than the fireworks. JETOUR has pushed cumulative global sales past 2.56 million vehicles across more than 100 countries and regions. Its JETOUR CLUB system counts over 300 owner clubs and 30,000-plus core members, who ran more than 500 owner events in 2025 alone. The festival itself has rotated from the Liwa Desert in the UAE to a fan music festival in South Africa, and now Brazil. Brazil is no random pick. JETOUR has already launched the T1 i-DM and T2 i-DM there, tailored to local demand. The Rio program doubles down with a vehicle modification exhibition and Brazil-themed test drives. As one Middle Eastern owner put it, JETOUR is "more than a car," a way of life and the courage to explore. Strip away the sentiment and the commercial loop is clear. Community events convert buyers into unpaid marketers, and localizing the festival in a growth market like Brazil compresses years of brand-building into one weekend. Chery-backed JETOUR is essentially buying distribution for its "Travel+" strategy at the cost of flights and a stadium rental. The endgame for this playbook is predictable. Brands that lock in owner communities early in Latin America will own the mid-range off-road segment there. Those still spending on billboard ads will be renting attention from someone else's crowd.
More

MKDWELL’s Gamble on Commercial VR Batteries

(SeaPRwire) - MKDWELL entered VR hardware through the back door. The Nasdaq-listed company built its reputation on automotive electronics and LiDAR sensors across Taiwan and mainland China. Now it wants you to believe its four-slot VR battery charger is the missing piece in commercial headset operations. The claims are specific enough to stress-test. A 120W power adapter charges four compatible batteries simultaneously. Lab data shows a 0% to 100% cycle in roughly two hours under specified conditions. Hot-swappable batteries let operators keep headsets running without shutdown. The company positions this for location-based entertainment, enterprise training, and medical education. Actual charging times depend on battery model and operating environment, the release carefully notes. Here is where the real pressure sits. Major VR headset makers guard their battery ecosystems fiercely. MKDWELL is not building headsets. It is building peripherals for other people's platforms. Securing orders from internationally recognized brands validates the concept. But those orders do not guarantee future orders, the company itself disclosed. This is component supplier logic, not brand loyalty logic. Buyers will switch providers the moment a cheaper alternative appears or a headset maker decides to manufacture internally. The commercial VR battery rotation market is real. Multi-device venues bleed revenue through charging downtime. MKDWELL has identified a legitimate pain point and delivered a workable product. The question is whether they control enough of the supply chain to matter. Removable batteries for flagship headsets require either OEM partnerships or third-party compatibility deals. Neither path provides lasting leverage. The margin advantage lives with headset manufacturers, not accessory makers. MKDWELL's diversification bet is sound. Its defensibility is not.
More

Video Is Easy. The Body Is Hard. Noitom Just Built the Bridge.

(SeaPRwire) - Egocentric video is everywhere. Learnable in-the-wild data is not. The industry obsesses over collecting viewpoints while ignoring the body behind the camera. Without body motion, video is just noise. Noitom Robotics introduced ITW-Ego Plus at CoRL 2026, aimed squarely at this blind spot. The product pairs egocentric video with full-body motion, captured by in-house Sol and Jupiter hardware. This is not another dataset. It is a statement about how data should be defined. Capturing video is the easy half. The body is the hard half. Official claim: ITW-Ego Plus is a new category of in-the-wild human data. It pairs egocentric video with full-body motion, wrist video, external views, touch, and sound. The Body modality runs on Sol and Jupiter. Jupiter is a few small wearables, no motion-capture suit required. Industry subtext: in-the-wild data must be learnable. Video is the easy half. Body is the hard half. Without whole-body motion, video cannot teach a robot how to stand, reach, or move through a task. Noitom CEO Dr. Tristan Ruoli Dai put it plainly: 'Scale gives you the first half; the second half is what makes scale learnable.' Competitors sell hours of video. Noitom sells motion context. Official facts: NEAR Lab, led by Dr. Han Lei, presented three main-track papers on Nov. 10 — HiPHI, OmniContact, and AdaPT. HiPHI is a 617.5-hour benchmark of whole-body motion and real-object interaction. OmniContact chains meta-skills via contact flow. AdaPT learns professional tennis styles from broadcast video. NEAR Lab also unveiled Unified Motion Retargeting (UMR), validated on five humanoids from 0.75 m to 1.83 m. HiPHI-Hand was released on Hugging Face under MORL v1.0. It contains 11 hours of egocentric video. Sub-millimeter 3D hand ground truth came from optical motion capture with micro-markers. NVIDIA used this capture for EgoHand. Industry subtext: Noitom is not a data dump. It is a closed loop. Capture plans what to record. Papers train on it. UMR carries motion to any robot. The 15,000 downloads of HiPHI show appetite. But the real signal is the pipeline from capture to deployment. The supply chain for physical AI is forming. It has three layers: capture hardware, data representation, and robot retargeting. Noitom Robotics calls its infrastructure the World Compiler, implemented as ModalityNet. This layer turns human interaction into machine-learnable representations. The hardware layer is commoditizing. Sol headsets and Jupiter wearables are not the moat. The moat is the retargeting capability. UMR learns dense surface correspondence between human and robot bodies. It translates any mesh-based motion to any humanoid. That closes the loop from capture to robot. Companies selling raw video will drown in commodity data. Companies with hardware plus retargeting will define the standard. Noitom just staked its claim at CoRL 2026. The winners will own retargeting, not video hours.
More
Medicine’s Blind Spot: The Study That Exposes the Dismissal Gap in Women’s Health Business

Medicine’s Blind Spot: The Study That Exposes the Dismissal Gap in Women’s Health

(SeaPRwire) - The new Clue study is a mirror held up to a medical culture that still treats menstrual pain as a footnote. Nearly half of the women who sought help walked away with their concerns waved off. That is not a patient satisfaction problem. It is a systemic failure in how the body is read and what gets prioritized. The data cuts clean. Of those who consulted a provider, one in three was told their symptoms were normal or not a problem. Fewer than a third received a diagnosis or treatment. Only 40 percent were satisfied with the encounter. A third said their provider did not know how to help them. This is not a case of difficult cases; it is a case of a medical culture that defaults to dismissal. The burden is not trivial. Nearly half of respondents reported severe symptoms. Forty-three percent said their symptoms substantially disrupted daily life. Yet 59 percent were managing alone, and only 9 percent felt their current strategies were working. The gap between symptom severity and clinical response is the real story here. Cycle tracking, as the study notes, helps people recognize patterns and speak more confidently with providers. That is a practical fix, not a wellness trend. The clinical takeaway is blunt. Without a systemic shift that treats the menstrual cycle as a vital sign rather than a nuisance, the dismissal will persist. The endometriosis case in the study is not an exception; it is the norm. The industry needs to stop normalizing pain and start integrating tracking data into care. Anything less will keep the cycle of silence running.
More
Tailg’s Milan Push: Why the 2,000-Patent Moat Matters More Than the Showroom Shine Business

Tailg’s Milan Push: Why the 2,000-Patent Moat Matters More Than the Showroom Shine

(SeaPRwire) - Tailg hit its fourth consecutive year at EICMA in Milan. The press release leans hard on the phrase “Together, Go Further.” It feels a bit hollow without hard metrics. They brought sixteen models to the floor. The real question is whether this is just a design showcase or a serious infrastructure play. Most Chinese two-wheeler brands treat EICMA as a brand-building exercise. Tailg seems to be treating it as a commercial gateway. The official facts are sparse but telling. They cite 2,000+ patents. The tech stack covers energy, power, intelligence, and charging. The T91 Ultra-L features a smart cockpit and fast charging. The F91 Ultra-L targets efficiency with mecha-style aesthetics. The TK76 is built for African commercial loads. These aren’t just consumer toys. The TK76 explicitly mentions delivery and goods collection in tough road conditions. That is a B2B play disguised as a consumer line. The subtext is global expansion. They have distribution in Belgium and Greece. They aim for the Middle East, Africa, North America, and Latin America. The partnership with the UNDP for “Green Ride Africa” is the key differentiator. It gives them a development corridor. This isn’t just selling bikes. It’s building a service network in emerging markets. The UNDP link provides legitimacy that generic imports lack. It positions Tailg as a mobility solution partner, not just a hardware vendor. The supply chain landscape is shifting. You can’t scale in Africa without local service networks. Tailg is betting on their patent base to keep hardware costs low. The fast-charging infrastructure will be the bottleneck. If they cannot source reliable charging components at scale, the “long-range” promise fails. The 2,000 patents are their insurance policy. They are moving from selling product to owning the standard. The endgame is lock-in through infrastructure dependency.
More

The Quiet Killer in AGV Battery Contracts: Why 30-Minute Charging Beats Raw Capacity

(SeaPRwire) - CBAK Energy just closed an $8.22 million order book. Do not read this as a victory lap. Read it as a signal fire. The client is not buying cells. They are buying uptime. This specific manufacturer of AGV packs has moved from evaluation in 2021 to full commercial supply by 2022. That is a four-year ramp. In the fast-moving robotics sector, retention like this is rare. It implies the spec sheet met the harsh reality of warehouse floors. The money is real. The pain point is time. The official release highlights two models: the 26650 PFS2 and the 32140 FS. These are full-tab LFP cells. The 26650 variant hits 3,000 cycles in testing. It offers high-rate charge and discharge. Its smaller footprint helps pack designers fit cells into tight spaces. This is a standard engineering trade-off. You accept a slightly lower energy density per cell to gain thermal stability and cycle life. For a robot that restarts every hour, this math works. The 32140 FS changes the game. It shows an internal resistance of 1.3 mΩ. That is 18% lower than comparable cells. More importantly, it supports 2C fast charging. Under test conditions, it reaches full charge in about 30 minutes. The release notes production hubs in Nanjing and Dalian. It also cites UL, UN 38.3, and RoHS compliance. These are not just checkboxes. They are the gatekeepers for Western logistics hubs. Passing them allows CBAK to sell into the global supply chain without regulatory friction. Here is the industry subtext. AGVs do not care about maximum range. They care about zero downtime. A battery that sits idle for two hours kills ROI. The 30-minute window allows a robot to recharge during a standard shift break. It replaces two robots with one. That is a capital expenditure saving for the end customer. CBAK is not selling energy storage. They are selling labor substitution. The technology is the enabler. The business model is efficiency. The supply chain landscape is shifting. Battery pack makers are no longer designing for peak power. They are designing for rapid replenishment. The full-tab design reduces heat during high-current operation. This allows smaller thermal management systems. That means lighter packs. That means more payload. The competitive edge in AGVs will not come from the motor or the AI. It will come from the seconds saved in the charger. CBAK’s data points to that efficiency gap. Expect other vendors to chase the 30-minute mark next.
More
The Bank in XTransfer’s Corner: Why BOCHK’s Bet Rewrites the SME Trade Playbook Business

The Bank in XTransfer’s Corner: Why BOCHK’s Bet Rewrites the SME Trade Playbook

(SeaPRwire) - Anyone who has run a mid-sized export shop knows the pain. The letter of credit sits in limbo. The remittance gets stuck in a correspondent bank. Compliance flags the invoice because the buyer’s name has a typo. Trade finance was built for conglomerates, not for the dusty factory floor. So when XTransfer signs a real cooperation pact with Bank of China (Hong Kong) at Hong Kong FinTech Week, the industry should stop and read the fine print. This is not a photo-op handshake. It is a structural shift in how SMEs access global money movement. The old architecture just got bypassed. The official line is clean. Martin Liu, VP of XTransfer, and Winnie Fan, Deputy General Manager of the Global Corporate Banking Department at BOCHK, signed the agreement. Bill Deng, XTransfer’s founder and CEO, and Liu Chao, General Manager at BOCHK, stood as witnesses. The scope covers global collections, payments, and foreign exchange. BOCHK brings its cross-border settlement muscle and its status as the RMB clearing bank in Hong Kong. XTransfer brings a self-built B2B settlement network and a risk-control engine. Under this model, XTransfer is BOCHK’s first corporate partner. That phrase matters. It is not “one of many.” It is the first. Now strip the PR wrapper. The real commercial intent is distribution. BOCHK has the treasury product, but it lacks a direct on-ramp to the long tail of trade clients. XTransfer sits on a network of over one million business customers. Those customers need multi-currency accounts, fast FX quotes, and compliant collection rails. They do not get that from a traditional branch relationship. So the bank becomes a “co-builder,” providing the licensed backbone. XTransfer becomes the front door, feeding the bank a pipeline of screened, vetted trade flows. It is a classic platform-plus-bank arrangement, but the direction is rare. Usually banks force startups into a vendor role. Here, the bank is the utility behind the platform’s brand. Deng’s quote is telling. He says SMEs can now enjoy cross-border financial services at the same standard as large multinationals. That is a direct attack on the rent-seeking layers that plague trade settlement. If this model scales, the handover points in cross-border transactions shrink. Margin pressure hits correspondent banks. Small trade banks that lack a strong SME platform will lose their best clients to the faster, cheaper pipe. The market share reshuffle will not be driven by interest rates or product features. It will be driven by who owns the customer's settlement feel. This partnership may be the template that puts traditional trade finance on notice.
More
Micware Moves Its HQ: A Tale of Twofold Space and Software-Defined Ambitions in Columbus Business

Micware Moves Its HQ: A Tale of Twofold Space and Software-Defined Ambitions in Columbus

(SeaPRwire) - Dublin, Ohio isn’t a tech hub. It’s a suburb. Yet Micware just doubled its footprint there. The company moved from its previous space to 5525 Parkcenter Circle, Suite 100S. This expansion looks odd for a firm selling infotainment code to Honda and Toyota. Why lease more desks in a quiet Ohio suburb? The answer lies in their software-defined vehicle (SDV) push. They aren't just selling maps anymore. They are selling spatial intelligence. The office size is a signal. It says "we are staying," not "we are pivoting." The facts are stark. Micware North America, Inc. relocated on October 30, 2026. The event drew local officials, including Mayor Chris Amorose Groomes and Rep. Mike Carey. They also handed out Patriot Awards to three employees for supporting a U.S. Army Reserve member. The tech showcase included micAuto-PF, Mvcube, and DynaPlanet-PF. These tools handle in-vehicle infotainment, road analysis, and 3D digital twins. The core business remains automotive software. But the "spatial intelligence" branding is new. It hints at a shift from car-specific code to broader data platforms. CEO Kenji Narushima called this move "the next chapter." He wants to introduce more platforms to the U.S. market. The company has been in the U.S. since 2014. This expansion signifies confidence. It also suggests a strategy to decouple from pure hardware sales. By building a dedicated U.S. base, they aim to sell services, not just products. The focus on AI-powered testing tools reinforces this. They want to be the backend for smart vehicles, not just the screen. The industry is tightening. Automakers need cost-effective software partners. Micware’s move positions them as a resilient backend provider. They aren't chasing hardware margins. They are targeting the software layer where margins expand. The Dublin office serves as a anchor for this transition. Watch their quarterly reports. Look for revenue shifts from licenses to services. That is where the real growth story hides. If they keep the software stickiness high, the Ohio expansion pays off. If not, it’s just a bigger office. The bet is on software stickiness.
More
Chery’s MOBO Robot Is a Clever Supply Chain Play, But Can It Survive the Living Room? Business

Chery’s MOBO Robot Is a Clever Supply Chain Play, But Can It Survive the Living Room?

(SeaPRwire) - The consumer home robotics market is a graveyard of failed startups. Chery is making a massive bet on its manufacturing muscle. It hopes to clean up the graveyard. Launching MOBO as a home companion robot sounds great on paper. But the reality of a robot navigating a chaotic living room is a world away from a car on a mapped highway. Chery claims MOBO can handle complex tasks, but hardware durability in real homes is brutal. Tying this robot to a car brand like LUXEED is a risky consumer play. On October 21, 2026, AiMOGA opened global pre-orders for MOBO in Wuhu. The robot targets elder care, child companionship, and daily family support. It uses MoAgent software to handle perception, motion, and memory. AiMOGA's product line holds EU CE and US FCC certifications. This launch looks like a standard consumer electronics rollout. But the real story is Chery's hardware manufacturing muscle. They want to use their automotive supply chain to mass-produce robot bodies. This could slash costs compared to niche robotics labs. Certifications are necessary, but they do not guarantee daily durability. Internal motors still need to survive real-world household accidents. LUXEED stands to gain from Chery's shared AI foundation. Both brands use environmental perception, motion control, and large-scale hardware manufacturing. CheryMind, the automotive foundation model, powers both LUXEED cars and AiMOGA robots. LUXEED's brand proposition, "I" DRIVE, YOU ENJOY, highlights this division of labor. Sharing the CheryMind model is a clever way to spread massive R&D costs. It lets Chery build a unified AI architecture. But the consumer value of a car talking to your living room robot remains unproven. Most users will see the link as a novelty unless the software works flawlessly across different hardware. The global hardware supply chain is highly concentrated in China. Chery's vertical integration gives them an unmatched cost advantage in sensors and motors. But software-defined hardware is only as good as the chips inside those devices. Scaling MOBO and LUXEED globally will be tough. They will face the same geopolitical bottlenecks as other giants. Component sourcing battles are inevitable. The winner in this space won't be the one with the smartest chatbot. It will be the one with the most resilient, localized hardware logistics.
More
Why 700 Distributors Drove Trucks in South Africa: The Real Stake in BAIC FOTON’s African Push Business

Why 700 Distributors Drove Trucks in South Africa: The Real Stake in BAIC FOTON’s African Push

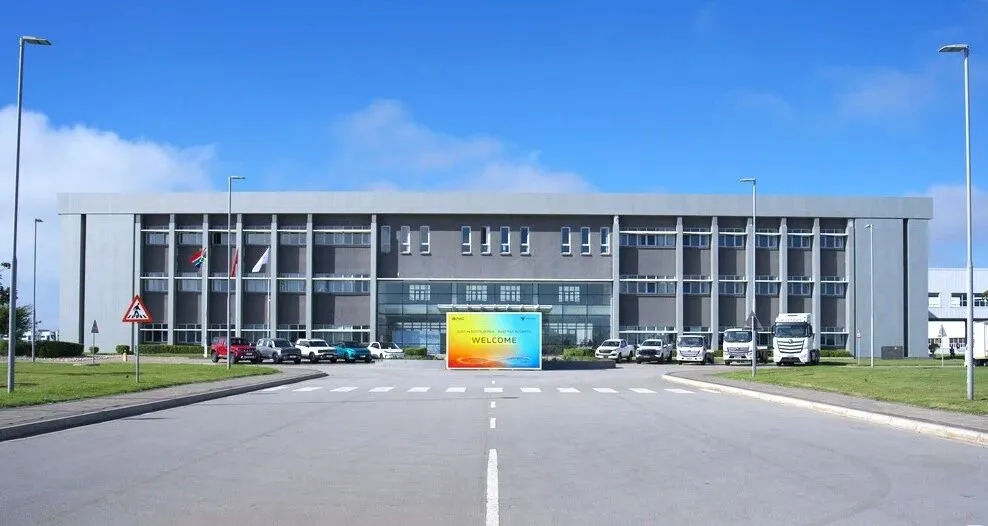
(SeaPRwire) - The gap between exporting steel wheels and building a continent’s infrastructure is brutal. You do not gain loyalty by shipping from distant ports. You gain it when your factory floor sits inside their economic zone. On October 29, in Port Elizabeth, South Africa, BAIC FOTON stopped selling a brand story. They started proving a supply chain reality. Nearly 700 partners from 42 African countries walked through the Coega Development Zone plant. This was not a showroom event. It was a stress test of trust for a market that is tired of broken promises and distant support. The official narrative calls this the “Drive to Great” conference. The subtext is colder. BAIC moved FOTON trucks to SKD production in January 2025. Heavy-duty AUMAN tractors entered trial assembly in March. Mass production for trucks started in August. Pickup CKD trials began in September. This timeline matters. It proves the transition from finished vehicle exports to localized assembly is not a slogan. It is a staged industrial rollout. The plant now handles welding, painting, and assembly. This reduces tariff friction and logistics delays that have long plagued imported commercial vehicles on the continent. The marketing sheet highlights 360-degree spins and drifting by two TUNLAND G7 pickups. Ignore the stunts. Focus on the commercial loop. The diverse lineup includes heavy trucks, light trucks, pickups, and vans. These are not lifestyle choices. They are tools for long-haul logistics and urban-rural distribution in harsh conditions. When 700 distributors see mass production capability locally, the value proposition shifts. It is no longer about importing a product. It is about accessing a regional hub that adapts to local road infrastructure. The confidence these customers feel now is anchored in the physical presence of the factory, not in a brochure. Supply chains in emerging markets die when the repair and parts ecosystem is foreign. By locking in production in South Africa, BAIC FOTON is betting that local manufacturing lowers the total cost of ownership for African operators. The market share will not shift because of better paint. It will shift because trucks break less, or get fixed faster, when the maker is neighbors. This is the hard truth of industrial expansion. Presence beats performance metrics every time.
More