The Machine That Doesn’t Sleep: Why Real Orders Beat Simulated Training

(SeaPRwire) - Most vocational programs in the West are dead on arrival. They teach simulation. Students press buttons on screens that mimic metal cutting, but no metal is ever cut. No part is ever good or bad. There is no consequence. This is the critical failure that separates modern industrial training from the brutal reality of the shop floor. When journalists from the Caribbean visited JIER Machine-Tool Group in Jinan, they saw something rare. They saw young trainees operating CNC gantry boring and milling machines. These were not display models. These were active production lines. The students were machining parts for real customer orders. This distinction changes everything. It moves training from a theoretical classroom to a live operational risk environment. The official narrative is straightforward. JIER was founded in 1937. It has grown into a major manufacturer of large-scale CNC stamping equipment. Its machines help build cars for General Motors, Ford, and Volkswagen. The company exports to 67 countries and regions. A media tour organized by the Jinan municipal government showcased this legacy. The focal point was the Intelligent Manufacturing Precision Machining Training Center. Here, smart production lines run alongside trainees. The core fact is simple: the training is attached to a production line with real orders. New workers practice on parts bound for real customers. They do not simulate. They produce. This is not a gimmick. It is a fundamental shift in human capital development. The subtext here is about supply chain resilience and demand stability. Why can JIER tie training to real orders? Because the enterprise has a steady flow of demand. A company that cannot sustain production volume cannot sustain meaningful apprenticeship. The machines that build cars for global giants like VW and GM represent a robust order book. This stability allows the firm to integrate education into its core operations. The trainees become junior operators immediately. They learn the rhythm of industrial output. They understand the weight of a deadline. They see the immediate link between their skill and the company’s revenue. This creates a workforce that is ready for the shop floor, not just the exam room. The "official" fact of a training center is actually the "true" fact of a self-sustaining industrial engine. This reshuffles the market share of industrial talent globally. Simulation-based training produces graduates who know theory but lack grit. Real-order training produces technicians who know flow, failure, and fix. The gap will widen. Companies that rely on classroom-only models will struggle to hire competent operators. They will have to retrain them. JIER’s model bypasses this cost. It embeds cost directly into the value chain. The lesson is not about tourism or government relations. It is about where the training sits. If it sits next to the revenue stream, it works. If it sits in a separate building with static software, it fails. The industry does not need more certificates. It needs more hands on the wheel.
More

The Real Battle for Yellow River Land Isn’t Solar Panels — It’s Who Owns the Pond

(SeaPRwire) - Jinan wanted to show the world something fresh. A decade ago, the pitch for rural solar was simple. Clear land, bolt down modules, sell power to the grid. Now those same municipalities face a wall. Farmland protections, fragmented land tenure, and grid capacity limits have all tightened. What looks like a clean energy story in the press release is really an institutional negotiation that most regions would fail to replicate. The Jinan Information Office invited international journalists to Wujiapu subdistrict this October. They saw rows of photovoltaic panels floating above water where fishermen were hauling up Yellow River hairy crabs. The project covers more than 1,500 mu across three villages. Shading stays below forty percent. The array powers around 40,000 households annually. Carbon emissions drop compared with conventional coal-fired generation. Aquaculture adds income. Village collectives receive annual rent. Residents work locally. On paper this checks every box for a green transition narrative. What the release does not advertise is the harder substrate beneath the panels. Replication depends on three invisible conditions that most provinces cannot simply purchase. First, existing ponds suitable for conversion. These were once idle assets clustered across three villages. Not every region has that stock of underutilized water surface sitting adjacent to distribution infrastructure. Second, land rent arrangements that flow revenue to village collectives. Property rights over rural water surfaces in China remain layered and contested. The Wujiapu model works because someone already resolved who gets paid and how. Third, grid access. The solar output must reach transmission lines without building new corridors. In regions where grid heads are full, even a perfect fishery-PV project sits behind a curtailment wall. The Wujiapu case is not a template. It is a case study. Each province must weigh its own pond conditions, its own collective governance structures, and its own grid bottlenecks against the same ambition. The visible technology is easy to copy. The institutional architecture is not. Until policy frameworks clarify water-surface rights and align them with renewable investment incentives, fishery-PV will remain a showcase model in select Yellow River counties rather than a scalable pathway. The next phase of China's rural energy rollout will be decided not by panel efficiency curves, but by who holds the deed to the water beneath them.
More

Fuzhou’s Blue Economy Gambit: How One City Turned Nearshore Waters Into a $10 Billion Exportable Model

(SeaPRwire) - The real story behind Fuzhou's latest display of maritime muscle isn't the conference backdrop or the press conference choreography. It's what happened in the three decades before it. Fuzhou became the first Chinese city to embed "advance toward the sea" into its master development blueprint over thirty years ago. That was when most coastal cities were still debating whether marine economics warranted a dedicated administrative line item. The institutional scaffolding matters more than the headline numbers. Fuzhou reformed sea-area-use approval procedures and pioneered property-rights registration for deep-sea aquaculture platforms. Both sound like bureaucratic housekeeping until you realize what they unlocked. Large-scale offshore aquaculture equipment had been stuck in a financing dead loop — high construction costs, unclear title, no collateral. By solving the property-rights question, Fuzhou created the precondition for private capital to enter a sector that previously required state balance-sheet backing. The financial-policy layer followed naturally. The technology stack that grew out of those reforms is where the actual competitive moat sits. Fuzhou built a land-sea integrated ocean sensing network. Ocean buoys, tide gauge stations, 5G links, satellite communications, and AI recognition systems now feed a single monitoring platform. Submersible platforms and net-cleaning robots handle the biofouling problem that has plagued offshore operators for decades. The output is measurable. Labour costs for large-scale fishery operations drop. Typhoon early-warning response times tighten. The city controls the data layer between the fish and the market. The international dimension is the part most observers glaze over. The Mauritania base — Fuzhou Hong Dong Fishery's USD 300 million investment creating over 2,000 local jobs — is not simply a distant-water fishing station. It is a processing and logistics node anchored to Fuzhou's supply chain. The China-Indonesia "Two Countries, Twin Parks" project adds another layer. Sixty-one square kilometers, more than 250 operational enterprises, connecting marine fisheries, food processing, and cross-border supply chains. Both projects operate under the Belt and Road Initiative framework but function as independent revenue streams insulated from domestic regulatory drift. What makes Fuzhou's model transferable is the standardization step. The city took its deep-sea aquaculture "experimental field" and converted it into a "standardized model" — meaning the hardware specs, the property-rights templates, the financing structures, and the monitoring protocols can now be packaged and exported. The 2025 fishery output value exceeding RMB 70 billion and the 31-year national ranking are the lagging indicators. The leading indicator is the replicability of the Fuzhou framework in other coastal jurisdictions. The end-game for Fuzhou isn't dominating China's fishery output. It is becoming the default blueprint for maritime-economy zones across the Global South. Any port city seeking to professionalize offshore aquaculture will face the same three bottlenecks Fuzhou solved: property rights, sensing infrastructure, and international market access. The question is whether other cities will build their own stacks or adopt the Fuzhou template wholesale.
More

EBC Put the Entire Trading Stack in One App. The Lock-In Play No One Advertised

(SeaPRwire) - Every retail trading platform knows where customers bleed out. Not at the chart. Not at the liquidity feed. Between the funding confirmation and the first trade button. That gap has been the silent killer of conversion in fintech for years. EBC Financial Group tried to kill that gap. The full trading lifecycle now lives in one mobile app. Whether solving the friction problem was the problem that needed solving is the real question. The fintech world has been chasing convenience like it is a growth lever. It is. But convenience is also a Trojan horse. Once you solve the surface friction, you bury the structural question underneath. The timeline is specific and the scope is broad. EBC announced its app on July 7, 2026, as an account management tool. Clients could open accounts, verify identity, handle deposits and withdrawals, and reach multilingual support around the clock. Live trading entered that same app on September 14, 2026. The feature expanded to additional markets on October 21, 2026. Clients can now view real-time quotes and trade CFDs across more than 300 forex pairs. Commodities, indices, stocks, and exchange-traded funds are also available. Market orders fill at the current price. Pending orders execute only when price hits a chosen level. Traders can set take-profit and stop-loss levels to close positions automatically. The order tools are designed to give traders clearer control over their exposure. They do not remove the risk. That distinction is deliberate. EBC wants the trader to feel in control without feeling the platform hides anything. EBC's Smart Order Routing Engine drives the execution layer. More than 87.6% of orders fill at a better price than the one quoted at placement. Average execution speed sits at 20 milliseconds. The system processes 1,000 orders per second with 98.75% stability. Tier 4 private leased-line servers run across five global financial hubs. Thirty data centres worldwide support the operation. Pricing draws from more than 50 liquidity providers. J.P. Morgan, UBS, Barclays, and Goldman Sachs are among them. Raw ECN spreads start at 0.0 pips. Five levels of market depth are visible to the trader. EBC operates under FCA, ASIC, CIMA, and FSCA regulation. It claims over 8 million registered users across more than 100 countries. The app runs on iOS and Android. EBC also claims the title of World Finance's Best Global Broker for four consecutive years. That institutional credibility is not accidental. It was built on the premise that infrastructure quality is the differentiator. Now the infrastructure lives inside a phone. Access is subject to each client's location and the specific EBC entity providing the service. Andria Phiniefs, Marketing Director at EBC, frames the move as helping clients trade better anywhere. That is the polite version. The commercial reality is more aggressive. When a trader opens, funds, monitors, and trades inside one app, the platform becomes a single point of relationship. The switching cost rises sharply. A trader no longer compares one broker's execution against another's. They compare leaving an entire stack versus staying put. EBC has converted what was a utility layer into a retention barrier. The 87.6% better-fill claim amplifies the lock-in. It gives the trader a quantifiable reason to trust their orders are handled better elsewhere. The infrastructure specs reinforce that trust. Sub-20ms latency and Tier 4 servers are not cosmetic details. They are signals that the broker invested in keeping prices sharp. The risk language in the release is blunt. CFDs trade on margin. Leverage magnifies gains and losses alike. Losses can exceed deposits. Stop-loss orders do not guarantee execution at a set price. Fast-moving markets can gap prices past that level. EBC states all of this clearly. But stating risk plainly does nothing to counter the pull of convenience. A trader who never switched apps to place a trade will never build the habit of comparing execution quality. This is where the end-game appears. EBC is not selling a better chart. It is building architecture where the broker becomes the default relationship between trader and market. Once that relationship locks in, the competitive fight shifts from features to trust. Trust anchored to infrastructure is extraordinarily hard to dislodge. Regulators will watch this consolidation closely. The more functions collapse into one app, the more exposure concentrates in a single entity. The four-jurisdiction regulatory framework EBC operates under is not just a badge. It is a survival requirement in a market where trust is the new product. Every broker that has invested in raw execution quality now faces the same pressure. Consolidate or get consolidated. The traders will not wait for you to catch up.
More

Shanghai’s Housing Conference Faces the Land Price Elephant in the Room

(SeaPRwire) - The SDG Cities Global Conference 2026 lands in Shanghai on 2 November with a theme that intimidates. “Regenerating the City: Adequate Housing for All” is not an agenda item. It is a land price confession. Co-hosted by the Shanghai Municipal People’s Government and UN-Habitat, this flagship event of World Cities Day first launched in 2021. It brings global mayors, planners and financiers to the Grand Halls. Yet such gatherings rise or fall on one awkward question. Can urban regeneration deliver enough affordable homes, fast enough, without turning old neighborhoods into investment products? Sophisticated programming can obscure that question. A cool-headed verdict says it will not. Press materials describe a thick apparatus. A plenary sits above the SDG Cities International Symposium. Five themed sessions, seven special sessions and six side-event series fill the programme. The Shanghai International City and Architecture Expo runs in parallel. On-site urban study tours are included. Shanghai says it is deepening cooperation with UN-Habitat. It promises to refine topics and event formats. The goal is to let global cities share experience and cooperate. The tangible outputs are called international public goods. These include the Shanghai Manual and the UMF-Shanghai Adapted Index. The scheduled application report for 2026, titled Various Scenarios & Proposed Solutions in Global Cities, joins the list. Crowds attend to find flexible toolkits. The real test is compliance cost. A medium-sized city that adopts a global index reorders its statistics office. It hires new technical skills. Budget politics follow every data feed. That is where warm talk dies. The official releases include the Chinese edition of the Shanghai Manual 2026 Annual Report. They also include the UMF-Shanghai Adapted Index Application Report 2026. Its subtitle is Various Scenarios & Proposed Solutions in Global Cities. Thematic scenario reports will be published too. Announcements are safe. They focus on shared outputs, not the gritty controls that shape housing affordability. Look at the true social impact. Adequate housing means rent data, vacancy data, demolition replacement timelines and infrastructure repair backlogs. A roadshow format or a media briefing can present a model block. It cannot replace the slow process of changing zoning and procurement rules. Shanghai knows this. Many other signatories to UN-Habitat statements know it too. The gap between ceremonial release and municipal practice remains the widest governance gap we have. For every elegant index, thousands of street-level decisions remain. Who may build? What must be preserved? Which families move back? The governance structure that matters is not announced in the symposium catalogue. It lives inside land conveyance contracts, rent control statutes and fiscal transfer formulas. This conference can push those boundaries if it ties each benchmark to a binding local audit. Otherwise, it becomes global elite theatre, repeating the same urban vocabulary every year. The city that wins is not the one with the brightest expo booth. It is the one that can prove, in hard local numbers, that adequate housing costs ordinary residents less. Watch the follow-up reports after November. If they count units and rents, the governance logic is real. If they count only events and workshops, treat the conference like any other city ritual. Attend the session, read the manual, then ask who actually benefits.
More
Fixing the FDM Moisture Nightmare: Why eSUN’s Four-Spool eBOX Plus Is a Workflow Reality Check Business

Fixing the FDM Moisture Nightmare: Why eSUN’s Four-Spool eBOX Plus Is a Workflow Reality Check

(SeaPRwire) - Most 3D printing hobbyists and small-shop operators treat filament drying like an afterthought until a print fails midway through a twenty-hour job. Stringing, surface bubbling, and brittle extrusion are usually blamed on bad slicer settings or nozzle clogs, while the real culprit is ambient humidity quietly ruining the polymer spool sitting out on the rack. The recently announced eSUN eBOX Plus aims straight at this persistent workshop headache by scaling up capacity and automating active dehumidification for everyday FDM workflows.Looking closer at the hardware specs released by Wuhan-based eSUN on October 23, 2026, the device introduces some practical engineering choices tailored for multi-material users. Traditional single-spool dryers force a frustrating bottleneck when juggling different colors or engineering polymers. The eBOX Plus addresses this by expanding its internal chamber to accommodate up to four spools of the same filament type simultaneously, cutting down on repetitive drying cycles. Heating capabilities reach a maximum of 80°C, which covers standard workshop materials like PLA, PETG, ABS, and TPU, provided operators dial in the correct thermal profiles for each specific polymer.Beneath the hood, the system moves past passive desiccant storage by deploying dual PTC heating elements paired with dual fans. This setup drives a 360-degree airflow pattern to keep the thermal environment uniform. More importantly, an intelligent active dehumidification system continuously monitors internal chamber humidity and purges the moisture rather than letting it linger inside the enclosure. For those who prefer backup options, an independent, removable desiccant box is included. The integrated dry-while-printing function also lets users feed filament directly from the warm chamber to compatible 3D printers, which minimizes ambient exposure during extended jobs. Master Mode rounds out the software side by offering preset parameters for common filaments, skipping manual configuration for straightforward print jobs.Ultimately, hardware like this reflects a quiet maturation in desktop fabrication where material handling matters just as much as extruder mechanics. As long as hygroscopic polymers remain a staple of daily production, standalone dryers will evolve from optional accessories into mandatory infrastructure for reliable builds.
More

$5M in Storage Modules and a Finland Data Center: How a Nasdaq Microcap Is Funding Its AI Ambition From Its Own Balance Sheet

(SeaPRwire) - A $5 million storage hardware order sounds trivial when the hyperscalers are signing eight-figure contracts with Samsung and SK Hynix every quarter. But look at who is moving this metal and you understand why it matters. 3 E Network Technology Group, Nasdaq ticker MASK, just started shipping enterprise-grade high-density memory modules and data center-grade storage controllers through its Hong Kong subsidiary. The amount is pocket change in the grand scheme of global semiconductor revenue. Yet the structure of how this deal flows through the company's operations reveals something more telling about where the AI infrastructure money chain is actually stretching and where it is snapping. Small-cap hardware integrators in Hong Kong are now running pre-shipment verification routines on the same tier of equipment that would normally sit in a Dell or Super Micro staging facility in Taiwan. The capital is thin. The margin is razor. And the bet is that a company can sell enough commodity-adjacent storage hardware to keep its lights on while it builds something proprietary in Finland. The contract itself is straightforward on paper. Approximately $5.0 million in core storage hardware, shipped in phases over coming quarters. The first batch has already been dispatched. What is not trivial is what 3 E Network is doing in the space between signing and delivery. Before any of that hardware left the staging area, their technical team ran system-level compatibility and interoperability verification on the storage equipment. This is not a standard commodity reseller move. Enterprise clients integrating independent hardware into existing data center architectures face real integration risk. A misconfigured storage controller or an incompatible memory module can stall a production environment for days. By absorbing that verification step before shipment, 3 E Network is not just shipping boxes. They are selling a risk-mitigation wrapper around otherwise standard enterprise hardware. The company's management, led by CEO Dr. Tingjun Yang, framed this dispatch as a milestone transitioning from signed agreement to tangible fulfillment. That is accurate. But the deeper signal is operational. They demonstrated cross-border order fulfillment capability and large-scale hardware procurement coordination at a moment when supply chain fragmentation has made even small-batch enterprise hardware logistics complicated. The phased delivery model means revenue is recognized progressively as fulfillment milestones are hit, with corresponding customer payments flowing into operating cash. This is where the real story sits. 3 E Network is not sitting on that cash. The non-dilutive operating cash flow from this contract is being directly allocated to two capital-intensive projects. One is the Mikkeli 9 MVA AI compute center in Finland, currently in the hardware RFP evaluation phase. Two megawatts of power infrastructure in a Northern European data center market is not a hobby project. The other is microarchitecture R&D for a next-generation proprietary AI Storage Controller. This is a company using its core enterprise IT solutions business to fund its advanced infrastructure initiatives without diluting existing shareholders through equity raises. That is a specific strategy. It is not the strategy of the GPU startups burning venture cash at a hundred million dollars per quarter. It is the strategy of a lean hardware integrator trying to build a defensible position in AI compute infrastructure by bootstrapping from operating cash flow. The company describes its business as comprising two main portfolios: data center operation services and software development. The hardware sales are effectively the cash engine funding the compute and chip ambitions. If the Mikkeli facility comes online and the proprietary storage controller enters development traction, 3 E Network has a vertical stack that does not exist in commodity hardware distribution. If either project stalls, the $5 million in storage shipments becomes exactly what it looks like from the outside: small-margin enterprise hardware reselling with modest upside. The market will have to decide which narrative to price in. Until then, the company's ability to convert this order into recognized revenue and deploy that cash into its Finland and microarchitecture projects without external financing is the single metric that separates the story from noise.
More
Twelve Partnerships, Zero Faster Approvals: Why Digital Patient Twins Can’t Outpace the FDA Business

Twelve Partnerships, Zero Faster Approvals: Why Digital Patient Twins Can’t Outpace the FDA

(SeaPRwire) - Every major pharmaceutical company has a tech partnership press release waiting in its backlog. Boehringer Ingelheim and Microsoft just released theirs. The announcement covers Digital Patient Twins, synthetic control arms, disease-progression modeling, and workforce-wide AI transformation. The headline promises faster access to safe and effective therapies. The subheading promises patient-centric, AI-backed clinical development. What it does not mention is the fact that this is another in a long string of such partnership announcements in the last eighteen months. The pattern is always the same. Two large companies meet in Germany or Boston. They sign a strategic collaboration. They issue a joint statement about bringing therapies to patients sooner. Eighteen months later, no drug has been approved faster because of it. The infrastructure gets built. The models get trained. The press releases keep coming. The regulatory pathway does not change. Investors love the partnership narrative. Analysts love the digital transformation story. Patients, who are the stated beneficiaries of every one of these collaborations, remain patient. Because they are still waiting. The official announcement describes an ambitious scope. Boehringer Ingelheim has stated a clear ambition to become a Frontier AI company across both human pharmaceuticals and animal health. The company has already deployed one of the largest Microsoft Copilot implementations in the pharmaceutical sector. The partnership covers security and datacenter modernization, supporting a secure, resilient, and future-ready technology foundation. They are exploring co-development projects in animal health, business processes, and technology infrastructure. Microsoft Germany employs over 3,000 people across seven locations: Berlin, Frankfurt, Hamburg, Cologne, Munich, Stuttgart, and Waldf. Boehringer Ingelheim has approximately 54,300 employees serving over 130 markets. The company has been independent since 1885. The commitment to employee enablement is explicit, with role-based use cases, skills development, governance, and secure technology foundations. The infrastructure investment is real. The workforce training budget is real. But the industry subtext cuts through the announcement language quickly. Deploying Microsoft Copilot across a workforce does not change regulatory timelines. Building datacenters does not change the FDA's evidentiary standards. Expanding into animal health and business processes does not accelerate human drug approvals. These are operational investments, not clinical breakthroughs. The security and datacenter modernization piece is not trivial either. AI models that process patient data need robust, compliant infrastructure. Building that foundation is necessary work. But it is also work that every major pharmaceutical company is doing independently or with its cloud partner of choice. This is table-stakes infrastructure, not a competitive differentiator. The first half of the partnership is solid. It is also largely irrelevant to the question of whether patients get medicines faster. The clinical development goals are where the tension lives. The official facts describe a joint research program exploring disease-progression modeling, predictive outcome modeling, and advanced trial simulation. The starting point is lung health, with plans to extend across multiple disease and therapeutic areas. Digital Patient Twins are computational representations of individual patients that use clinical and other relevant data to predict disease progression and treatment outcomes. The partnership will assess scientific and technical feasibility through modeling, prototyping, and evidence generation. The stated goals include reducing the number of patients required in control groups. They want to accelerate the generation of clinical evidence. They want to improve clinical trial design. They are exploring whether these approaches could support synthetic or hybrid control arms. Synthetic control arms use existing real-world data. Hybrid control arms combine real-world data with a traditional control group. These are all legitimate and important research directions. But the subtext is where the partnership meets its ceiling. The FDA has issued guidance on using external data in clinical trials. The EMA has published its own position papers. Neither agency has formally accepted synthetic control arms as a primary comparator for new therapeutic approvals in major therapeutic areas. The FDA guidance allows for use in certain circumstances, particularly rare diseases where recruitment is difficult. For common therapeutic areas, regulators still insist on placebo-controlled or active-comparator designs. The disease-progression modeling angle is particularly nuanced. Predicting how a disease like COPD or emphysema progresses in an individual patient is a hard problem. Even good models have uncertainty bands. And regulatory agencies are not comfortable with evidence generated from models with meaningful uncertainty. The hybrid control arm approach is more conservative by design. It still requires some traditional patient enrollment in the control group. That reduces but does not eliminate the regulatory friction. A company can build the most sophisticated Digital Patient Twin in the world. If the FDA or EMA does not accept the output as evidence for regulatory approval, the tool remains a research artifact. The bottleneck is not computing infrastructure. The bottleneck is not model accuracy. The bottleneck is institutional regulatory conservatism. No partnership between a pharmaceutical company and a cloud provider changes that assessment. The drug development supply chain has not changed structurally in a decade. Trials still take seven to ten years. Still require thousands of enrolled patients. Still face regulatory review timelines that vary by jurisdiction but rarely move faster. The partnership between Boehringer Ingelheim and Microsoft is not a failure. It is simply one node in a pipeline that is constrained by regulatory gatekeeping. The tools they build might inform trial design. They might improve predictive modeling. They might contribute to evidence generation in specific scenarios. But they will not collapse the approval timeline unless regulators change course. The pharma-AI partnership market has become a signaling mechanism. Companies announce alliances to signal to investors and analysts that they are investing in digital transformation. That signaling has value in the short term. It has almost no value in the long term unless the underlying regulatory environment shifts. The drug development pipeline is not just a technology problem. It is a regulatory problem. And regulators do not move at the speed of cloud partnerships. They move at the speed of peer-reviewed evidence, stakeholder consultations, and multi-year guidance updates. That is the supply chain reality that no press release can change. The industry needs to face this directly. Every pharma-to-cloud partnership announcement creates the expectation that technology will solve what is ultimately a policy problem. It will not. The next time a pharmaceutical company partners with a hyperscaler to accelerate drug development, ask one question. Has the FDA or EMA updated their guidance on computational control arms since the last announcement? The answer will be no. Until that answer changes, the partnership announcements are infrastructure spending ahead of regulatory policy. The patients who need faster drug access will keep waiting.
More

Silk, Souvenirs, and Soft Power: Why Jiangsu’s Budapest Showcase Is Really an Inbound Tourism Sales Pitch

(SeaPRwire) - Strip away the ceremonial robes and the poetic talk of "woven clouds," and what happened in Budapest last week was a trade mission wearing a costume. The "Charm of Jiangsu" Chinese Weaving and Embroidery Art Exhibition, staged jointly by the China Cultural Center Budapest and the "Charm of Jiangsu" Global Communication Center, looked like a museum show. It functioned like a funnel. I've sat through enough of these culture-first promotions, from trade fairs in Frankfurt to food weeks in Dubai, to recognize the architecture. You lead with heritage because heritage disarms. Nobody feels sold to when they're admiring a Ming dynasty ceremonial robe. But make no mistake, the object of the exercise is not embroidery. It's airfare, hotel nights, and foreign currency flowing into one Chinese province. Read the official facts first, because they are telling in their arrangement. The exhibition itself was built in three thematic sections, covering the history, craftsmanship, and continued innovation of Jiangsu's textile arts. On display were Ming dynasty ceremonial robes, reproductions of nankeen, and decorative pieces made with Nanjing Yunjin brocade. A representative inheritor of Nanjing Yunjin brocade weaving techniques delivered a lecture under the China Cultural Center's seventh "China Stories" session, titled "Nanjing Yunjin Brocade: Woven Clouds of the Jiangnan Water Towns," walking Hungarian attendees through Jiangnan silk history and the old story of nankeen exports to Europe. All legitimate, all well-curated. Now look at what was bolted onto it. A "Charm of Jiangsu" cultural and touristic conference. A "Hello, China" segment called "Chinese Cities I Have Visited," where two Hungarian guests recounted studying in Nanjing, visiting historic sites, and eating local specialties. Then the reveal: representatives of four travel agencies and airlines presenting travel products, themed itineraries, and China-Hungary flight information. That is not an exhibition add-on. That is a point of sale. The commercial intention becomes fully explicit in the closing moves. Jiangsu has introduced ten practical measures aimed at boosting inbound tourism spending and launched a "Next Stop: Jiangsu" visitor attraction initiative, with stated ambitions to expand in European markets including Hungary. This is the part the brocade is carrying. China has been pushing hard to convert post-pandemic visa easing and restored flight capacity into actual visitor volume, and provincial governments are now competing for their slice of that flow. Jiangsu's problem is awareness, not product. European travelers know Beijing, Shanghai, maybe Xi'an. Nanjing and the Jiangnan water towns sit one notch below in the mental map. So you don't advertise Jiangsu. You demonstrate it, through silk that once genuinely did travel this exact road westward to Europe centuries ago. The nankeen export story isn't nostalgia. It's a market-reentry argument dressed as history. Here's my read, plainly. This model works only if the conversion machinery behind the charm offensive is real, meaning actual airlift, bookable itineraries, and payment rails that don't frustrate a Hungarian tourist at the checkout. Four agencies and airlines showing up suggests the plumbing exists at least in outline. What I'd watch is whether Budapest becomes a recurring node rather than a one-off photo opportunity. Culture opens the door, but whoever turns museum visitors into boarding passes within twelve months wins this corridor, and right now every Chinese province with a heritage story is racing toward the same European wallets.
More

Gogoro’s Q3 Report Card: Will the Battery-Swapping Gamble Finally Pay Off?

(SeaPRwire) - The numbers on Gogoro's balance sheet will tell you everything you need to know about the battery-swapping economy. Not the press releases. Not the accolades pinned to their website. The quarterly earnings. November 11 is the day traders and analysts will separate conviction from hope. Gogoro built an infrastructure play on a razor-thin margin model. Swapping stations cost money to build. Batteries degrade. Riders subscribe. The question now is whether the unit economics finally align. Let's look at what Gogoro has actually claimed publicly. They power nearly 700,000 riders. Over 900 million battery swaps have been completed. More than 2,700 GoStation locations are operational globally. These are the numbers they put in their investor materials. The Q3 financial results arriving before markets open on Wednesday will reveal whether those riders are converting into sustainable revenue. Fortune called them a "Change the World" company in 2024. Fast Company named them Asia-Pacific's most innovative. MIT flagged them among 15 climate tech companies to watch. Frost & Sullivan crowned them global company of the year for battery swapping. Awards do not pay for station expansion. They do not fund R&D on next-generation cells. What they do is signal market confidence. Whether that confidence holds depends on what shows up in the revenue and gross margin figures. The deeper tension here is between infrastructure scale and capital efficiency. Battery swapping requires dense physical networks. Each GoStation is real estate, real equipment, real electricity. Competitors who bet on plug-in charging avoid that capex but sacrifice convenience. Gogoro's thesis is that convenience wins urban markets. The risk is that convenience is expensive. The Q3 results will show whether the network effect is compounding or plateauing. Revenue growth against station count is the metric that matters. Rider retention matters more than rider acquisition at this stage. The webcast at 7 a.m. Eastern Time will be where management addresses these questions directly. An archived version will sit on the company site for two weeks after. For investors tracking the sustainable mobility thesis, this earnings call is not a formality. It is a stress test.
More
Why Abbott International’s Rebrand Isn’t About a New Logo — It’s About Survival in a Saturated Wealth Market Business

Why Abbott International’s Rebrand Isn’t About a New Logo — It’s About Survival in a Saturated Wealth Market

(SeaPRwire) - Let's be honest. When a mid-tier wealth manager rebrands, nobody cares about the logo refresh. The real question is whether they're pivoting from a niche position they can't defend to a broader play they might actually win. Abbott International is doing exactly that. They spent 2026 consolidating their corporate structure, bringing domain alignment in April, and launching a new website in July. That's not aesthetics. That's triage. The press release frames this as an evolution. "From primarily investment-focused toward a broader wealth management model." Read between the lines. Investment management alone is a low-margin game with razor-thin differentiation. Every family office, every boutique firm, every global bank does it. The real money in wealth management isn't managing portfolios. It's managing relationships. It's fee-based planning that sticks. That's what Abbott is reaching for. The CEO, Jianyu Luo, says the company has developed considerably over the past year. "Developed" is generous coding for restructuring. The consolidation of corporate assets, digital properties, and intellectual property under one structure suggests they were fragmented before. Fragmentation kills valuation. The official facts are straightforward. The abbottinternational.com domain was unified in April 2026. The new corporate website went live in July. Investment management, wealth planning, and client services now sit under one identity. The revised offering targets clients across different markets and financial circumstances. The company works with individuals, families, and institutions. They emphasize long-term client relationships and integrated services. Nothing controversial there. But the industry subtext is clear. The wealth management space in Greater China and the broader Asian corridor is among the most crowded in the world. You either differentiate through technology, through scale, or through positioning that nobody else owns. Abbott is betting on positioning. They're trying to become the firm that treats investment decisions as one piece of a larger financial life picture. That's a defensible niche if you execute well. What I want to know is whether this rebrand actually changes anything on the ground. Clients don't care about your domain strategy. They care whether their advisor understands their tax situation, their succession plans, their liquidity needs. The press release mentions all of this. But execution is everything. And execution requires people who aren't just investment managers wearing wealth planner hats. It requires genuine multi-disciplinary capacity. That's hard to build. That's harder to keep. The China angle is significant. Abbott is explicitly developing business there while maintaining an international footprint. That's a double-edged strategy. Chinese high-net-worth clients are sophisticated. They've worked with UBS, with Credit Suisse, with local state-backed firms. A rebrand won't impress them. A track record will. And that takes years, not a new website launch. Here's my assessment. The rebrand is real. The restructuring behind it is real. But the competitive landscape hasn't shifted by a single degree because of it. Abbott International is now better positioned to compete in the broad wealth management segment. That doesn't mean they'll win there. It means they've entered the fight. The market share reshuffling will depend on whether they can convert this corporate realignment into actual client acquisition and retention gains over the next 18 to 24 months. Watch their client numbers, not their press releases.
More
EC-Council Just Bought a Ticket Into the Insurance Business — and the Premiums Are the Least Interesting Part Business

EC-Council Just Bought a Ticket Into the Insurance Business — and the Premiums Are the Least Interesting Part

(SeaPRwire) - Strip away the press-release polish and this is a talent-market land grab wearing an M&A costume. EC-Council, the company behind the Certified Ethical Hacker credential, announced on October 22, 2026, that it has acquired Cyber Insurance Academy, the credentialing body for the cyber and AI insurance industries. Nobody is selling software here. Nobody is selling threat feeds. What changed hands is a certification pipeline, the accreditation rails attached to it, and the trust of an industry that barely understands the technology it now prices. That is the real asset, and the announcement dances around it politely. The stated terms are straightforward. Cyber Insurance Academy keeps its brand, its leadership, and its base in Delaware. Guy Simkin stays on as Co-Founder and CEO. Asaf Armoni remains Co-Founder, CTO and COO. The entity operates as an EC-Council Company. Its programs carry accreditation from CII, ANZIIF, RIBO and NIBA, with continuing education approval in more than 45 U.S. states. That regulatory footprint alone would take years and serious money to replicate from scratch. EC-Council skipped the queue by writing a check, which is exactly what a rational buyer does. The product roadmap tells you more than the deal structure. The flagship Certified Cyber Insurance Specialist designation has been rebuilt as CCIS v2, now covering AI-driven threats, AI governance and AI-related insurance exposures. Beyond that, the Academy plans to expand from cyber insurance into three adjacent territories: AI risk, emerging technology risk, and role-based technology education for insurance professionals. Delivery runs through self-paced learning, certifications, professional designations and enterprise programs aimed at carriers, brokers and managing general agents. Note the sequencing. Cyber stays core, AI rides shotgun, everything else follows. The subtext is a labor arbitrage problem the release actually admits to. Underwriters, brokers, risk managers and claims professionals rarely come from technology backgrounds. Deep technologists almost never speak insurance. Simkin put it bluntly: every insurance professional is now a technology risk professional, whether they realize it or not. EC-Council chose not to invade this market from outside. It bought the organization already closing the gap from within. That is cheaper than building credibility, and credibility is the only currency that matters in credentialing. Watch the competitive ripple. Every cybersecurity training vendor now faces a blueprint for vertical escape. Selling CEH seats to security teams is a crowded, commoditized game. Selling AI-risk fluency to an entire insurance workforce, backed by accreditations in 45-plus states, is a recurring-revenue annuity with regulatory moats. EC-Council also gains a captive distribution channel for its broader Adopt. Defend. Govern. framework. Jay Bavisi framed it as people, process and technology. Translated, it means course content no longer sourced externally, faster catalogue expansion, and margin staying in-house. The next acquisition in this space will not be a training company buying a training company; it will be an insurer or a broker buying the credentialing body outright.
More

$1.04 Trillion in BRI Loans Won’t Build a Single Road Without This

(SeaPRwire) - Seven trillion yuan is a staggering sum. Over a decade. Through more than one hundred and thirty partner countries. Yet standing at the Financial Street Forum in Beijing last Wednesday, listening to Export-Import Bank of China officials present these figures alongside pledges of new financial innovation, I found myself struck by a question no press release will answer: what portion of that money actually transforms into roads, ports, or power plants that generate revenue instead of debt? The official numbers are precise and carefully curated. Chen Huaiyu, chairperson of CEXIM, presented a portfolio spanning over 7 trillion yuan in loans with a newly announced 30-billion-yuan special financing quota for China-Europe freight trains and what was described as the market's first basket of panda bonds involving BRI partner countries. Beijing's own trade statistics, as Vice Mayor Tang Wenhong reported, show 1.93 trillion yuan in commerce with BRI partners out of a total 3.19 trillion yuan for 2025 — sixty point four percent of the capital's foreign trade volume. The subtext, however, tells a more complicated story. CEXIM's partnerships with the New Development Bank and the World Bank signal an acknowledgment that traditional sovereign lending alone cannot absorb the risk profile of infrastructure projects in emerging markets. Kenya's Cabinet Secretary John Mbadi Ng'ongo delivered a pointed message from a satellite venue: infrastructure remains central to national development agendas, but the sectors requiring investment — transport, energy, water, ICT — demand financing that is not merely accessible but genuinely affordable and sustainable over decades, not just through groundbreaking ceremonies. Lesotho's Finance Minister Retselisitsoe Matlanyane raised a different concern entirely. She pointed to China's own experience gradually opening its financial system while strengthening domestic institutions as something African countries might learn from, but the underlying implication was unmistakable: financial inclusion without institutional depth creates vulnerabilities, not development. The panda bond framework is clever branding. Its utility depends entirely on whether the underlying assets — the railways, the power stations, the logistics corridors — produce the cash flows required to service the debt without resorting to restructuring. Professor Hu Qimu of Huaqiao University's Maritime Silk Road Institute framed the current moment as a shift toward more diversified and sustainable financing models. That framing is accurate in direction but potentially misleading in timeline. The signing of cooperation agreements between CEXIM and various international financial institutions represents a structural evolution in how BRI financing is packaged. It does not, in itself, change the fundamental economics of whether a highway through eastern Africa generates enough toll revenue to repay a yuan-denominated loan over twenty years. The governance implication is clear. China has moved from being primarily a bilateral lender to orchestrating a more complex ecosystem of multilateral development banks, private capital, and local partners sharing investment risk. That ecosystem reduces any single institution's exposure. But it also fragments accountability. When a project underperforms, the question of who bears responsibility moves from a straightforward creditor-debtor relationship into a web of cooperative agreements and joint financing structures that no textbook currently covers. The practical consequence for developing nations is that they now negotiate with a system rather than a lender. That system offers more capital and more sophisticated instruments. It also demands more institutional capacity from borrower governments to manage complex, multi-party financing arrangements and deliver the regulatory and policy environments that private capital requires to participate meaningfully. The BRI is not financing infrastructure anymore. It is financing the conditions under which infrastructure financing becomes possible.
More
The ‘Human-Verified’ Trojan Horse: NexCut Turns Operator Expertise Into the Dataset That Replaces Them Business

The ‘Human-Verified’ Trojan Horse: NexCut Turns Operator Expertise Into the Dataset That Replaces Them

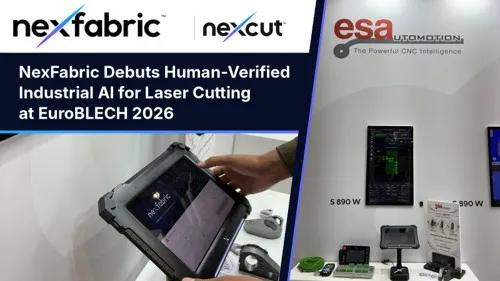
(SeaPRwire) - Nobody at EuroBLECH 2026 will tell you the real story about NexFabric's "human-verified" industrial AI. They have wrapped a diagnostic data capture operation in the language of operator support. The operator still "makes the call." The operator still "confirms" every hardware check. But every diagnosis gets logged. Every procedure gets saved for the next shift. Every new operator's learning curve gets documented in a central production dashboard. That is not augmentation. That is knowledge extraction wearing a lab coat and asking for confirmation at every step. The human verification framing is not a limitation. It is the precision mechanism. It ensures every data point is accurate. It ensures every procedure is actionable. It makes the platform more valuable with every interaction. And every interaction goes into NexFabric's proprietary database. Here is the official story of NexCut. It pairs AI-assisted analysis with operator-confirmed checks for laser cutting diagnostics. Each machine gets a touchscreen operator station and a connected hardware module. The module feeds process signals into the platform. When cut quality drops, NexCut combines those signals with physical checks. The operator inspects the lens, checks gas pressure, verifies focus position, assesses cutting height, examines the nozzle, and evaluates machine stability. NexCut narrows down the likely cause. It explains why. It points to the fix. The operator decides. The official story makes sense. The industry subtext is entirely different. NexFabric is building a proprietary library of manufacturing failure modes and their confirmed resolutions. Every operator interaction becomes training material. Every confirmed diagnosis becomes a reusable procedure. The human verification is the data quality gate. Without it, the dataset would be noisy. With it, the dataset compounds. NexFabric debuted NexCut at EuroBLECH on the stand of Esautomotion, Hall 15, Stand E28, after a first showing at CIIF in Shanghai. That sequencing tells you something. They tested in Shanghai. They are now demonstrating in Germany. They are building the European manufacturing base case while the Asian data foundation is already compounding. The workforce statistics NexFabric cites are real. Germany's Federal Statistical Office projects 12.9 million workers, close to 30% of the workforce, will reach retirement age by 2036. Italian companies reported difficulty filling 47.8% of planned hires. CNC operators and welders are among the hardest roles to fill, according to a CGIA analysis of Unioncamere Excelsior data. These are genuine problems in European manufacturing. NexFabric is not lying about them. The proof of concept at Soluzioni Markaurelio S.r.l. in Avezzano, Italy, is testing specific targets. Average guided diagnosis of 7 to 11 minutes. A 50 to 70% reduction in setup time. Reduced startup scrap and machine stoppages. New operators working independently within two to four weeks. Those numbers sound like a productivity improvement story. Read them as a replacement clock. Two to four weeks is not how long it takes to develop a decade of machine intuition. The veteran operator spent years learning by watching sparks and feeling vibration and listening to cutting sounds. NexCut compresses that learning curve to weeks. That compression is not neutral. It accelerates the point at which the original knowledge holder becomes economically dispensable. NexFabric is not solving the knowledge transfer problem. They are narrowing the transfer window until the transfer becomes unnecessary. And once the window closes, the operator who held the knowledge for decades has no role left. The endgame is visible. Industrial AI companies positioning themselves as human-centered are building proprietary diagnostic datasets that will eventually make the human layer optional. The architecture already contains the seeds of that transition. Start with human verification because model confidence is not yet sufficient. Tighten the decision guidelines as the dataset expands. Phase out confirmation steps once confidence thresholds are met across enough failure scenarios. NexFabric plans to work with multiple industrial partners and dealers to broaden access. That distribution strategy matters. Each new partner means more machines connected. Each connected machine means more diagnostic data flowing into the platform. Each data point means higher confidence in the model. Higher confidence means fewer human checks required. The supply chain question is not whether operators will accept guided diagnostics at the machine. That adoption piece is trivial. The supply chain question is whether laser cutter manufacturers, Esautomotion among them, understand what they are becoming at shows like EuroBLECH. They are not just distribution channels for an aftermarket product. They are becoming the on-ramp to a platform that will eventually own the full relationship between their machines, their operators, and their process knowledge. The person who decides what to cut and how is being slowly extracted from that equation. They simply do not know it yet. NexFabric CEO Stefano D'Andria said NexCut helps and teaches, and that the decision always stays with the person at the machine. That is true today. It will not be true forever. The platform is designed to outgrow the human in the loop. That is what proprietary diagnostic data does when it compounds across enough machines and enough failures and enough shifts.
More
A Korean Supplement Claims It Beat NMN, Name-Drops Harvard, and Cured 13 Diseases — Let’s Read That Press Release Slowly Business

A Korean Supplement Claims It Beat NMN, Name-Drops Harvard, and Cured 13 Diseases — Let’s Read That Press Release Slowly

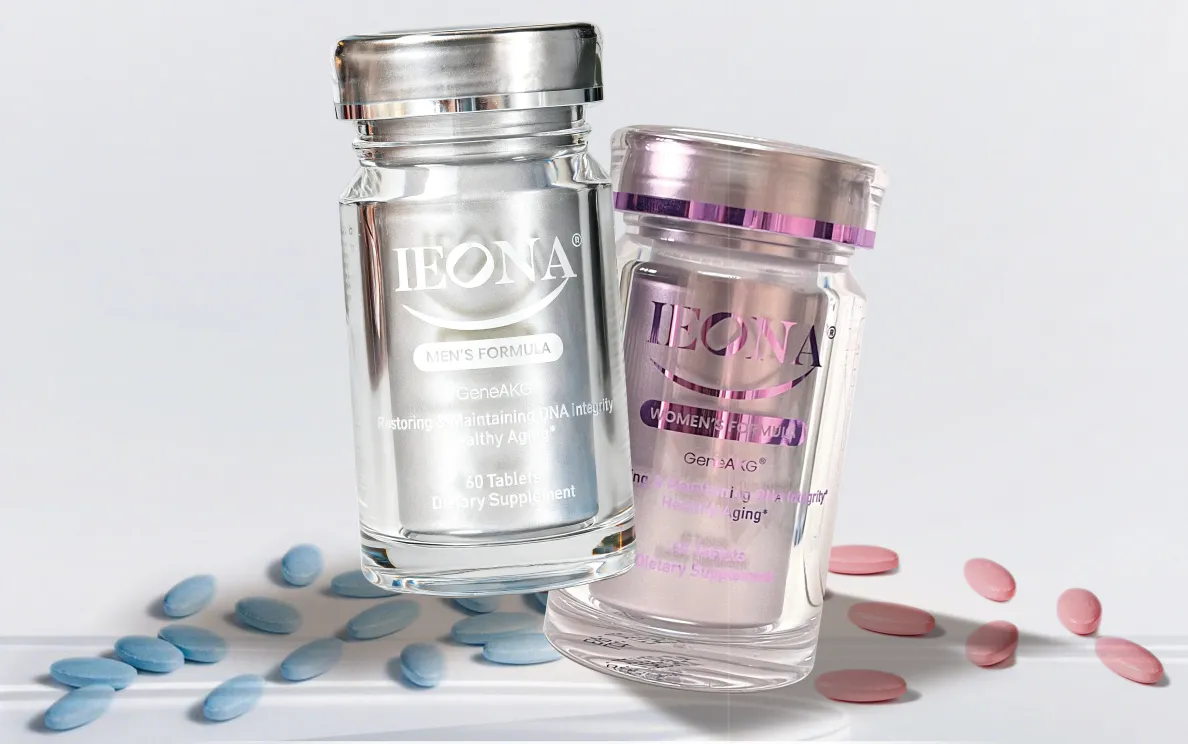
(SeaPRwire) - Here's my honest read on IEONA GeneAKG®. It's either the most important longevity compound since rapamycin, or it's the most skillfully written supplement press release of 2026. The product comes from Hanmi Life Sciences under NEXTEYE Group, a KOSDAQ-listed company (137940.KQ). The pitch is bold. AKG, a TCA cycle intermediate, supposedly outperforms NMN on NAD+ and sirtuin levels. The team is led by a Harvard-trained doctor. And David Sinclair has "reportedly acknowledged" its potential. Notice that word. Reportedly. It appears twice in the release, doing enormous amounts of work. Strip the adjectives and here's what actually exists. In 2020, the team published animal research showing GeneAKG increased NAD+ and sirtuin protein levels, with effects on mitochondrial ATP production. Third-party evaluations reported a 44.8% reduction in reactive oxygen species, up to a 53.2% increase in telomerase activity, and up to 77% higher SPNS1 gene expression. The formula stacks GeneAKG with fisetin for cellular clearance and pterostilbene for energy production. There are also gender-specific versions. Men's gets saw palmetto and zinc. Women's gets phytoestrogen-like compounds. Now the clinical claim, which deserves its own paragraph. A Phase I trial at NewMed Hospital in the US reportedly showed patients with chronic conditions improving across 13 common chronic diseases, with 128 clinical indicators returning to normal ranges. I've covered longevity biotech for years. Phase I trials are safety studies. They are not designed to demonstrate efficacy across thirteen diseases. One trial, one hospital, thirteen conditions, 128 normalized markers. That pattern should make any careful reader pause. Extraordinary breadth like that usually signals marketing ambition, not validated biology. Here's the macro game. The post-NMN regulatory chill in the US left a vacuum in the consumer longevity market. Brands need a successor molecule with a plausible mechanism and a clean story. AKG fits perfectly. It has real biochemistry behind it, aging-related decline is documented, and it's not tangled in the FDA's NMN drug-exclusion fight. So Korean manufacturers with KOSDAQ listings are positioning early, wrapping the molecule in "world-first patented" framing and gender segmentation. That's not science strategy. That's shelf-space strategy dressed in a lab coat. The competitive moat claim is thinner than it sounds. Fisetin, pterostilbene, saw palmetto, zinc — these are commodity nutraceuticals available from any contract manufacturer in Gyeonggi-do or New Jersey. The defensibility rests entirely on the proprietary GeneAKG processing and the 2020 animal data. If independent labs replicate the NAD+ and telomerase findings, Hanmi Life Sciences has a genuine asset. If they don't, this becomes another longevity brand living off affiliate marketing and a Harvard name-check. The next eighteen months of independent replication will decide which. Watch for whether the peer-reviewed human data ever materializes in a journal anyone has heard of — that's the only tell that matters.
More

JETOUR’s Mud-Splattered Gambit: Why Off-Road Tech Is No Longer Just for the Obsessed

(SeaPRwire) - On a rain-slicked forest road in Moganshan, Zhejiang, a handful of journalists and influencers pointed cameras at SUVs crawling through water crossings and cross-axle obstacles. October 21st, 2026. The 2026 JETOUR Global Technology Experience Day wasn't designed as a subtle product launch. It was a declaration. The brand wants you to believe that rugged capability can now sit comfortably beside a four-screen smart cockpit and high-quality audio. The question isn't whether the hardware works. It's whether this strategy can crack open a segment dominated by established players with deeper pockets and longer pedigrees. JETOUR has been building toward this moment since its 2018 launch. Today the brand claims more than 50 million global users across 100 plus countries, supported by over 2000 sales and after-sales service outlets. Its R and D network stretches across the EU, the Middle East, Central and South America, and ASEAN. That's substantial reach for a marque that barely exists in North American showrooms. The T Series targets the light off-road segment. The G Series, headlined by the G700, positions itself higher in premium luxury off-roading. Together they form a two-pronged strategy under what JETOUR calls its "Travel+" framework. This isn't a company guessing at market direction. It's a company mapping territory deliberately. The technology on display reveals a clear design philosophy. The XWD Intelligent 4WD system translates experienced drivers' terrain judgment into algorithms. Seven drive modes cover Eco, Standard, Sport, Snow, Mud, Sand, and Rock, with a one-touch "X" intelligent off-road mode handling the rest. During the Moganshan test, T Series models navigated water crossings, water-fording bridges, and cross-axle sections. The electronic jaw-type differential lock kicks in when wheel grip changes, redistributing power automatically. In the G700, the GAIA super hybrid powertrain pairs with CDC intelligent suspension and air suspension that adjust damping and ride height for uneven surfaces. This is engineering aimed squarely at people who want capability without the learning curve. The commercial logic behind this approach deserves scrutiny. The light off-road SUV segment has become one of the most crowded spaces in global automotive markets. Traditional players like Toyota, Ford, and Mercedes offer proven capability. Chinese brands including Maxus, Great Wall, and Tank have pushed hard into this category over the past three years. JETOUR is entering late but with a differentiated angle. By pairing accessible off-road technology with premium cabin features and a hybrid powertrain option, the brand is targeting buyers who would otherwise choose a luxury crossover. The G700's four-screen smart cockpit and multifunction seats aren't accessories. They're deliberate positioning signals aimed at buyers who value comfort as much as capability. What matters now is whether JETOUR can convert this technology narrative into sustained market share. The brand's global distribution network provides a foundation. The Travel+ strategy gives it a coherent product framework. But automotive markets are won on reliability, resale value, and brand trust built over decades. JETOUR has five years of existence against competitors with sixty. The technology is impressive on paper and in a controlled test drive environment. The real test will come when these vehicles face long-term ownership demands across diverse climates and driving conditions from urban commuting to serious trail use. JETOUR is betting that convenience-seeking buyers will trade off-road expertise for algorithm-assisted capability wrapped in luxury packaging. If the technology delivers consistently, that bet pays off. If it doesn't, the brand risks becoming another flash in a segment where durability is the only currency that matters. The Mudanshan test drive demonstrated what's possible. Ownership will reveal what's sustainable.
More

A Non-Binding MOU With a Binding Anchor: Green Circle’s Real Play in Airport Decarbonization

(SeaPRwire) - Three companies sign a non-binding document and a stock ticker gets a wink. That is the whole trick. Green Circle Decarbonize Technology announced on October 21, 2026. The company entered into an MOU with SANVO Fine Chemicals Group Limited and Menzies Eurus Aviation Services Limited for airport energy efficiency. The press release reads like a template filled in by someone who needed three logos on one slide. The MOU is non-binding. That means no one is obligated to deliver anything. Yet the release speaks of "tailored decarbonization strategies" and "upgraded benchmarks for environmental excellence." Those are words, not contracts, not revenue. I have watched enough MOU-driven stock movements over the past decade to know what is happening here. When a public company like GCDT announces partnerships with aviation ground handlers, the market reads validation. The industry reads something else entirely. It reads a company still hunting for paying customers. The product is a thermal storage panel that has never seen large-scale commercial deployment. Here is what actually happened. Green Circle Decarbonize Technology Limited is a Cayman Islands holding company operating through its Hong Kong subsidiary, Boca International Limited. It provides energy-saving solutions built on proprietary phase change thermal energy storage materials and thermal engineering services. Its core product is the BocaPCM-TES Panel. SANVO Fine Chemicals brings chemical formulation capabilities. Menzies Eurus Aviation Services brings airport ground-handling operations. The stated plan is to combine these inputs to improve HVAC efficiency across airport infrastructure. But one earlier fact anchors everything. In September 2026, Green Circle already signed a strategic partnership agreement with SANVO. Under that binding agreement, SANVO was appointed sole supplier. It also became the exclusive manufacturer for mass production of BocaPCM-TES Panels in the People's Republic of China. The October MOU extends the SANVO relationship into a new operational venue. It does not create a new manufacturing relationship. It adds deployment access. Strip the promotional language and the architecture becomes clear. Green Circle needed manufacturing capacity. SANVO provides that exclusively in China. Green Circle also needed real-world deployment sites where phase change thermal storage can be tested at scale. Menzies Eurus provides airport access. Menzies Eurus is a joint venture. Menzies Aviation holds 49 percent. Eurus Express Limited holds 51 percent. Eurus Express is headquartered in the Greater Bay Area and the Hainan Free Trade Port. It operates 58 locations across 17 countries. That global footprint is the asset being leveraged. But the MOU says the parties will work together to introduce energy-saving solutions across airport facilities. It does not say how many airports. It does not say what the financial terms are. It does not say when deployment begins. The September agreement with SANVO is binding. The October MOU is not. Green Circle has locked down manufacturing. What it is shopping for now is proof of concept and a narrative for investors. The airport sector burns enormous amounts of energy on HVAC alone. A phase change material product could genuinely reduce that load. But the technology still needs to prove cost-effectiveness in real terminal conditions. The MOU gives Green Circle a door to walk through. It does not guarantee anyone walks. The decarbonization of airport infrastructure is a crowded field. Major HVAC manufacturers already offer retrofittable thermal storage solutions. Airlines are signing corporate net-zero commitments with their own in-house engineering teams. What Green Circle brings is a specific chemical formulation embedded in a panel product that SANVO now exclusively manufactures in China. That exclusivity is real. The deployment question is not. If Green Circle can demonstrate measurable energy savings, it will have performance data no competitor can match. That data would cover Menzies Eurus-managed airport facilities in that specific geography. If it cannot, the MOU becomes another line in a prospectus that investors skim past. The next twelve months will tell us which version this is. For now, the supply chain advantage is locked. The market share question is still open. And in this game, open means nothing is settled.
More

Hainan’s Deep-Sea Gambit: Why 1,400 Companies Are Quietly Building the World’s Next Underwater Industrial Base

(SeaPRwire) - Let me be blunt about what most Western readers will miss in this announcement. The Fourth Hainan Free Trade Port International Science and Technology Innovation Cooperation Forum and Deep-Sea Technology Innovation Conference, running November 3 to 6, 2026, in Sanya, is not a conference. It is a procurement showcase dressed up as one. I have watched enough of these events over the years to recognize the pattern. When a provincial government labels a gathering "a new home ground for global deep-sea innovation forces," that is not marketing fluff. That is a claim of ownership over an industrial category. The Americans did this with semiconductors in the 1980s. The Chinese are now doing it with the ocean floor. And the timing matters. Deep-sea equipment, from pressure-rated housings to autonomous underwater vehicles, sits in a supply chain that nobody in Washington or Brussels currently dominates. Hainan is moving into that vacuum with state infrastructure, state capital, and an open door for foreign partners who want test access they cannot get elsewhere. One main forum, seven parallel forums, three supporting events. That structure is built for dealmaking, not keynote applause. Now look at the official facts, then read what sits underneath them. The release says the National Marine Comprehensive Testing Site (Deep Sea) is operational, and a seafloor scientific observation network is under accelerated construction. The subtext: testing infrastructure is the true moat in this industry. Any hardware architect will tell you that deep-sea gear fails in ways simulation cannot predict. Salt corrosion, pressure cycling, biofouling. You need real water, real depth, real time. Hainan is offering exactly that, at scale, to anyone who signs on. Then there is Sanya Yazhou Bay Science and Technology City, which has attracted more than 1,400 marine-related enterprises. That number is the whole story. Cluster density of that kind means a prototype can go from a machining shop to a test vessel within the same zip code. I saw a smaller version of this dynamic in Shenzhen's drone belt fifteen years ago. It did not stay small. The cooperation record deserves equal scrutiny. The first three editions, running since 2023, produced a China-Egypt strategic partnership in marine scientific research, two consensus documents on pooling deep-sea big science, an Underwater Robot Industry Alliance, and a deep-sea technology venture capital fund. Participation grew from nearly 20 countries to 25, and from 170 institutions to more than 250. On paper, this reads like soft diplomacy. In practice, it is standard-setting by another name. Consensus documents shape who defines abyssal research protocols. An industry alliance sets interface specifications for underwater robots. A venture fund decides which startups live. Add the stated cooperation with the United Kingdom, Germany, Canada, and Singapore, and you see the real play. Hainan is positioning itself as the neutral node through which Western marine research must pass to reach Pacific depth. The topics on the agenda, from marine biomedicine to deep-sea oil and gas engineering to cultural heritage protection, map almost perfectly onto every commercially viable ocean vertical. Nothing on that list is accidental. So here is my plain-spoken read on the supply chain landscape. Whoever controls deep-sea testing capacity, equipment standards, and early-stage capital in the same geography ends up controlling the hardware. Right now, only one place on earth is assembling all three at once, and it is a tech city on the southern tip of Hainan Island. Western marine equipment firms will show up in Sanya this November, because the test site is too useful to boycott and the fund is too tempting to ignore. They will sign memoranda, share data, and slowly relocate their R&D gravity. By the time anyone in a committee hearing notices, the connectors, the pressure hulls, and the acoustic modems will all be spec'd to standards written in Yazhou Bay.
More

The Oral Peptide Trap: Why 2026’s Pharma Supply Chain Is Broke Before It Starts

(SeaPRwire) - WuXi AppTec just published a manufacturing confession from San Diego. Oral peptides aren't a patient convenience story. They're a capacity crisis wrapped in soft language. When bioavailability drops below 1%, an oral peptide needs 10 to 100 times the API of its injectable version. A 1 mg subcutaneous dose becomes roughly 100 mg orally. That's a multiplier. Not a margin. Most pharmaceutical companies are still pulling oral program budgets from injectable dose spreadsheets. The gap isn't a forecasting problem. It's a fundamental misread of what oral delivery does to a manufacturing supply chain. The press release lays out the math with an approved product example. Mycapssa, Chiesi USA's oral octreotide acetate, needs 20 mg orally to match 0.1 mg subcutaneously. That's a 200-fold difference in administered mass. The FDA label backs this up. The release flags oral semaglutide as a boundary case, not a universal proof. Industry subtext: companies see the oral label and think formulation problem. The actual problem starts at the API level. You can't estimate API needs from an injectable dose. Eventual dose, patient population, route yield, purification recovery, and drug product requirements all get modeled together upfront. WuXi TIDES ran a case study proving this. Four synthesis routes. Eight condition sets. A next-generation oral cyclic peptide. From 50 grams to 1 kilogram to 6 kilograms for GLP batch in six months. GLP and GMP API delivered in 10 months total. That timeline isn't impressive. It's the compressed reality of working backward from a demand multiplier traditional planning never accounted for. The synthesis bottleneck gets more complicated. Conventional solid-phase synthesis collapses past 50 amino acids. Coupling efficiency and overall yield fall sharply. WuXi TIDES took a peptide conjugate that originally needed 87 steps. They broke it into fragments under 50 amino acids. Reconnected them by chemical ligation. Overall yield went from less than 0.1% to 3%. Parallel fragment production shortened the timeline. Published tirzepatide work at kilogram-scale GMP manufacture confirms the approach at volume. Hybrid solid-phase and liquid-phase routes. Continuous processing. Real-time analytical monitoring. Nanofiltration for intermediate purification. But here's where industry subtext diverges from the release narrative. The bottleneck isn't synthesis anymore. It's purification. WuXi TIDES hit unstable column material under basic buffer conditions. They screened alternatives. Worked with a supplier on a custom alkali-resistant blend. Impurities dropped 80%. Final overall yield increased 20%. Three unnatural amino acid starting materials had limited commercial supply. WuXi TIDES developed synthetic processes in-house. Produced more than 3 kilograms. An external supply dependency came off the critical path. Building blocks aren't procurement line items. They're gatekeepers of program timelines. The blunt truth about the supply chain landscape for oral peptides is straightforward. You multiply API demand. You parallelize synthesis. You build purification capacity that matches actual output. You manufacture building blocks before they become chokepoints. Companies that treat oral peptide manufacturing as a formulation challenge with a manufacturing appendix will hemorrhage capital across every phase of development. The CRDMO model isn't an outsourcing preference. It's the only architecture that coordinates API volume, solid-state requirements, formulation process, and finished-dose capacity under one quality system from preclinical through commercial stages. Whoever learns this coordination first won't just win manufacturing contracts. They'll set the standard the rest of the industry has to catch up to.
More
eSUN’s TPE-95A is the 3D Printing Industry’s Wake-Up Call — and TPU Suppliers Should Be Nervous Business

eSUN’s TPE-95A is the 3D Printing Industry’s Wake-Up Call — and TPU Suppliers Should Be Nervous

(SeaPRwire) - The whole flexible filament market in FDM printing has operated on a single compromise for years. You pick either a material that prints easily and recovers its shape poorly, or one that bounces back beautifully but chews through extruders and slows production to a crawl. That tension defines every product decision a maker or manufacturer makes. eSUN sees it clearly. The company is positioning its new TPE-95A not as another incremental upgrade but as the answer to that old tradeoff. This is what happens when a manufacturer finally decides to stop catering to the middle of the market. Here are the numbers eSUN is putting on the table. Rebound rate tops out at 58 percent, which the company says is 93 percent higher than its own TPU-95A. Printing speed reportedly jumps up to 137 percent faster. Abrasion drops by nearly 30 percent. Hardness sits at 95A, sitting right in the zone where phone cases and watch bands live. Performance remains stable down to minus 30 degrees Celsius. Fatigue resistance and low compression set are called out as key durability features, along with yellowing resistance. The company points to real end-use applications like anti-slip components and functional flexible parts rather than abstract demos. This is not a lab curiosity. These are production-grade claims meant for shops that run parts daily. What matters most practically is what this means for a printer running Bambu Lab hardware. Firmware presets are built in under the TPU Generic and Bambu categories. That ecosystem lock-in is deliberate and effective. Printers that already live inside that closed loop get a frictionless path to adoption. Outside of it, users still face the age-old flexible filament problems of proper drying, stable feeding, and flow ratio calibration. The material does not erase the mechanical realities of extruding elastomers. It just shifts the balance toward recoverable elasticity at higher throughput. That is a meaningful operational change for anyone stamping out cushioning structures or wear-resistant straps on a regular schedule. The strategic read is straightforward. If these claims hold up in independent testing and production runs, TPU suppliers face margin compression and a re-evaluation of their product roadmaps. Flexible filament buyers now have a credible alternative that does not sacrifice speed for elasticity. The supply chain will sort itself out through price competition and adoption curves, not through announcements. Until then, the question is whether eSUN can scale consistent quality across larger spool runs and wider printer compatibility beyond the Bambu ecosystem. That is where most flexible material launches stall quietly.
More