The Quiet War for Crypto Trust: Why CoinW’s Messaging Pivot is a Major Red Flag for the Industry

(SeaPRwire) - We usually ignore the plumbing of digital asset exchanges because the narrative is always about yield, order book depth, or token speculation. But in 2026, the fatal weakness of most web3 platforms is not the interface. It is the inability to reliably communicate with their users during peak volatility. CoinW is partnering with EngageLab. This is not a vanity move. It is a structural repair job on a crumbling foundation. When you cannot guarantee that a user receives their two-factor authentication code or a critical market alert, you have not built a financial institution. You have built a liability waiting for a lawsuit. The press release frames this as "fortifying communications," but the subtext is far more alarming. It suggests that the existing infrastructure was insufficient. The official release states that CoinW is integrating EngageLab’s AppPush, OTP, and Email capabilities. The date is October 26, 2026. CoinW, founded in 2017, is described as a leading global platform. The specific integration targets three areas: secure app notifications, OTP delivery resilience, and transactional email. The claim is that this supports "secure and reliable communications" for a global user base. On the surface, it reads like a standard B2B software procurement. You buy a service, you improve SLAs. But look closer at the language. They are emphasizing "continuity" and "resilience." These are not words used when things are working well. They are words used when things break. The release notes that EngageLab supports delivery of trading alerts and account updates. It mentions that the OTP solution facilitates secure delivery of authentication codes. This is basic hygiene. Yet, outsourcing it to an "AI-first customer engagement platform" signals a gap in internal engineering capacity or a decision to decouple communication costs from core development. There is a stark contrast between the PR polish and the industry reality. The release lists EngageLab’s other clients: Dhgate, HelloRide, and the CNE of Ecuador. This customer base is interesting. Dhgate is a marketplace. HelloRide is a ride-hailing app. The CNE is a government electoral body. Now CoinW joins them. This suggests EngageLab is a generalist engagement layer, not a specialized high-frequency financial messaging provider. For a crypto exchange, millisecond latency and absolute reliability are non-negotiable. Using a platform that likely aggregates traffic for various consumer apps might introduce latency or prioritization biases. The "AI-first" tag in EngageLab’s description raises questions. Is this AI actually analyzing message delivery paths in real-time? Or is it just a marketing label for standard API routing? The release does not specify technical architecture. It does not mention dedicated edge nodes or failover protocols specific to financial transactions. It just says "reliable delivery." In finance, "reliable" is a relative term. If your OTP gets delayed by 30 seconds during a liquidation cascade, the user loses their position. The industry subtext is that CoinW is decoupling communication from its core trading engine to isolate risk. If the messaging layer fails, the trading engine stays up. It is a sensible architecture, but it reveals that the previous coupling was a single point of failure. The endgame here is consolidation of user trust through infrastructure dependency. CoinW is admitting that its home-grown solutions or previous vendors couldn't keep up with global scale. By switching to EngageLab, they are betting that a third party can handle the heavy lift of global connectivity. But this creates a new supply chain risk. Now, the security of CoinW users depends on EngageLab’s uptime and security posture. If EngageLab gets breached, CoinW’s authentication is compromised. The industry will see this trend across all major exchanges. Communication is no longer a feature; it is the primary security interface. The companies that succeed will be those that treat their messaging stack with the same rigor as their custody systems. This partnership is not about engagement. It is about survival in a market where one dropped notification can trigger a regulatory probe or a mass exodus of liquidity. The plumbing is broken. Now we are watching who fixes it first.
More

The Death of Monotherapy: Why ESMO 2026 Marks the End of Single-Target Lung Cancer Treatment

(SeaPRwire) - For years, the oncology world has treated EGFR-mutated non-small cell lung cancer with a rigid adherence to single-agent tyrosine kinase inhibitors. The prevailing assumption was that a highly selective TKI like osimertinib was the gold standard. This view has now fractured. The SANOVO trial data presented at ESMO 2026 exposes a critical blind spot in precision medicine. Patients with co-occurring MET overexpression were effectively being undertreated with monotherapy. The anxiety is no longer about finding a better single drug. It is about acknowledging that resistance mechanisms often exist from day one. The industry must pivot from reactive treatment to proactive, combinatorial strategies. The data from the Phase III SANOVO study is unambiguous. In treatment-naive patients with EGFR-mutated NSCLC and MET overexpression, the combination of savolitinib and osimertinib reduced the risk of disease progression or death by 44% in the overall population. The benefit was even more pronounced in the high MET overexpression group. Here, the risk reduction reached 55%. Median progression-free survival jumped to 24.9 months with the combination. This stands in stark contrast to the 11.1 months observed in the high MET subgroup receiving osimertinib alone. The overall survival endpoint also shows a meaningful improvement. The hazard ratio for OS was 0.48, extending median survival by 9.6 months compared to the control arm. These are not marginal gains. They represent a fundamental shift in what is clinically achievable. Commercially, this trial redefines the value proposition of upfront combination therapy. Historically, combinations were reserved for later lines due to toxicity concerns and cost. SANOVO proves that all-oral, dual-targeted approaches can be initiated at diagnosis. This preserves quality of life while extending survival. For HUTCHMED and AstraZeneca, this validates a multi-year investment in biomarker-driven strategies. The end-game is a market where standard-of-care decisions are dictated by comprehensive molecular profiling at diagnosis. Providers will move away from sequential trial-and-error. They will adopt targeted combinations based on MET status. The result is a longer-lasting efficacy window before resistance emerges. This extends the duration of care and alters drug reimbursement models. Payers must now consider upfront combination therapy as the primary baseline for this patient cohort.
More

The 21.8-Month Number That Breaks the GPRC5D Playbook: What Leads Biolabs’ ESMO Data Actually Means

(SeaPRwire) - Multiple myeloma treatment has been locked in a pattern for two years now. Every bispecific and every CAR-T hits the same targets. Every press release sounds the same. The only question left was whether someone could break out of the mold without burning cash on a clinical trial that ends in silence. Leads Biolabs walked into ESMO 2026 and answered that question with numbers that made the room uncomfortable. The 21.8-month median progression-free survival data for LBL-034 is not just a good result. It is a message sent to every big pharma oncology division that has been betting on GPRC5D as the next great platform prize. The numbers from the oral presentation at ESMO 2026 deserve scrutiny. Fifty-six patients enrolled with heavily pretreated relapsed and refractory multiple myeloma. The median prior therapy lines sat at 4.5, with a range stretching to 12. Seventy-three percent of patients had triple-class exposure. Fifty-seven percent had penta-drug exposure. Sixty percent were triple-class refractory. In the effective dose range of 400 to 1,200 μg/kg, the 41 patients treated posted a median PFS of 21.8 months. The 15-month and 18-month PFS rates held at 62.0 and 54.8 percent respectively. Duration of response data had not yet reached median. The 12-month and 18-month DoR rates stood at 77.0 and 68.4 percent. Time to complete response or better dropped from 5.60 months at 400 μg/kg to 3.06 months at 1,200 μg/kg. In the subgroups that matter most, LBL-034 did not flinch. Extramedullary disease patients posted a 75.0 percent ORR, with two patients hitting stringent CR. In the 1,200 μg/kg cohort, all EMD patients responded. Patients who failed prior BCMA-directed therapy showed an ORR of 85.7 percent with a 57.1 percent sCR rate. Penta-drug-exposed patients still achieved a 73.9 percent ORR and 34.8 percent sCR rate. On the safety side, no dose-limiting toxicities appeared up to 1,200 μg/kg. Nearly all CRS events were low-grade. Only one Grade 3 or higher CRS event was reported. Two cases of ICANS emerged, and both patients recovered fully. Adverse events affecting quality of life were predominantly Grade 1-2, concentrated in the early treatment period. Median treatment exposure reached 11.3 months. The real question here is what this means commercially for Leads Biolabs and what it signals for the broader bispecific race. The proprietary LeadsBody TCE platform has now earned its first clinical validation. The company's strategy is not to outspend the giants on a single target. It is to prove that a structural innovation in antibody design translates into a clinical differentiator. The 21.8-month median PFS is approximately twice the level reported in the pivotal studies of approved therapies targeting the same GPRC5D marker. That is not a rounding error. The platform claims reach beyond hematologic malignancies, into autoimmune diseases and solid tumors. Whether the big pharma licensing interest materializes as a blockbuster deal or gets shelved in a partnership graveyard remains the next chapter. The science has done its part. The market will decide whether it deserves a bigger audience.
More

CHANGAN’s Quiet War for the Middle East Is Being Won on the Service Counter, Not the Dealership Floor

(SeaPRwire) - Chinese automakers have spent years trying to outrun a reputation problem in the Middle East. Build quality was acceptable. Prices were aggressive. But trust was another conversation entirely. CHANGAN now appears to be shifting the battlefield entirely. It moved from competing on horsepower and horsepower-equivalent battery range to competing on the one metric that actually decides whether a buyer returns. The service counter. The 2026 CHANGAN Middle East and Africa Skills Competition in Muscat was not a photo opportunity. It brought together 47 professionals who had survived months of qualifying rounds across the region. The dates were precise. October 23 through 25, 2026. The first day was a theoretical exam. The second day stripped away the paper testing and moved straight into simulated customer scenarios. The service track covered advisor reception and precision diagnostics for both new energy and fuel vehicles. The sales track forced participants through real-world purchasing simulations. The result was not a vague exercise in good intentions. It was a quantifiable measurement of service attitude, hands-on expertise, and process adherence, all translated into actionable standards. The commercial logic behind this is straightforward and somewhat ruthless. CHANGAN is launching new products in the Middle East and Africa right now. Product launches create initial purchases driven by price and novelty. But repeat business, brand loyalty, and word-of-mouth referrals are entirely different revenue streams. They depend on what happens after the keys are handed over. Mr. Xiao, General Manager of CHANGAN Middle East & Africa Business Unit, stated that the competition enables teams to learn from each other in settings mirroring their daily work. That is not a soft statement about team building. It is a signal that the company has identified service delivery as the actual bottleneck between selling a car and keeping a customer for the next one. The "withU" service commitment mentioned in the release is not a marketing slogan. It is the operational framework under which all this training now falls. What makes this move noteworthy for industry observers is the timing and the scale. The competition is only in its second edition. Preparations are already underway for a global skills competition in Saudi Arabia in 2027. That trajectory tells you where management sees the lever of competitive advantage. It is not in engine specifications or infotainment screens. It is in the consistency of the customer experience across every market they operate in. Standardizing service quality across the Middle East and Africa is a supply chain problem, just dressed differently. It requires training infrastructure, evaluation systems, and a feedback loop that closes quickly enough to correct failures before they become permanent brand damage. The exchange component of the competition deserves attention as well. Front-line employees from different markets shared practical experience and local approaches. This is knowledge transfer happening organically between markets that CHANGAN could not achieve through corporate memos alone. A successful tactic developed in one country gets tested against the criteria of another. The weakest links in service delivery get exposed faster. Automotive retail in emerging markets has historically been fragmented. Dealerships operate with significant autonomy. Service standards vary from city to city. CHANGAN is attempting to centralize the quality of the customer interaction without stripping dealerships of their local agility. The unified judging criteria used across both the service and sales tracks suggest a deliberate push toward that balance. Consistent standards, locally adapted execution. That is the harder model to build but also the more defensible one. The brand is betting that superior service becomes its primary differentiator in a market where Chinese competitors are multiplying. When every rival can offer a similarly priced vehicle with comparable range, the remaining variable is whether the owner regrets the purchase three years down the line. CHANGAN is treating the service experience as that variable. The next two years will reveal whether this approach moves the needle on customer retention or simply adds another cost center to an already thin-margin operation.
More
BioNTech and BMS Drop a Bispecific Bombshell in the Second-Line Lung Cancer Graveyard Business

BioNTech and BMS Drop a Bispecific Bombshell in the Second-Line Lung Cancer Graveyard

(SeaPRwire) - Second-line metastatic non-small cell lung cancer remains a clinical dead end, a harsh reality for oncologists and patients alike. Once tumors progress on first-line immunotherapy combined with chemotherapy, the standard of care, docetaxel, offers a median survival extension of barely four months. BioNTech and Bristol Myers Squibb are stepping directly into this massive void with a bispecific antibody that has just delivered remarkably strong Phase 2 numbers, signaling a potential paradigm shift in how we tackle resistant lung tumors and offering a glimmer of hope where therapeutic options have historically been extremely limited, forcing the industry to rethink traditional sequential treatment algorithms. The global Phase 2 ROSETTA Lung-107 trial evaluated pumitamig, a PD-L1xVEGF-A bispecific immunomodulator, combined with docetaxel in fifty patients with metastatic NSCLC. Among thirty efficacy-evaluable participants, the confirmed objective response rate reached thirty-six point seven percent, accompanied by a disease control rate of ninety percent. Crucially, responses spanned multiple PD-L1 expression levels, showing forty-two point nine percent efficacy in low expressors and forty percent in high expressors. These figures are particularly striking given the heavily pretreated nature of the cohort, which had all undergone prior immunotherapy plus chemotherapy regimens. The clinical benefit translated into a median progression-free survival of six point nine months, nearly doubling the historical benchmark of under four months for standard docetaxel. The six-month progression-free survival rate stood at sixty-three point three percent, with a median time to response of just one point four months. On the safety front, the combination presented a manageable profile with no treatment-related deaths or dose-limiting toxicities, though twenty-two percent of patients experienced immune-related adverse events. Efficacy was observed across both squamous and non-squamous histologies, with a confirmed objective response rate of fifty-seven point one percent in the squamous subgroup. This data represents more than just a clinical victory; it is a strategic masterstroke in the highly competitive bispecific antibody arena. By targeting both PD-L1 and VEGF-A simultaneously, pumitamig attempts to re-engage antitumor immunity while simultaneously cutting off the vascular supply that resistant tumors use to grow. BioNTech and Bristol Myers Squibb are leveraging this dual mechanism to build a broad development program spanning multiple lung cancer settings, aiming to challenge established players and capture a significant share of the second-line market while signaling to Wall Street that the mRNA pioneer and the oncology giant have a highly lucrative pipeline to sustain long-term growth. The commercial implications are profound, as the second-line NSCLC market has long been neglected due to poor historical response rates. With a disease control rate exceeding ninety percent, pumitamig offers a compelling value proposition for payers and clinicians seeking to extend patient survival without introducing catastrophic toxicity. The consistent activity across diverse patient subgroups suggests that this therapy could bypass the need for complex biomarker stratification, simplifying clinical decision-making and accelerating widespread adoption. With four global Phase 3 trials already underway, the partners are positioning themselves to redefine the standard of care across multiple lines of therapy. Regulatory bodies will likely initiate a fast-track review for pumitamig in second-line NSCLC within the next twelve months, forcing rival bispecific programs to either demonstrate superior overall survival or face complete market marginalization as the standard of care solidifies around this new dual-targeting backbone, a strategic shift that will inevitably trigger a wave of consolidation among late-stage oncology developers struggling to keep pace with BioNTech and Bristol Myers Squibb's aggressive clinical footprint and prompting venture capitalists to aggressively redirect capital away from single-target monoclonal antibodies toward next-generation multi-ligand inhibitors.
More

Behind Bodor’s 1,400 m² Bet at EuroBLECH: The Real Weapon Is Not the Laser

(SeaPRwire) - Bodor Laser walked into EuroBLECH 2026 with over 1,400 m² of exhibition space spread across Hall 13, Booths A181 and A182. That is the largest footprint among every Chinese exhibitor at the world's leading sheet metal working trade fair. It also puts Bodor among the five largest booths at the entire show, which runs October 20 to 23 in Hannover. The square footage alone would be remarkable for any laser manufacturer. For a Chinese company competing against entrenched European and Japanese incumbents, it sends a signal. The real question is whether that signal translates into orders. Bodor is betting that it does. The bet is worth a hard look. The official press release frames two new premium tube laser cutting machines as the headline product debut. The four-chuck series uses a fully floating chuck configuration with unrestricted rotation. Conventional three-chuck machines lock rotation at fixed angles, which creates idle time on mixed-diameter batches. The four-chuck design breaks that constraint. It switches into a dual-process mode that significantly improves heavy-tube efficiency. The system automatically matches chuck logic to tube and part length. Intelligent stepless retraction allows operators to load short tubes without re-homing, which further boosts loading speed. For shops running heavy tube batches, unrestricted rotation eliminates angular dead zones that force manual repositioning. That is hours saved per shift. The double-chuck series takes a different approach. It integrates cutting, drilling, and tapping onto a single platform. An optional 14-position tool magazine cuts down workpiece transfers, repeated setups, and inter-process waiting. Laser scanning, visual recognition, and intelligent sensors detect tube contours, weld seams, and processing conditions in real time. The system then performs dynamic cutting-centre adjustment. This is not a marketing flourish at this point. It means the machine compensates for out-of-round profiles that would otherwise require manual recalibration and machine downtime. Zoom out from the specs and a different picture emerges. Bodor is not showing two machines at EuroBLECH 2026. It is presenting a complete metal fabrication portfolio. Three sheet laser cutting machines sit on the floor alongside the tube units. The P6 60 kW, the P3+Automation-12 kW, and the i3 6 kW span a wide power range. The P Series delivers up to 4G acceleration and 200 m/min speed. An automated system integrates sheet handling with raw material and finished-part storage for continuous production flow. Bending and welding solutions complete the workflow from cutting to finishing. A 3 kW robotic laser welder handles automated production lines. A Pro 1.5 kW handheld laser welder covers field repair and custom finishing work. German-speaking technical specialists staff the booth throughout the show. Bodor already operates service centres in Germany and Hungary with over 10 locally based professionals. The company serves 180-plus countries through 20-plus service centres and 500-plus service locations worldwide. That is not a showroom strategy. That is a service infrastructure strategy designed to make switching costs painful. The P Series automation is particularly relevant for shops that cannot run three shifts due to staffing constraints. Continuous production flow with reduced manual intervention means one operator can watch a system that previously needed three. The supply chain implication is blunt. Bodor has ranked No. 1 globally in sales of 1 kW-plus laser cutting machines for seven consecutive years, from 2019 through 2025, according to FORWARD Business Information Co., Ltd., Shenzhen. Seven years of volume leadership means the company has accumulated hardware reliability data that competitors without that volume simply cannot match. It also gives Bodor pricing power at scale. European metalworking shops face rising steel input costs, labor shortages, and tightening delivery windows. They need throughput. They need fewer touchpoints between machines. They need a service team that speaks German on site, not a support ticket routed through three time zones. Bodor is not just selling cutting machines in Hannover. It is selling an end-to-end manufacturing workflow where the cutting, the sheet handling, the bending, the welding, and the service network all come from one vendor. The individual machines will eventually become comparable to competitors on spec sheets. The service network and local presence are harder to replicate. That is where the lock-in happens. European metal fabricators who commit to a full Bodor workflow line do not have to re-engineer their process stack when the next machine cycle rolls around. They stay in the system. And Bodor keeps the revenue.
More

Chery’s 2035 Gambit: Selling Cars Was Never the Endgame, and the Balance Sheet Knows It

(SeaPRwire) - The global auto industry has a dirty secret. Export volume is no longer a growth story. It is a margin trap dressed up as one. Every Chinese carmaker that shipped record units overseas in the past three years discovered the same wall. Tariffs bite. Local dealers squeeze. Brand loyalty never forms. Chery just told 2,000 users and partners at its 2026 International User Summit in Wuhu that it intends to escape that wall entirely. The company calls it Globalisation 3.0. Strip away the stage lighting and the plan is blunt. By 2035, Chery wants to stop being a traditional automaker and become what it describes as a high-tech extensive cluster built around AI. That is not a marketing flourish. That is an admission that shipping metal from Wuhu to 130 countries has a ceiling, and Chery hit the math early. The timing matters. The company turns 30 in 2027, and management clearly does not want the next decade priced like the last one. Here is what the official record actually says, and it deserves a careful read. The strategy rests on three moves. Restructure the organisation. Push the business focus forward. Integrate into local markets. The operating motto is "In somewhere, for somewhere, be somewhere." In plain terms, Chery is committing to local R&D, local manufacturing, and local procurement across a network spanning more than 130 countries and regions. The stated payoff is jobs, tax revenue, and durable trust with communities rather than pure export arithmetic. That is capital-heavy. Building plants and labs abroad burns cash for years before it defends a single point of margin. The summit also leaned hard on credibility assets. Partners from Spain, the United Kingdom, Türkiye, South Africa, Indonesia, Mexico, and Canada jointly launched "One Nature, One Future," covering five conservation themes from land to climate. The IUCN's Asia communications lead recounted a partnership running since 2024. UNICEF's representative in Viet Nam detailed children's education programmes Chery has funded across multiple countries, with the standard disclaimer that UNICEF endorses no company. This is not charity for its own sake. It is regulatory and reputational insurance, purchased in advance, in markets where Chinese manufacturers face rising political scrutiny. Now trace the commercial loop to its logical end. Chery claims more than 20 million users worldwide. The plan converts those users into co-creation partners, recruiting KOLs and KOCs to turn high-tech concepts into sellable products and fresh business opportunities. Read that as a distribution play. The company wants its user base to function as a low-cost R&D feedback loop and a marketing channel simultaneously, cutting both product development risk and customer acquisition cost. If it works, Chery stops competing on sticker price and starts competing on embedded local presence, which is exactly the moat Toyota and Volkswagen built over decades. If it fails, the company carries factories and staff in dozens of countries with export-grade margins that cannot service them. My read is simple. The automakers that survive the next decade will be the ones that stop behaving like exporters before politicians force them to, and Chery is one of the first to make that bet with real money on the table.
More
Every Robotics Company Hides the Same Secret. DEEP Robotics Just Wrote It Down. Business

Every Robotics Company Hides the Same Secret. DEEP Robotics Just Wrote It Down.

(SeaPRwire) - Every robotics company tells you they've solved the sim-to-real gap. Not one of them has. DEEP Robotics published five research advances on October 24, 2026, from Boston, bundled under the architecture name DEEPRobotics-Brain. The release spans world models, vision-language-action models, policy optimization, predictive memory, and real-world robot benchmarks. It is a serious technical effort. The academic collaborations point to that. But the core contradiction of embodied AI remains unresolved. You want a robot that adapts to environments it has never visited. The only way to teach it is through environments it has already been in. Every new capability demands more real-world data. Every new deployment scenario demands more. More always costs money. The research here is strong. The data treadmill is the story that matters. The five components are not interchangeable. Each one targets a specific failure mode in real-world robot operation. DR-WM-1.0 is the world model. It incorporates robot-terrain contact dynamics into action consequence prediction. The model can estimate friction, roughness, and stiffness before the robot commits to a path. It was trained on 2.58 million image-mask pairs and over 100,000 real-robot action clips. The architecture uses a dual-ControlNet approach, conditioning video generation on scene geometry and camera motion derived from simulated robot movement. During autoregressive rollouts, robot and controller states are carried forward. This maintains continuity with the underlying control loop. The application example is concrete. Picture a substation inspection robot operating after rain or snow. It can simulate a slippery shortcut and a longer route. It assesses the likelihood of slipping, unstable motion, or limited progress. It weighs those risks against travel efficiency. This is physical rehearsal, not just visual prediction. DR-VLA-2.0 handles navigation and manipulation. It introduces EgoLynx, a dataset of 10,000 hours of curated egocentric web video paired with 2,000 teleoperated robot navigation clips. The central mechanism is a domain-invariant scene representation called DISR. It combines semantic, spatial, and relational information. The model tracks what is present, where it is, and how scene elements relate to each other. A Mixture-of-Transformers framework brings together vision-language understanding, latent world modeling, and a flow-matching action expert. Human video supervises scene understanding and prediction. Robot demonstrations provide the action supervision for executable trajectories. On the held-out EgoLynx-Robot test split, DR-VLA improves the Quadruped Navigation Score by approximately 5%. It also reduces open-loop final heading error by 14.6%, each relative to the best competing result. The QNS metric combines safety, instruction compliance, comfort, and progress. The intended applications include socially compliant behaviors like waiting, bypassing obstacles, and yielding to pedestrians in shared spaces. For manipulation, the Atomic Motion Coordinate framework defines 13 interpretable motion atoms per arm. These cover positive and negative translations along three axes, positive and negative rotations about three axes, and a hold action. An initial training stage excludes visual inputs to align language with geometric motion. DR-APO is the policy optimization framework. DR-Agent handles predictive memory for the embodied agent. DR-Benchmark provides the data and evaluation platform for measuring real-world progress. Collaborations span MIT, UC San Diego, University of Illinois Urbana-Champaign, Tsinghua University, Zhejiang University, the Hong Kong University of Science and Technology, and the Beijing Institute of Technology. The commercial question is not whether these models work. The benchmark numbers show they do. The question is whether any company can afford the data collection cycle at deployment scale. Ten thousand hours of curated egocentric video sounds like a large corpus. It is not, relative to the full range of intersection patterns, pedestrian behaviors, and surface conditions a quadruped robot will encounter across thousands of residential communities and campuses. DR-Benchmark is the strategic play here. DEEP Robotics is not just publishing papers. It is building the evaluation infrastructure. If DR-Benchmark becomes the industry reference for measuring embodied AI progress, DEEP Robotics gains a structural advantage in attracting capital, partnerships, and talent. That is the real competitive moat. Models can be reproduced by well-funded competitors. Benchmarks are harder to replicate because they require sustained, large-scale real-world data collection. But the treadmill never stops. Every new benchmark exposes new performance gaps. Every new gap demands more real-world clips. The DR-APO and DR-Agent components aim to reduce this dependency. They still need real data to initialize and calibrate. The practical implication for anyone building a robot deployment program is straightforward. Evaluate whether your data acquisition pipeline can match the iteration speed of your model training pipeline. If it cannot, you will burn capital training models that cannot improve. The next batch of validation data simply has not arrived. The bottleneck in embodied AI is no longer the algorithm. It is the camera on the robot, the logging infrastructure behind it, and the calibration loop that turns raw clips into usable training signal. Whoever fixes that pipeline first will own the deployment layer. The five research pillars at DEEP Robotics are a credible technical foundation. They are not the answer to the data problem. They are the roadmap for asking better questions about it.
More
JUST’s $20M Buyback Upgrade Is a Buffer, Not an Engine Business

JUST’s $20M Buyback Upgrade Is a Buffer, Not an Engine

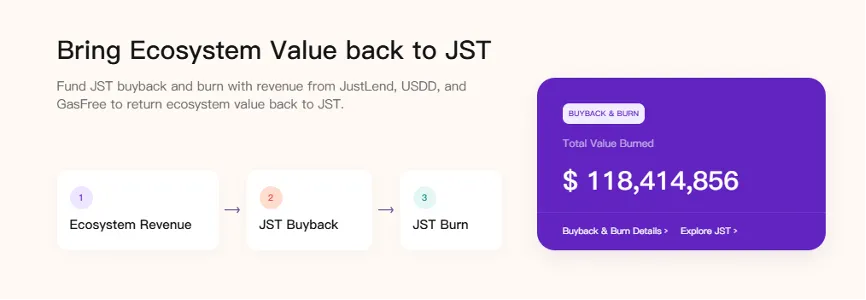
(SeaPRwire) - The JST token just got a $20.34 million lifeline, and the market should be skeptical. On October 24, 2026, JUST unveiled an upgraded Buyback and Burn mechanism. The press release sounds generous. It talks about $50 million in treasury reserves, a triple-pillar funding model, and phase-by-phase capital injections. Strip away the institutional language, and you're looking at a DeFi project trying to prove its token still has legs. The brand refresh landed one day earlier, on October 23. JUST now calls itself the flagship on-chain DeFi infrastructure on TRON. Phase 1 wrapped up on October 16. That's three weeks of rapid activity. The real question isn't how much money they're committing. It's whether the cash flows backing those commitments can survive a downturn. JUST has been operating on TRON for years. The token has gone through cycles. Now it's getting a mechanism overhaul. That's fine. But a mechanism overhaul is not the same as fundamental growth. The market has seen token buyback programs before. Many started with impressive numbers and faded when the underlying activity didn't keep up. JUST is no different. The mechanism is more granular this time. Granularity doesn't equal sustainability. The official narrative is straightforward. JUST expanded its funding sources from two product lines to three. JustLend and USDD were already feeding the buyback pool. Now GasFree revenue joins them. The announcement locks in a $50 million minimum reserve floor as a solvency backstop. All protocol funds above that floor go to JST buybacks. An initial $20.34 million was unlocked for deployment across four rounds starting in Q4 2026. That money comes from cumulative GasFree earnings and surplus reserves above the safety floor. JUST DAO handles everything on-chain. Every transaction is publicly verifiable. The protocol adopts a continuous buyback and periodic burn approach. Funded by 100% of revenue across all product lines, open-market buybacks adjust dynamically to market depth and liquidity. Accumulated tokens get burned on a regular schedule. JUST describes GasFree as the second growth engine for JST buyback funding after JustLend. The integration is scheduled to begin capital allocations in Q4 2026. The service enables single-asset fee settlement. Users pay transaction fees with the tokens they transfer. No need to hold TRX just to move funds. It currently supports gasless transfers for USDT and USDD. The protocol claims over $157.1 billion in cumulative stablecoin transfer volume across 9.14 million transactions. Over 500,000 unique addresses have used it. JUST also points to specific revenue sources. JustLend's sTRX staking and SBM programs generate income. USDD protocol revenue exceeds the $10 million threshold. The five structural pillars, the three revenue streams, the reserve floor, the surplus injection, and the on-chain governance form a coherent package. That's what the press release sells. The industry subtext tells a more complicated story. Those numbers behind GasFree need scrutiny. As of October 23, 2026, it claims $157.1 billion in cumulative transfer volume across 9.14 million transactions. Those metrics look impressive on paper. But cumulative transfer volume doesn't equal revenue. It measures throughput, not profit. The press release omits any breakdown of GasFree's actual revenue margins or unit economics. How much does GasFree earn per transaction? What's the margin after covering infrastructure and liquidity costs? The answer isn't in the release. JustLend's sTRX staking and SBM revenue are cited. USDD protocol revenue is said to exceed the $10 million threshold. Yet the actual dollar contribution from each stream isn't quantified. A three-pillar funding model only holds if each pillar generates real, recurring cash. If GasFree revenue is thin, the whole buyback engine loses traction fast. The $50 million reserve floor is a safety net. Safety nets don't print tokens or drive adoption. The $20.34 million surplus injection, split across four rounds, looks like a buffer designed to smooth gaps if organic revenue falls short. If TRON's overall network activity cools, all three product lines face correlated headwinds. GasFree transfers drop. JustLend staking volumes shrink. USDD yields compress. Diversification across product lines sounds like diversification. In reality, it's vertical diversification on a single rail. The governance consolidation under JUST DAO, formerly JustLend DAO, streamlines execution but concentrates risk. Every transaction can be verified on-chain. Key financial figures get disclosed regularly. Transparency is genuine. But transparency doesn't fix fundamental revenue weaknesses. One chain, one framework, one token. That's the structural reality. The blunt truth is that JST's value-accrual story depends entirely on sustained on-chain activity across TRON's DeFi sector. The buyback mechanism is mechanically sound. The math checks out on paper. Phase 1 ran smoothly. The 5th buyback and burn wrapped up without issues. Phase 2 kicks off with a bigger war chest and more funding sources. But $20.34 million in one-time surplus doesn't build a deflationary engine. It primes one. The organic revenue from GasFree, JustLend, and USDD has to carry the load after that surplus runs dry. If users start using competing gasless solutions, GasFree revenue drops. If lending demand on TRON contracts, JustLend shrinks. If USDD yields fall below competitors, the token loses traction. JUST controls the mechanism. It doesn't control the market. There's also a structural risk in the timing. The surplus funds get deployed across four rounds starting in Q4 2026. If the market is in a downturn during that window, those buybacks hit at weak liquidity. If the market rallies, the buybacks might look insufficient. Either way, the outcome depends on external forces. JustLend needs sustained staking participation. GasFree needs continued user adoption and transaction volume growth. USDD needs yield competitiveness. All three have to perform simultaneously. That's not a strategy. That's a hope. Watch the next two buyback rounds in Q4 2026 closely. If volume stays consistent, the thesis holds. If it drops, the surplus was just a delayed confession.
More
LUXEED’s 60-Market Bet: A Structural Reconfiguration of Luxury Mobility Business

LUXEED’s 60-Market Bet: A Structural Reconfiguration of Luxury Mobility

(SeaPRwire) - The automotive sector is drowning in the term "luxury," yet few brands attempt to redefine the underlying value proposition as aggressively as LUXEED did on October 21, 2026. Held at Shenshan Intelligent Valley in Wuhu, this global debut was not merely a product reveal. It was a strategic assertion that intelligence, not material opulence, constitutes the new luxury currency. The event showcased two distinct vehicles: the LLounge MPV and the Stormax SUV. This dual-launch strategy signals a rejection of the monolithic branding typical of legacy OEMs. Instead, LUXEED splits its consumer base into passenger-centric and driver-centric segments from day one. The claim of "Extreme Driving Pleasure, Beyond-Class Enjoyment, and Ultimate Intelligence" is bold. It positions the brand against established German and Japanese rivals who still rely on heritage and badge engineering for sales volume. The core tension here is simple. Can a new entrant sell high-ticket hardware in a market saturated with established perceptions? The official narrative outlines a clear geographic and temporal roadmap. LUXEED plans to enter 18 markets in 2026–2027. Expansion reaches 36 markets by 2028–2029. The target exceeds 60 markets by 2030. Initial focus areas include the UAE, Thailand, and Indonesia. This is not a Western-first strategy. It is a global south and middle east priority approach. The brand explicitly links "consistent global product standards" with "localized validation." This hybrid model attempts to mitigate the common failure mode of international expansion where local tuning degrades core engineering integrity. The value proposition, "I DRIVE, YOU ENJOY," maps directly to the two hardware units. The Stormax caters to the driver. The LLounge caters to the occupant. This bifurcation reduces marketing friction. It allows the brand to sell comfort to families and performance to enthusiasts under a single intelligent umbrella. Behind these public-facing metrics lies a specific commercial logic. Entering 60 markets within four years requires significant capital expenditure. It demands localized service networks and parts distribution infrastructure. The focus on "seamless intelligence" suggests that the software stack will be a primary retention tool, not just the hardware. By targeting emerging economies like Thailand and Indonesia alongside wealthy nations like the UAE, LUXEED is hedging its market risk. It avoids the brutal price wars in mature European and North American markets where legacy brands hold service lock-in. The emphasis on "aspirational mobility" indicates a premium pricing tier. The industry subtext is clear. LUXEED is not competing on volume initially. It is competing on perceived technological superiority. The "intelligent luxury" label is the shield. It prevents direct comparison with traditional luxury sedans by changing the category definition entirely. This expansion will reshuffle the premium EV hierarchy in Asia and the Middle East by 2030. Legacy brands will face a new competitor that does not carry the baggage of fossil fuel history. They cannot be accused of false advertising regarding emissions. The "enlightened intelligence" tagline is a direct counter to the status quo. The risk is execution. Can LUXEED maintain consistent quality across 60 diverse regulatory environments? The answer remains unproven. The strategic window is narrow. If the initial 18 markets do not generate sufficient brand equity by 2027, the subsequent expansion to 36 and then 60 markets becomes a logistical nightmare. The endgame is not just selling cars. It is owning the definition of intelligent luxury in the next decade.
More
One Target, Three Weapons: Immatics Just Made the Boldest PRAME Bet in Oncology — and ESMO 2026 Was Its Proof of Concept Business

One Target, Three Weapons: Immatics Just Made the Boldest PRAME Bet in Oncology — and ESMO 2026 Was Its Proof of Concept

(SeaPRwire) - Solid tumor immunotherapy has a dirty secret. For all the billions poured into checkpoint inhibitors, the patients who fail them — and there are many — hit a therapeutic wall fast. The anxiety hanging over ESMO 2026 in Madrid was precisely this: what comes after ICI failure in melanoma, ovarian cancer, and other hard-to-treat solid tumors? Immatics walked into that anxiety with an unusually confident answer. Not one drug. Not two. Three distinct clinical-stage programs, all aimed at a single intracellular target, PRAME. That is either disciplined portfolio design or expensive redundancy, and the new data from Dirk Schadendorf and Antonia Busse's oral presentations begin to tell us which. Start with the facts, because they are genuinely not trivial. IMA402, the company's off-the-shelf TCR bispecific, was tested in 126 heavily pretreated patients — median three prior lines of therapy, median target lesion sum of 7.4 cm. This is not a cherry-picked, biomarker-lucky cohort. Within the recommended Phase 2 dose range of 10 to 45 mg, the confirmed objective response rate was 25% overall, climbing to 32% in PRAME-high patients across all indications and 32% specifically in melanoma. The numbers that matter more are the durability figures. In PRAME-high melanoma — where every single patient had already failed immune checkpoint inhibitors, a median of two prior ICI regimens — median duration of response hit 12.5 months, the longest ongoing response exceeded two years, and 91% of patients were alive at one year. Compare that to 60% one-year survival in patients dosed below the RP2D range, and the dose-response signal looks real rather than statistical noise. Safety held up too: transient lymphopenia and low-grade CRS, zero ICANS cases, no drug-related Grade 5 events, and no additive toxicity when combined with an ICI. Meanwhile, IMA203CD8, the PRAME-directed cell therapy, posted a 55% confirmed ORR with an 8.4-month median DOR in heavily pretreated gynecologic cancers at clinically relevant doses. Add the exploratory poster on anzu-cel's Phase 1b melanoma cohort, and the "three complementary approaches" framing from CMO Cedrik Britten stops sounding like investor-relations boilerplate. Now the commercial logic, which is where this gets interesting. Bispecifics and cell therapies are not redundant assets — they occupy different slots in the treatment algorithm. IMA402 is an off-the-shelf infusion, scalable, combinable with ICIs in melanoma and gynecologic cancers, and even stackable with Immatics' own MAGEA4/8 bispecific IMA401 in lung cancer, with first data expected in 2027. IMA203CD8 plays the deeper-response, tumor-agnostic card for patients who can tolerate cell therapy logistics. The quiet strategic weapon here is the liquid biopsy-based PRAME testing. Rapid, sensitive patient selection is what turns a 25% unselected response rate into a 32% enriched one — and potentially a fast-to-market regulatory path in PRAME-high melanoma. That companion-diagnostic flywheel is exactly what separated winners from also-rans in the HER2 and PD-L1 eras. The end-game, if the data hold in Phase 2, is a company that doesn't just sell a drug but owns the entire diagnostic-to-treatment loop for a target expressed across a wide swath of solid tumors. The risk is equally clear: PRAME-high enrichment must keep outperforming, or the three-program architecture becomes three parallel cash burns. Watch the ovarian expansion cohorts and the 2027 lung combination readout — those will decide whether Immatics built a franchise or just a very elegant hedge.
More
Soft Power 2.0: How Yangguang News Turned Tang Poetry Into a 6-Million-View Global Youth Recruitment Engine Business

Soft Power 2.0: How Yangguang News Turned Tang Poetry Into a 6-Million-View Global Youth Recruitment Engine

(SeaPRwire) - Chinese cultural campaigns have always suffered from the same structural problem. You put on a costume, play guqin music, and broadcast poetry to the world. Nobody watches. Traditional cultural export runs into a wall of irony and disengagement among foreign youth. This campaign is different because it hands the tools directly to the audience instead of asking them to watch politely. Yangguang News launched "Me, Tang Poetry, and AI" in Xi'an back in January 2026. Thirty-one co-organizing institutions signed on. One hundred and twenty-six schools responded with submissions. The campaign reached over 100 short video entries already. Distribution runs through TikTok and YouTube rather than state media channels. More than 20 individual works crossed 100,000 views each overseas. Total overseas accumulation sits near 6 million views as of September 2026. A student named Zhong Yi used AI to render the landscapes of Li Bai's Hard Is the Way to Shu. Two other students, Xu Zihe and Yang Yifan, tackled Cen Shen's frontier poems. Xi'an itself, designated as a City of Tang Poetry back in August 2025, provides the institutional and cultural backbone. The follow-up creative theme, When Tang Poetry Meets the World, pushes participants to create virtual characters from their own cultures reading Tang poems. AI disclosure is mandatory on every submission. The deadline sits at September 20, 2026. The real play here is not content distribution. It is behavioral architecture. Every piece of official cultural messaging traditionally treats the foreign audience as a receiving vessel. This campaign inverts that entirely. Young creators abroad become the actual producers. They build the visuals. They write the voice-overs. They translate the poems themselves with AI assistance. The organization provides the framework, the prompts, and the platforms. The audience does the creative labor. That is a significant shift in how cultural soft power operates in an algorithm-driven attention economy. The campaign structure rewards participation over consumption. It turns viewers into collaborators without them realizing they are participating in a curated cultural exchange operation. The 6 million overseas views are engagement metrics, yes. But they are also evidence that the model works. Traditional cultural diplomacy relied on institutions broadcasting outward. This campaign proves that distribution platform choice determines reach more than content quality ever will. TikTok and YouTube bypass the gatekeepers entirely. Foreign youth discover Tang poetry because the algorithm surfaces it alongside other creative content, not because a cultural ministry posted it. The commercial landscape for cultural export is shifting toward this participatory model. Organizations that design for creator involvement will capture attention. Those still relying on top-down broadcasting will watch their relevance fade.
More
The Liquor Industry’s Growth Trap: Why Quality Isn’t Enough Business

The Liquor Industry’s Growth Trap: Why Quality Isn’t Enough

(SeaPRwire) - The global spirits and wine sector is suffering from a chronic momentum deficit. It is not a product quality issue. It is not a branding visibility issue. The 30 representative brands included in the recent World Famous Liquor Brands Sustainability Index Report all check those boxes. The real problem is stagnation. These companies have built solid foundations. Now, they are struggling to turn those static assets into dynamic business results. The industry is stuck in a loop of maintaining heritage without expanding market capture. The data from the report, released on October 17 at the 2026 Chishui River Forum, paints a clear picture. Xinhua Index Research Institute analyzed 30 brands and found that quality and visibility are strong. However, business momentum lags significantly. The report sorts these brands into four tiers: Leading, Resonating, Established, and Emerging. Only 20% of the sample sits in the Leading tier. These top players do not win because of a single sharp edge. They win through years of accumulated strength in regional ecosystems and brewing traditions. Their leadership relies on effective synergies between brand visibility and market recognition. The rest of the industry lacks this depth. A distinct split is emerging between distilled spirits and fermented beverages. Distilled spirits lean heavily on terroir and legally protected production-area designations. They build competitive moats around history and traditional craftsmanship. Fermented beverages take a different approach. They focus on building global operating systems. Their strength lies in translating international market presence into tangible results. While their overall development levels are converging, their underlying engines of growth differ radically. For many in the spirits sector, especially in China, the challenge is acute. The industry has reached maturity in brand positioning and waste recovery. Yet, it fails in international market conversion. It struggles to keep intangible cultural heritage alive in commercial practice. The next step is not about proving quality. It is about converting that accumulated cultural and asset strength into tangible development outcomes.
More
Why Moutai Is Selling the World, Not Just a Bottle Business

Why Moutai Is Selling the World, Not Just a Bottle

(SeaPRwire) - There is a specific type of panic in the global beverage sector right now. It stems from the fact that premium spirits are no longer just products; they are geopolitical currency. The 2026 Chishui River Forum, held October 16-18 in Maotai Town, Guizhou, exposed this reality. Organized by Xinhua and China Moutai, the event was not a marketing stunt. It was a declaration of intent. Moutai is trying to standardize the world’s view of terroir. The official release cites a strong local foundation. Ao Hong, Director-General of the Guizhou Provincial Department of Industry and Information Technology, stated clearly that Moutai cannot be produced anywhere else but Maotai Town. This is the core value proposition. Chen Hua, Chairman of China Moutai Group, argues that production regions are the ecological foundation of the liquor industry. He claims these regions are the source of quality. This is not just poetry. It is a legal and strategic framework. However, the subtext is about market control. China’s baijiu industry is currently undergoing a profound adjustment. The release admits that evolving consumer demand and inventory restructuring are shared challenges. Moutai is using this forum to build consensus. They launched the *Chishui River Valley: China's Sauce-Aroma Baijiu* Regional Brand Think Tank. They also launched the China Brands Go Global initiative. Six brands, including Moutai, were classified as “Leading” in the *World Famous Liquor Brands Sustainability Index Report (2026)*. The move is strategic. Moutai invited 16 domestic and international liquor companies. They are building consensus around six priorities. These include cultural heritage, green development, and technological innovation. Li Xiaojie, former Vice Minister of Culture, called for bringing intangible cultural heritage brewing techniques to life. This is not just about preserving tradition. It is about creating a new standard for luxury goods. If Moutai defines the standard, they control the narrative. I see this as a reshuffling of global market share. The west has dominated premium spirits for decades. That is ending. Moutai is moving from a local powerhouse to a global rule-maker. The forum was a pressure point. It forces competitors to engage on Moutai’s terms. The industry is moving toward a bifurcated landscape. Some will align with the new terroir-based standards. Others will be left behind.
More

Junshi’s First Phase 3 Dosing of JS203 Is Really a Bet on Rewriting the R/R DLBCL Playbook

(SeaPRwire) - Relapsed or refractory diffuse large B-cell lymphoma is where good intentions in oncology go to get humbled. Patients who fail first-line therapy face a median overall survival of barely over a year and a five-year survival rate hovering around 30%, based on retrospective Asian data. The market has been waiting for something that moves the needle without the logistical burden of CAR-T manufacturing. That anxiety is exactly the opening Junshi Biosciences is walking through. On October 23, 2026, the Shanghai-based company confirmed first patient dosing in the JS203-003-III-DLBCL study, a randomized, open-label, multicenter Phase 3 trial. This is the first registrational study for JS203, its self-developed recombinant humanized anti-CD20/CD3 bispecific antibody. The trial pits JS203 plus chemotherapy against the incumbent standard of rituximab plus chemotherapy in R/R DLBCL patients. Rituximab has been the backbone of B-cell lymphoma care for two decades. Taking it head-on in a head-to-head registrational design is not a cautious move. It is a declaration. The facts deserve a careful reading. The study, led by Professor Yuqin Song of Beijing Cancer Hospital, plans to enroll 282 subjects with overall survival as the primary endpoint. OS, not progression-free survival or response rate. That is the hardest bar in oncology and the one regulators and payers actually respect. The Phase 1 foundation is genuinely encouraging. At the recommended Phase 2 dose with step-up dosing to 30 mg, JS203 monotherapy delivered an objective response rate of 72.4% in CD20-positive relapsed or refractory B-cell non-Hodgkin lymphoma. Within the DLBCL subgroup specifically, ORR reached 69.7% and complete response rate hit 39.4%, with durable remissions observed. The safety profile is arguably the more interesting number. Cytokine release syndrome occurred in only 27.3% of patients, and there were zero cases of ICANS, the neurotoxicity that has plagued T-cell engagers and complicated community hospital adoption of competitors like glofitamab and epcoritamab. Meanwhile the addressable problem keeps growing. DLBCL accounts for roughly 40% of adult non-Hodgkin lymphoma cases in China, with about 45,000 new diagnoses annually per GLOBOCAN 2022, and incidence is creeping upward. Now the commercial logic. Junshi already proved with toripalimab, its PD-1 antibody approved across more than 50 countries including the US and Europe, that it can execute global regulatory strategy from a Chinese cost base. JS203 fits the same playbook. Bispecific antibodies are off-the-shelf, meaning no vein-to-vein wait, no manufacturing slots, no six-figure per-patient production economics. If the Phase 3 confirms the Phase 1 signal with a clean CRS and zero-ICANS profile, Junshi owns a product that community oncologists can actually administer, which is where the volume lives in both China and emerging markets. The combination-with-chemotherapy design also matters. It positions JS203 as an upgrade to an existing, reimbursed workflow rather than a wholesale treatment disruption, lowering adoption friction. The end-game here is straightforward. If JS203 beats rituximab on overall survival in this 282-patient trial, the R/R DLBCL treatment algorithm gets rewritten around a Chinese-originated bispecific, and Junshi converts a domestic pipeline asset into a global franchise. Watch the enrollment velocity. That single metric will tell you whether investigators believe the early data, and right now the smart money says they do.
More
Moganshan Truth or PR Hype? Deconstructing SOUEAST’s Bold Hybrid Ambition Business

Moganshan Truth or PR Hype? Deconstructing SOUEAST’s Bold Hybrid Ambition

(SeaPRwire) - Polished marketing narratives of family SUVs conquering rugged mountain slopes hide a much harsher operational reality. When SOUEAST showcased the S08 DM to a global audience in Moganshan on October 21, 2026, the event was not a casual drive. It was a high-stakes demonstration of powertrain engineering under intense commercial pressure. The global automotive market is trapped in a brutal price war. Every kilowatt of hybrid power is squeezed for cost efficiency. To blend a 255 kW hybrid system with multi-configurable interior comfort is a bold gamble. It demands tight component integration. Most traditional manufacturers still struggle with this consistency. The 2026 SOUEAST Global Technology Experience Day served as a critical proving ground. It exposed the gap between promotional gloss and mechanical grit for attendees from over 10 countries. The official release highlights the C-DM Hybrid System, pairing a 1.5TD hybrid-dedicated engine with a stepless DHT transmission. It boasts a combined output of 255 kW and a massive 525 N.m of torque. On paper, these figures represent a competitive push into the global hybrid segment, promising brisk acceleration for a large seven-seater. In reality, the subtext involves immense thermal and mechanical stress on the transmission during consecutive curves and sudden accelerations. The undulating slopes of Moganshan are not scenic backdrops. They are physical obstacles testing thermal management limits under heavy load. The claim of a resilient chassis absorbing gravel impacts sounds reassuring. The subtext reveals a highly competitive sourcing market for suspension parts. Suppliers face constant pressure to lower prices. This often leads to thinner tolerances in dampers and bushings. The reported smooth braking and quiet cabin experience are impressive. They represent careful acoustic engineering and insulation choices. Yet, the long-term durability of these systems under heavy loads remains the unspoken question. The industry watches to see if these parts can withstand years of real-world abuse without degrading performance or causing safety concerns. The official narrative focuses heavily on family utility, showcasing a 4,810 mm body with a 2,820 mm wheelbase. The 2+3+2 seven-seat layout offers up to 32 configurations, including specialized modes like the Home Bed and Travel Pallet. The event held a "Fun Loading Challenge," stuffing a giant 3.5-meter plush giraffe and a portable football goal into the cabin. This highlights spatial flexibility and aims to appeal to active lifestyles. The subtext points to the rapid commoditization of smart cabin tech. Features like the 15.6-inch central screen, intelligent voice interaction, and 3.3 kW V2L external discharge are now standard checklists on spec sheets. The real challenge lies in software stability and processing power for these large displays. A laggy or glitchy interface can quickly turn a premium feature into a daily frustration for drivers. Furthermore, the physical utility of 32 seat configurations is questionable in daily urban commutes. Constantly adjusting seats while navigating traffic is a safety hazard. The challenge for SOUEAST is whether these complex electronic and mechanical modes are genuinely useful. Or if they are merely marketing gimmicks designed to win on specification sheets against rivals. The supply chain for multi-mode seat mechanisms, large displays, and high-voltage V2L systems is highly fragmented. Navigating this complex network is a massive logistical hurdle for any expanding brand. The harsh truth of the global automotive supply chain is that it rarely rewards complexity. It only rewards massive vertical integration and strict quality control. SOUEAST's ambitious push with the S08 DM relies on a sprawling network of tier-one and tier-two suppliers. These partners deliver the 1.5TD engine, the DHT transmission, and the complex multi-mode seating systems. In the current economic climate, these suppliers face rising raw material costs and shrinking margins. The risk of component quality variance increases when a brand attempts to scale too rapidly across diverse global markets. If the brand cannot secure long-term, stable supply agreements for these complex hybrid and interior components, the S08 DM will transition from a highly praised test vehicle to an expensive maintenance liability. It will become a nightmare for customer service departments and brand reputation. The ultimate test for global buyers is not the initial drive on scenic routes. It is the long-term reliability of the underlying parts network and the responsiveness of after-sales support. Stakeholders should look past the launch events and PR spectacles. They must audit the actual component sourcing channels and supplier financial health before committing capital or inventory.
More
They Killed the Pump. Then They Killed the Tank. Now They’re Redrawing the Rules. Business

They Killed the Pump. Then They Killed the Tank. Now They’re Redrawing the Rules.

(SeaPRwire) - Glacier Fresh launched the U03 in early October 2026 and it's already cracking the top of search results within weeks. A reverse osmosis unit that needs no plug in the wall. That's the headline. But here's what the press release doesn't say: this isn't a minor iteration. This is a product philosophy that treats the traditional RO box as an embarrassing artifact of an era when hardware engineers didn't think twice about bolting a compressor into a humid cabinet. If your kitchen cabinet can't host a vacuum cleaner, a space heater, and a water pump all competing for one outlet, the problem was never the kitchen. The specs are clean and dehydrated. U03 runs on municipal tap water pressure, zero external electricity. The integrated "TankInside" design eliminates the bulky external storage tank. This single move reclaims up to 70% of the under-sink footprint. Installation uses quick-connect plumbing fittings. No electrical modifications. No drilling. No plumber call. The filtration stack is multi-stage and claims removal of up to 99.99% of contaminants including heavy metals, PFAS/PFOA compounds, residual chlorine, microplastics, bacteria, and odor-causing substances. A built-in high-efficiency tank delivers high flow rate on demand. CEO Magic Wu framed the pain point in blunt terms. Previous users lived in apartments where drilling wasn't permitted and space was tight. The U03 exists because that constraint was ignored by competitors for years. The product is built on natural water pressure from the treatment plant's tap line. It removes electrical safety hazards in a hot, humid environment. It operates silently. And if the grid goes down, the water keeps flowing. The press release notes this specifically for emergency scenarios like sudden power outages. What's actually happening in the RO market is a segment collapse that's being dressed up as a product launch. Every manufacturer sold the same story: bigger tanks, faster flow rates, smarter displays, more filter stages. Nobody asked whether the user needed a high-pressure pump in the first place. The pump architecture created a whole supply chain around it. Pump makers, tank makers, power connector manufacturers, installation services. Now one company says none of that matters, and the market has to figure out who pays the bill. The installed base of traditional RO systems is massive. Most are still running on pump-driven designs with external tanks. Those customers face a replacement cycle in 3 to 5 years. If Glacier Fresh's no-power paradigm catches, the entire component supply chain gets reshaped overnight. Pump manufacturers lose volume. Tank manufacturers lose volume. Plumber service networks lose recurring revenue. The companies that survive are the ones who can source membranes and filtration media without being locked into the old pump-tanked architecture. This isn't about one product. It's about which supply chain wins the next decade. The next RO wars won't be about which brand filters better. They'll be about who gets rid of the pump first.
More

Crossing the Floor: 3 E Network’s $5 Million Insider Bailout and the Governance Red Flag Nobody Wants to Touch

(SeaPRwire) - A 2-for-1 reverse split executed on October 23, 2026, followed immediately by a private placement where the CEO's own offshore entity absorbs the largest tranche. 3 E Network Technology Group Limited (Nasdaq: MASK) is not running a growth engine. It is running a survival sequence. The company raised exactly $5,000,000 through a private placement of 2,751,789 post-consolidation Class A ordinary shares at approximately US$1.8170 per share. The single largest buyer was 3E NETWORK TECHNOLOGY PTE. LTD., a Singapore-incorporated entity controlled by Dr. Tingjun Yang, the company's chief executive officer and sitting director. That entity subscribed for 1,157,823 shares at $2,103,764.12, representing roughly 42 percent of the total deal. Six individual purchasers each bought 265,661 shares for $482,705.98, completing the raise. The Audit Committee reviewed the related-party transaction. The full board of directors gave final approval. When a sitting CEO's foreign entity is the dominant buyer in a capital raise, the audit committee is not exercising independent oversight. It is providing procedural cover for insider access to company equity at market-priced terms. The press release frames this transaction with textbook precision. The shares will be issued under a Section 4(a)(2) exemption and Rule 506(b) of Regulation D of the Securities Act of 1933. No registration is required. Each purchaser has represented accredited investor status. The shares will not be issued before October 30, the Nasdaq Market Effective Date when the consolidated Class A ordinary shares begin trading. The company intends to deploy proceeds toward general working capital, ordinary course business operations, and other lawful corporate purposes. The release positions 3 E Network as a B2B IT solutions provider with ambitions to become a next-generation AI infrastructure provider. Two business portfolios are cited: data center operation services and software development. This framing language is standard corporate marketing scaffolding. The "AI infrastructure" positioning and references to an "AI and energy symbiosis" industry consensus exist to sustain a narrative of strategic relevance. But the actual capital markets are pricing this equity at a level that makes the narrative irrelevant. The market does not care about the infrastructure story. The market cares about whether the stock can clear the Nasdaq minimum bid threshold. The reverse split is the most revealing data point in the entire announcement. Companies that execute a 2-for-1 consolidation are almost always defending against the Nasdaq minimum bid price rule. A stock trading persistently below the compliance floor triggers a deficiency notice. The company consolidates shares to inflate the per-share price above that threshold. This is administrative triage, not strategic positioning. The company is simultaneously selling consolidated shares to its own CEO's entity at approximately $1.82 per share on a post-consolidation basis. A genuine strategic investor at meaningful scale would not wait for a reverse split to restructure the share price. They would negotiate a pre-money valuation directly. Instead, 3 E Network is accepting whatever insider capital is available at whatever price the public market currently establishes. The six identical individual purchaser tranches of 265,661 shares each look like a coordinated syndicate structured to satisfy the Rule 506(b) accredited investor requirements. Alternatively, they could represent a single actor splitting allocations across multiple accounts. The press release provides no clarification. Omission of beneficial ownership detail in a related-party capital raise is not a neutral choice. It is a signal. The board members who approved this transaction without publicly disclosing the identities of the six individual purchasers are exposed to proxy challenge. The Audit Committee must release a complete beneficial ownership table covering all seven purchasers. Dr. Yang should recuse himself from any capital allocation decision involving the proceeds of this raise. The company requires an independent governance review before it can execute any further capital market event. Small-cap holders of MASK should ask one question and nothing more: is the CEO subscribing to his own company's equity because he has genuine conviction in the business model, or because he is the only counterparty willing to buy it? Five million dollars in working capital will not transform a data center operator into a next-generation AI infrastructure provider. A reverse split will not manufacture organic demand for equity that the broader market has already rejected. This is not a corporate announcement. It is a liquidity event wearing the costume of a strategic transaction.
More

Tokyo Lifestyle’s Chatswood Move: A Calculated Bet on Sydney’s Nostalgia Economy

(SeaPRwire) - Most retail expansions are exercises in vanity. Executives love the map pins. They love the ribbon-cutting photo ops. They do not love the arithmetic of square meters per dollar. Tokyo Lifestyle’s decision to anchor its third Australian outpost at Westfield Chatswood is not vanity. It is a cold, hard look at where discretionary spending actually lives. The company claims this milestone strengthens its presence. I see a pivot toward high-density consumer capture. The location is not just "convenient." It is a chokepoint. With over 601,000 people in the immediate trade area, this is not a test market. It is a saturation play. The press release talks about "brand visibility." I talk about cash flow velocity. The official narrative is smooth. They cite the train station, the bus interchange, and the Pacific Highway. They mention the 147 square meter footprint. They list the mix: Japanese beauty, Korean skincare, collectible cards, plush toys, and snacks. It sounds like a curated lifestyle destination. The industry subtext is different. This is a value trap for younger demographics. By combining premium Japanese goods with "trendy toys" like Pokémon cards and BE@RBRICK, they are selling aspiration at mid-range price points. The "authenticity" is the hook. The "value-conscious purchasing" is the conversion mechanism. The Haymarket store targets tourists. Melrose Park targets locals. Chatswood targets the commuter class with disposable income. It is a segmented funnel designed to feed a single revenue stream. Geographic diversification is a standard talking point for Nasdaq-listed foreign companies. But look at the numbers. Revenue from directly operated physical stores rose by 15.7% year over year for the fiscal year ended March 31, 2026. More importantly, revenue from outside Japan jumped from 29.5% to 47.1% of total revenue. This is the real story. They are no longer a Japanese company with a foreign presence. They are a global retailer with a Japanese identity. The shift in the geographic revenue base is the key to their valuation. By signing a five-year lease in Chatswood, they are locking in capital efficiency. They are betting that the Australian consumer will treat Japanese lifestyle goods as a necessity, not a luxury. The five-year commitment signals that they do not expect to need to renegotiate or exit. They expect compounding returns. The market share reshuffling will not be dramatic. It will be incremental. Every new store tightens the net in Sydney. The competition from local discounters will not follow. They cannot match the "authentic Japanese supplier" angle easily. Tokyo Lifestyle is leveraging cultural capital. They are selling a story, not just items. The Chatswood store is the keystone in the local arch. If this location hits its revenue targets, the next move will be Brisbane or Perth. The real estate logic is sound. The consumer psychology is sound. The only risk is over-saturation. But for now, this is a solid, defensible position in the global retail landscape.
More
0.4 mm, Three Guides, and the Real Cost of Fixing PCB Design After the Gerber Files Are Already Sent Business

0.4 mm, Three Guides, and the Real Cost of Fixing PCB Design After the Gerber Files Are Already Sent

(SeaPRwire) - 0.4 mm pitch BGA packages. That number alone tells you where the pressure point is. Every compact industrial controller, every high-density power module, every next-gen telecom switch converges on the same routing density. And every one of them depends on a supply chain that still struggles to keep up with the geometric demands. WellerPCB published three engineering guides on October 23, 2026 — one on CTI-based material selection, one on fine-pitch BGA design, and one on high-voltage clearance and creepage. Strip the PR polish, and the message is blunt. The Shenzhen-based manufacturer is acknowledging that layout engineers routinely make pad-geometry, escape-routing, and insulation-spacing decisions that will fail at the fabrication stage. Solder bridging. Mask registration errors. Creepage distance miscalculations. These aren't edge cases anymore. They're the default failure pattern when teams push pitch density without getting the factory involved until the file handoff. Let's get into the specifics. The CTI guide references material classifications tied to industrial electronics and power systems, where creepage distance requirements are governed by environmental contamination levels and applicable safety standards. The fine-pitch guide explicitly names HDI technology, laser-drilled microvias, and filled via-in-pad structures as potential requirements for 0.4 mm pitch components — all of which carry significant cost premiums over standard through-hole processes. The high-voltage guide catalogs isolation slots and additional insulation barriers as design necessities under high-transient-overvoltage scenarios. None of these details come with published price tags. They should. A filled via-in-pad structure adds material overhead and process complexity. HDI routing requires multi-layer stacking with alignment tolerances measured in micrometers. Isolation slots consume board real estate and can weaken mechanical integrity under vibration loads. WellerPCB positions these guides as early-warning tools to "identify potential reliability, yield, and cost issues earlier in the design process." That phrasing is doing real work. It frames the problem correctly: fabrication complexity and assembly costs are inflating at the point where engineers hand off Gerber files, not where they place the first component on the schematic. The gap between a clean schematic and a manufacturable board keeps widening. Design teams that skip manufacturer engagement at the schematic stage absorb yield losses, respin cycles, and BOM cost overruns downstream. Each of those three guides maps a different failure vector — material selection, routing density, and electrical insulation — but they all point to the same structural flaw in how most teams sequence their design workflow. The endgame is consolidation, and it's already in motion. Smaller PCB shops without the process engineering depth to handle 0.4 mm pitch routing, microvia fill, and rigorous CTI qualification will lose bids to vertically integrated manufacturers who bundle design consultation, DFM evaluation, and assembly under one roof. WellerPCB's play is transparent. Position as the engineering partner before production, not just the factory that prints your files at a fixed margin. Every mid-market design house that treats PCB fabrication as a post-layout afterthought will see margins compressed by respin costs and yield leakage. The hardware vendors who survive the next cycle will be the ones who build design-manufacturing feedback loops directly into their development process. The cost of that integration is a fraction of what a mid-production board revision costs. But that's an engineering discipline decision, not a marketing exercise. And right now, most teams are still making it the hard way.
More