Ten Thousand Machines In, the Laser Business Stops Being About Lasers

(SeaPRwire) -By: Oliver Hawthorne Here is the anxiety nobody in the fiber laser business says out loud. Machines are becoming commodities. Power ratings converge. Cutting heads converge. Even prices converge. So when Bodor Laser announced on September 29, 2026, from Jinan, China, that its 10,000th machine of the year had rolled off the production line, the number itself was not the story. Ten thousand units in nine months is a volume figure any CFO can print. The real question is what breaks at that scale. Ask anyone who has run a fabrication shop. One unreliable machine costs an afternoon. Ten thousand unreliable machines cost a reputation across continents. The industry has watched Chinese laser makers win on price for a decade. Now it is watching to see whether any of them can win on uptime. That is a far harder contest, and Bodor has just volunteered for it at industrial scale. The facts deserve a careful read. Bodor states that each machine follows defined production and inspection procedures before delivery. It explicitly acknowledges that higher volumes strain material preparation, scheduling, assembly, testing and inspection. This is an unusual admission for a press release. Most manufacturers celebrate output and hide the operational tax that output imposes. Bodor instead frames the milestone as a coordination test across production, quality control, delivery and customer support. It also ties the number to service. Its service system covers installation, technical support, troubleshooting and ongoing maintenance. The release notes that a growing international installed base creates more diverse service requirements across markets, configurations and applications. Translation: every machine sold abroad is a long-term liability unless the support network scales with it. The company says it is expanding service capacity alongside manufacturing. No specific service center counts or response-time metrics are disclosed. That gap matters, and buyers should ask about it. Now follow the commercial loop. Laser cutting equipment earns its margin twice. First at the sale. Then across years of operation, where downtime kills customer trust and parts plus service generate recurring revenue. Bodor's own framing concedes this: manufacturing determines how equipment is produced, service supports it once it enters operation, and together they form the foundation for long-term customer relationships. At 10,000 machines a year, the installed base compounds fast. Each new unit is either a future annuity or a future complaint on a shop floor in a market Bodor cannot afford to lose. Competitors in Germany, Japan and the United States built their moats on exactly this post-sale layer, not on wattage. If Bodor's service spend grows proportionally with shipments, the milestone signals a genuine structural challenge to incumbents. If it does not, the number is a debt accumulating quietly in the field. Watch the service hires and regional depots over the next four quarters. That ledger, not the production line, decides who owns this market. Author bio: Oliver Hawthorne is a Principal Correspondent permanently stationed at an international technology review, covering industrial hardware, manufacturing economics, and the global machine-tool supply chain.
More
The $15 Brushless Drill at the 140th Canton Fair Isn’t a Deal. It’s a Power Play. Business

The $15 Brushless Drill at the 140th Canton Fair Isn’t a Deal. It’s a Power Play.

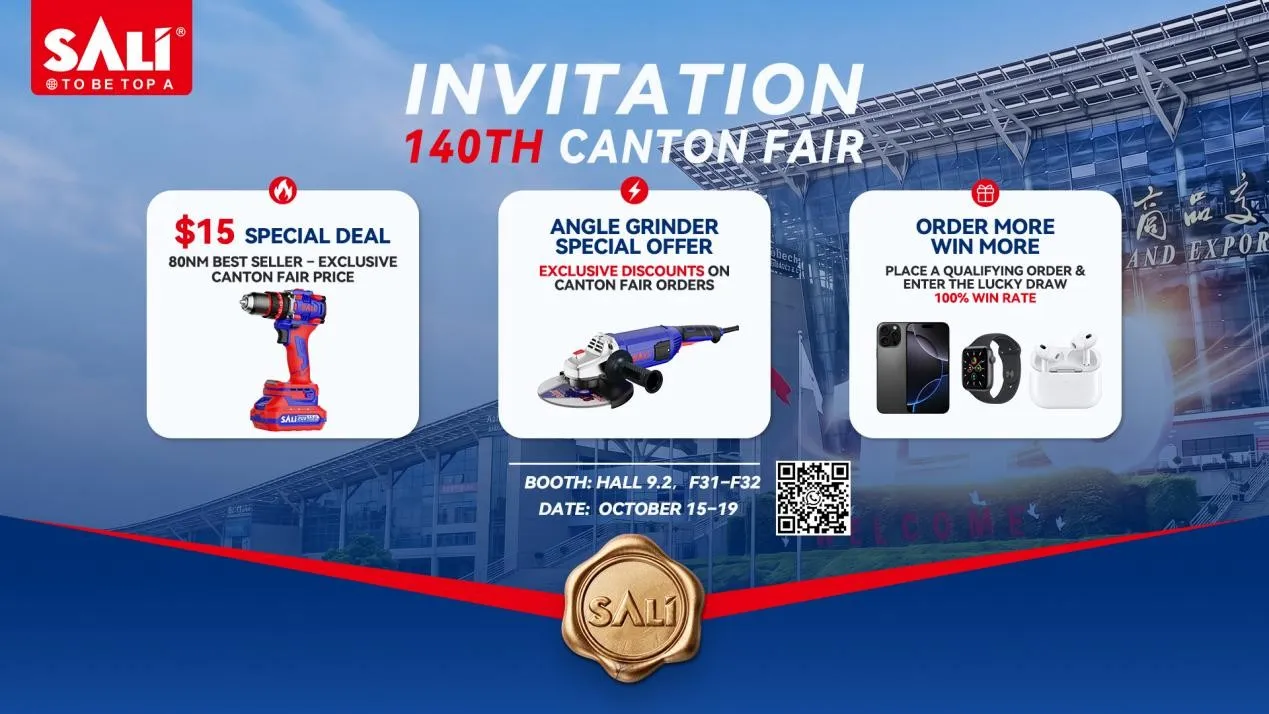
(SeaPRwire) - By: Robert Kensington The power tools distribution game is a blood sport. Margins are thin. Freight costs are brutal. Every importer chases the same prize, a supplier who can bundle SKUs and shrink the vendor list. SALI Tools walks into the 140th Canton Fair holding exactly that playbook. The press release dresses it in polite phrases. It talks about reviewing products and discussing sourcing requirements. It points buyers to Hall 9.2, Booth F31–F32, from October 15 to 19, 2026. None of that is the real news. The real news is the commercial strategy buried inside a routine exhibition notice. SALI is not showing up to make friends. It is showing up to capture channel mindshare. The weapon of choice is a fifteen-dollar drill. Look at the official facts first. SALI was founded in 2010. Its catalogue covers cutting, grinding, polishing, and drilling. The accessories include cutting and grinding discs, flap discs, diamond saw blades, drill bits, and hole saws. Its power tool range covers angle grinders and cordless drills. The target applications span metalworking, construction, stone processing, and maintenance. That is standard fare for a Chinese tool exporter. The interesting part is the bundling logic. The press release says buyers can source complete combinations. An angle grinder with matching cutting and flap discs. A cordless drill with drill bits and hole saws. The stated rationale is that distributors can consolidate purchasing and develop coordinated product lines for local channels. The true intention is sharper. The power tool is bait. The accessories are the annuity. Every channel veteran knows consumables carry the margin. The hardware is just the foot in the door. SALI has structured its entire fair presence around that idea. Then come the fair-only offers. The 80Nm brushless cordless drill goes for US$15. That price is not a discount. It is a statement of intent. An 80Nm brushless machine at that level is either a loss leader or a deliberate entry weapon. Selected angle grinders also carry exclusive discounts. The lucky draw for a smartphone, smartwatch, or wireless earbuds is a small sweetener, tied to qualifying B2B orders. The exact thresholds will be revealed by the sales team on site. That is where the real negotiation begins. Sales Manager Lily leads the team. The stated agenda covers product selection, market requirements, purchasing plans, and distribution opportunities. The release also mentions product development, international supply, and overseas channel support. The phrase that matters most is "cooperation beyond a single order." That is the core message. SALI does not want your one-time quote. It wants a structural position in your supply chain. Buyers should arrive with their own volume forecasts and ask for the mixed-container pricing first. A head start can be arranged through Lightman Yu at www.salitools.com or salimarketing@pcsali.com. Here is the plain-spoken truth. The Chinese power tools export market is overcrowded. Factories that survived tariff shocks and freight chaos now face a demand cycle that punishes passive players. The winners are the ones who sell complete systems and defend their channel partners. SALI's Canton Fair strategy fits that pattern. The US$15 drill is the hook. The accessory attach rate is the test. Distributors who see through the pricing gimmick will still find a serious supplier. The team is there to discuss specifications, packaging, order planning, and regional distribution needs. The booth is compact. The offer is not. Sales Manager Lily and her crew will be measuring which buyers understand the play. Those who walk away because the display looks ordinary will hand the advantage to the next buyer in line. The reshuffling of market share in this industry happens exactly here, one negotiated order at a time. Do the math on the flap discs before you judge the drill. Author bio: Robert Kensington, an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion.
More
The Hanoi Sandbox Gambit: EHang Isn’t Asking Vietnam for Permission. It’s Co-Writing the Rulebook. Business

The Hanoi Sandbox Gambit: EHang Isn’t Asking Vietnam for Permission. It’s Co-Writing the Rulebook.

(SeaPRwire) - By: Ethan Gallagher The applause around this MOU is premature. EHang just secured permission to experiment in Vietnam, not permission to operate commercially. The difference between those two things is the difference between a laboratory and a business. Anyone with hardware experience knows that a signed memorandum in a government office is the easiest step in the entire chain. The hard steps come later, at altitude, with a passenger onboard and a city watching below. This is not a breakthrough. It is a starting line. And the industry should treat it with the sobriety it deserves, because delivering the EH216-S from a hangar to a revenue flight is a grueling path that most companies never complete. The official record is straightforward. EHang's Global Fast Track Program now counts Vietnam as its second country, following Sri Lanka. Hanoi is the first city-level destination. The company's partner, HungViet Technology and Investment Trading JSC, signed an MOU with the Hanoi Department of Science and Technology. The ceremony drew serious political weight. Truong Viet Dzung, Vice Chairman of the Hanoi People's Committee, attended. Cu Ngoc Trang, Director of Hanoi DOST, attended. EHang sent CFO Conor Yang. That lineup signals government-level engagement, not just commercial outreach. The technical program centers on the EH216-S pilotless human-carrying aircraft at Hoa Lac Hi-Tech Park. The work proceeds in phases. Controlled test flights of the EH216-S come first. Then a UTM model. Then an operations control center model. HungViet will commit technical, financial, and human resources starting October 2026, prepare the sandbox application materials, and conduct flights only after authorization. EHang provides the aircraft, the operational technology systems, and personnel training. The agreement also covers joint development of technical standards and regulations. The plan extends to cargo-carrying variants of the EH216 series, not just passenger transport. After Hanoi, EHang intends to pursue Ho Chi Minh City and Da Nang. The company also held discussions at the DGCA/61 conference with delegates from Malaysia, Laos, Fiji, Cambodia, the Philippines, Tonga, Vietnam, Maldives, Bhutan, and Nepal. Vietnam's tourism market explains the enthusiasm. The country received nearly 21.2 million international arrivals in 2025, an all-time high. Yang framed the strategy around safety and compliance as the bedrock of commercialization, which sounds cautious but actually describes a very deliberate expansion doctrine. Now the subtext the press release cannot state. EHang is not just testing aircraft in Hanoi. It is co-authoring the regulatory framework that will govern them. The sandbox mechanism is a legal construction that lets a government authorize flights without having a permanent certification pathway in place. That is convenient for both sides. Hanoi gets to appear technologically progressive. EHang gets to fly. But the real prize is the rulebook. The parties will jointly develop technical standards. That means EHang's engineers sit in the same room as Vietnamese regulators, defining what safe looks like for pilotless eVTOL operations. When you write the standards, you shape procurement decisions, competitive barriers, and market entry conditions for everyone else. This is not transportation policy. It is industrial policy with EHang's fingerprints on every page. The tourism numbers clarify the actual revenue thesis. 21.2 million international tourists do not come to Hanoi for commuter transit. They come for experiences. An EH216-S sightseeing flight over the city is an attraction, not a commute. The commercial model resembles a theme park ride with a premium ticket price. Ho Chi Minh City and Da Nang are obvious extensions because they sit on the same tourist circuit. Cargo variants matter for a different reason. Freight regulation is lighter than passenger regulation. EHang can use cargo operations to accumulate flight hours, maintenance data, and airspace credibility before carrying humans. It is staged risk deployment. The DGCA/61 outreach shows the strategic pattern. Ten countries in one conversation. EHang is not waiting for a global consensus. It is collecting bilateral wins across the Asia-Pacific, each sandbox feeding the next with operational reference data. The supply chain reality is harsher than the ceremony suggests. EHang is a manufacturer. It needs orders, volume, and repeat revenue. The Hanoi sandbox produces none of those immediately. What it produces is something equally valuable: proof. The eVTOL industry is drowning in concept videos and abandoned certification timelines. Piloted competitors in the United States and Europe are stuck in extended regulatory review cycles, burning capital while waiting for airworthiness approvals. EHang's bet is that a pilotless aircraft, operating under sandbox permission in a Southeast Asian market, can accumulate real-world operating data faster than any Western bureaucracy can move. Vietnam is the test laboratory for that bet. Every safe flight at Hoa Lac Hi-Tech Park becomes ammunition for the next negotiation, in the next country, with the next regulator. But the risk is severe. This is a pilotless human-carrying aircraft operating near a dense urban center. If an EH216-S fails in Hanoi, the damage does not stay in Vietnam. It poisons the regulatory conversation across all ten countries EHang courted at DGCA/61. Fatal accidents involving unmanned passenger aircraft offer no second chances. The verdict is simple. This MOU matters only if the first flight with a passenger lands safely. EHang has the regulatory creativity to open doors. It now has to prove its hardware can survive the scrutiny that comes through them. Author bio: Ethan Gallagher, a Silicon Valley hardware architect and infrastructure strategist. Over two decades designing autonomous vehicle systems and advising mobility startups on certification strategy, sensor integration, and airspace deployment.
More
Baijiu With a Patent on “Healthier Drunk”? Tinghua Just Got the USPTO to Blink Business

Baijiu With a Patent on “Healthier Drunk”? Tinghua Just Got the USPTO to Blink

(SeaPRwire) - By: Lucas Caldwell A Chinese liquor maker just walked out of the USPTO with a Notice of Allowance for a technology that claims to make alcohol less harmful. Not flavor. Not packaging. Harm reduction, plus a tumor-prevention application on the U.S. filing. Read that twice. Tinghua Liquor is patenting the idea that baijiu can be engineered to hit your parasympathetic nervous system, not just torch your sympathetic one. If this holds up, the distilled-spirits playbook gets rewritten. If it doesn't, it's still the boldest IP claim this industry has seen in years. Here are the dehydrated facts. The EPO granted the corresponding patent on May 6, number EP4353263 B1. The U.S. application, published as US 2024/0252453 A1, then received its Notice of Allowance after rigorous examination. Both offices tested novelty, inventive step, and industrial applicability. The U.S. scope goes further than the European one. It adds prevention and/or treatment of tumors. The release is dated September 28, 2026, out of Yibin. Two of the world's toughest patent regimes signed off. That's not nothing. The mechanism is what matters. Tinghua calls it "Dual Activation." Conventional drinking spikes sympathetic activity, driving oxidative stress, inflammation, metabolic burden. Their theory says reformulated spirits can coordinate sympathetic and parasympathetic activation, triggering endogenous repair and antioxidant responses. Underneath that sits a processing stack: controlled-strain fermentation, molecular distillation, membrane separation. They identify thousands of trace compounds, strip the ones tied to bad reactions, enrich selected actives. Precision ingredient editing applied to aged liquor. Now the game theory. The global spirits industry spent a century optimizing taste, yield, and cost. Physiological response was treated as regulatory noise, not R&D territory. Tinghua is carving a moat exactly where nobody else built walls. Patents in both the EPO and USPTO mean any Western distiller wanting "health-oriented" spirits may have to license Chinese IP or litigate. That's a bizarre inversion. The traditional medicine framing, yin-yang balance from the Huangdi Neijing translated into neurophysiology, is either genius positioning or a clinical-validation landmine. Skepticism is warranted. A patent proves novelty, not efficacy. Notices of Allowance don't require human trials. The tumor-prevention claim in the U.S. filing will draw FDA attention fast, because health claims on alcohol are regulatory dynamite in Western markets. Big players like Diageo and Pernod Ricard have legal teams that live for this fight. And peer-reviewed replication of Dual Activation is, so far, company-asserted. The gap between granted IP and demonstrated biology is where most of these stories die. Watch the first independent clinical dataset on Dual Activation, because whoever publishes it controls the next decade of this category. Author bio: Lucas Caldwell is a tech opinion leader with millions of followers on X/Twitter, covering the collision of frontier science, intellectual property, and consumer markets.
More

SPACs Keep Stalling: Why Columbus’ Adjourned Vote Is a Red Flag, Not a Delay Tactic

(SeaPRwire) - By: Robert Kensington A reconvened SPAC general meeting that adjourns without a single vote cast tells you everything and nothing. It tells you the deal is not ready. It tells you nothing about why. The corporate-speak version says Columbus Acquisition Corp wanted to ensure a "full and fair disclosure" before shareholders weighed in on the WISeSat.Space Corp combination. The real version is simpler. Someone is buying time. Here is what actually happened. The company filed its definitive proxy statement with the SEC on August 19, 2026. That document lays out the proposed business combination and the terms shareholders were being asked to approve. The original Extraordinary General Meeting did not happen on schedule. Instead, it reconvened and then immediately adjourned on September 28, 2026, to 9:00 a.m. Eastern Time the following day. The meeting was held at Loeb & Loeb LLP offices at 345 Park Avenue, New York, NY 10154, with a virtual teleconference option also available. Shareholders with the August 17, 2026 record date remain eligible to vote, even if they sold their shares after that cutoff. The company's proxy solicitor, Advantage Proxy, Inc., based in Yakima, Washington, stands ready to field questions. Now consider what the adjournment signals beneath the surface. A SPAC does not reconvene and then immediately adjourn unless there is a material obstacle. That could be a shortage of shareholder support. It could be a last-minute valuation dispute between the sponsor and the target. It could be a redemption scenario so large that the deal economics collapse if too many holders cash out. Fen "Eric" Zhang, the company's chairman and CEO, and Jie "Janet" Hu, the CFO, are growth-oriented executives with stated track records in value creation. But track records do not rewrite voting math. The fact that no business was conducted at the reconvened session means the core question remains unanswered. Will the WISeSat deal get enough affirmative votes to close? The SPAC market has shed its glamour fast. The era of free pass deals with speculative targets is over. Investors now demand proof of revenue, proof of margins, and proof that the deal thesis holds up under stress. Columbus is asking shareholders to approve a combination that, based on the proxy filing, still has not cleared a critical hurdle. The adjournment is not a routine procedural formality. It is a signal that the commercial mechanics of this deal are not yet settled. Sponsors who adjourn without resolving the underlying tension usually reopen the vote under duress, not confidence. What happens next will be blunt. If Columbus secures sufficient support by September 29, the vote proceeds and the WISeSat combination moves forward. If it does not, the SPAC faces liquidation or a new target search, both of which destroy value for retail shareholders who bought into the premise without fully reading the proxy. The market has stopped rewarding SPACs that cannot deliver. This adjournment is not a pause. It is a warning. Author bio: Robert Kensington is an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion.
More

The UN Just Watched China Sell the Grid AI Playbook. The Hard Part Comes Next.

(SeaPRwire) -By: Oliver Hawthorne For years, grid AI meant watching transformers and hoping. The industry's obsession was uptime. Hangzhou has shifted the question. The grid is a production input for startups making cameras, chips and visual intelligence gear. Those firms do not ask whether power will come back. They ask whether a voltage dip kills a batch of silicon wafers. They ask whether the electricity they buy passes an overseas customer's carbon audit. Hangzhou has more than 13,000 tech and innovation companies. Nearly 80 percent of the economic value from each kilowatt-hour comes from "new quality productive forces," including AI and visual intelligence firms. Most are early-stage small companies. They cannot build an energy analytics team. So State Grid Zhejiang built an AI service instead. That inversion is the real story. The stage was the UN Global Compact Leaders Summit in New York on Sept. 22-23. The State Grid team was China's sole representative. Its solution was called "AI for good: Chasing the light, seeking the carbon." It won the China round of the SDG Innovation Accelerator, which involved 49 companies. It then passed the global online showcase against winners from 22 countries and regions. From there it landed in the global top five. The pitch rested on two free services. Powertrace follows the electricity supply path. Carbonseek follows embodied carbon. Behind them is Guangqing, an AI super-agent that analyzes a megacity grid in real time. The numbers are blunt. The system continuously assesses 9,517 transmission and distribution lines and 503 substations. It detects grid abnormalities, voltage disturbances, and equipment overloads in seconds. It generates precise dispatch strategies within one minute. Customers get power supply reliability above 99.999 percent. Average annual outage duration per customer has fallen to 3.15 minutes, a globally advanced level. On the carbon side, Carbonseek calculates emissions by hour and by location, based on electricity consumption. It then tells a manufacturer when to run production in the cleanest window. So far, 56 technology startups have used it. Smart manufacturing clients have cut product carbon footprints by 6.6 percent. The team plans to reach at least 10 percent of Hangzhou's tech startups by the end of 2026. Then it wants 30,000 SMEs across China within a year. After that, an open-source toolkit for SMEs worldwide. The UN reaction was not ceremonial. David Steingard, head of the UN Global Compact's Principles for Responsible Management Education, said the concept was outstanding and scalable. Bruna Elias, senior manager of the SDG Innovation Accelerator, said the solution could scale globally. The Ghanaian delegate, Juliet Makafui Gbate, described it as a practical answer for Africa's unstable green power supply. She asked about cooperation. That is a credible validation trail. But none of it explains how the project turns into a business model. The free part is the trap. Powertrace and Carbonseek look like charity tools. In practice, they are sensors for the grid. Every trace reveals where dispatch is fragile. Every carbon calculation reveals how factories respond to price signals and carbon intensity. That data stream has commercial value beyond any startup. It tells a grid operator where to reinforce lines. It shows where to place storage. It flags which industrial customers are cheap to serve versus expensive to serve. The scale target confirms the ambition. 30,000 SMEs connected to one AI dispatch logic creates an enormous coordination surface. When that happens, the open-source toolkit becomes the interesting play. If the toolkit ships globally, utilities outside China face a stark choice. They can adopt a proven dispatch model. But they accept carbon accounting methods defined by a Chinese state grid. Or they can build their own systems from scratch. Their tech startups will fall behind on carbon traceability while they build. The smartest response is not to block the toolkit. It is to replicate the model inside a neutral data trust before the standard hardens. The clock is running. The UN applause will fade. The AI interface between power dispatch and factory carbon decisions is being set right now. The grid war is no longer about copper. It is about who gets to define the clean kilowatt-hour. Author bio: Oliver Hawthorne, Principal Correspondent for an international technology review, covering industrial AI, grid digitization, and the power networks that run modern compute infrastructure.
More

How a Niche Oilfield Supplier Just Outbid Giants in Saudi Arabia — And Why It Matters

(SeaPRwire) -By: Christian Pierce Most oilfield equipment suppliers cling to incumbent relationships. They win renewals because switching costs are high. Procurement teams prefer familiarity. A Saudi Aramco purchase order for specialty connectors and pipes was supposed to follow that script. The March 2026 order under the long-term supply agreement, worth $11 million, confirmed the comfortable arrangement. Then the order came through a competitive tender instead. OMS Energy Technologies won a $7.1 million order from Saudi Aramco through open bidding. The products fell outside the existing long-term agreement. That is why the tender happened. OMS Oilfield Services Arabia Ltd. competed against established rivals and took the contract. Deliveries start in January 2027. Saudi Aramco, the world's largest oil producer, does not run competitive tenders for routine purchases. This one needed specific technical and operational specifications. The tender signal is clearer than a renewal announcement. On the other side of the map, a different pattern played out. PT OMS Oilfield Services received a $2.3 million order from Pertamina Hulu Rokan for surface wellheads and Christmas trees. This came under an existing three-year supply contract. A $1.3 million extension to that same contract was announced in March 2026 after demand exceeded original values. Products will ship from the Duri facility in Indonesia by March 2027. The total new orders sit at $9.4 million combined. But the total is a rounding error against the real story. What actually matters is that OMS is now proving it can win both sides of the same equation. Competitive tender victories in one market. Contract extension renewals in another. Chairman and CEO How Meng Hock flagged the strategy explicitly. He cited diversification beyond the core Saudi Arabian market as a deliberate direction. The company has 11 manufacturing facilities across six jurisdictions in Asia Pacific and MENA. Their balance sheet carries no debt. That financial positioning is not incidental. It allows capital deployment without leverage risk during commodity cycles. The deeper implication concerns market structure. Upstream oilfield supply has always been relationship-driven. Long-term agreements lock in volume. But competitive tenders reveal whether a supplier truly outperforms on technical capability and delivery execution. Saudi Aramco chose OMS over competitors who likely held comparable relationships. That selection matters more than the order value. It establishes a template. Other national oil companies in the region watch those tender outcomes carefully. Procurement officers reference precedent when evaluating next bids. OMS Indonesia represents the second axis of this strategy. Pertamina Hulu Rokan expanded an existing contract because demand outpaced the original ceiling. The Duri facility handles production. This is not a speculative entry. It is a proven track record reinforcing itself. The March 2026 extension preceded this new order by months. Demand velocity is the signal here. For the broader upstream equipment supply chain, this signals two converging pressures. Suppliers without geographic diversification face concentration risk when any single national oil company tightens procurement standards. Competitive tender exposure rewards operators who combine technical depth with regional manufacturing presence. OMS has positioned itself at exactly that intersection. The $9.4 million in new orders validates a strategy that others will attempt to replicate. The real question is who can match the facility footprint fast enough. Author bio: Christian Pierce is a chief financial columnist and markets commentator covering energy sector procurement dynamics and upstream supply chain economics for global trade publications.
More

EBC’s Live Trader Cup: The Real Prize Is Your Order Flow, Not the Podium

(SeaPRwire) - By: Robert Kensington EBC did not pick this window by chance. The EBC Live Trader Cup Indonesia starts on 28 September and runs to 31 October 2026. That window wraps itself around the September Non-Farm Payrolls report, the CPI release, and the Federal Reserve's FOMC decision. These are the exact moments gold markets stop being polite. The contest is branded as a chance to prove trading skill and fight for a title. Look closer. The entry price is only USD 100. The ranking system uses percentage returns. That setup pulls in thousands of small traders. They bring deposits, emotions, and the urge to trade news spikes. The broker brings the arena. The arena always favours the house. Start with the published facts. The tournament runs from 28 September to 31 October 2026. The theme is "Buktikan Skill Tradingmu, Rebut Gelar Juara!" which translates roughly to "Prove your trading skill, take the champion title." Participants can trade forex and gold, with XAUUSD as the local favourite. Registration happens through the EBC User Portal. Each trader must use a new or existing PRO or STD live account with at least USD 100 in equity. The account must be free of open positions and active copy trades. One participant can register up to ten accounts but can take home only one prize. The top ten traders share prizes worth up to IDR 40 million. The breakdown goes like this. First place receives USD 1,000. Second place receives USD 500. Third place receives USD 300. Fourth and fifth receive USD 100 each. Sixth to tenth receive USD 50 each. Prizes arrive within 30 business days after the competition ends. Winners must finish with a positive final return. Now the mechanics that matter. Ranking is based on percentage return, not nominal profit. A USD 100 account can beat a USD 10,000 account. Deposits made during the competition increase the denominator. That means adding money mid-contest lowers your percentage gain unless your trading outpaces the extra equity. Withdrawals do not affect the calculation. The release even answers the beginner question about minimum capital. Here it is, in plain terms. One lot of XAUUSD equals 100 troy ounces of gold. Lot sizing and pip calculation determine your risk per position. That is the official front end of the story. Now read the commercial layer beneath the scoreboard. Every participant must share trading signals inside the EBC copy trading community. That is not buried in small print. It is stated in the release as a transparent approach that lets beginners observe experienced traders. In plain business terms, the contest converts skilled traders into public signal generators. Their entries, exits, and risk patterns become visible to the whole client pool. Other users can copy those trades. That creates a feedback loop for EBC. The best performers pull followers. The followers bring deposits. The followers also keep paying spreads and swaps. The calendar does the rest of the work. The September NFP is due on 2 October. CPI inflation data follows on 14 October. The FOMC meeting is scheduled for 27 to 28 October, with the rate decision announced in the early hours of 29 October Western Indonesian Time. That sequence is a pressure cooker for XAUUSD. Many traders focus on the London session, which opens around 14:00 WIB. Others trade the New York session in the WIB evening. The overlap between those two sessions is the busiest window. Scalpers jump on lower timeframes. Smart Money Concepts disciples watch liquidity grabs. Support and resistance traders mark levels. The contest hands them the same market, but with an audience. The audience is not there for charity. It is there to copy. The official quote from EBC's marketing manager, Fikri Fairuz, says the event provides a fair arena where discipline and strategy matter more than account size. That is half true. Discipline and strategy matter because ranking uses percentage returns. But the arena itself is far from neutral. EBC controls the infrastructure, the spreads, the signal feed, and the prize payout schedule. The competition is a customer acquisition machine dressed as sport. None of this is illegal. EBC is a regulated group, with operating entities under the FCA, ASIC, CIMA and FSCA. The point is simpler. A contest like this one floods the broker's order flow pipeline. The prize pool of IDR 40 million is small compared with the aggregate deposits that a flood of USD 100 accounts will bring. Some traders will win. Most will not. And the losing trade history itself has value, because the copy trading community turns it into educational content for the next cohort. So here is the blunt read. EBC is not running this cup to crown a champion. It is running it to collect retail order flow during the most volatile month of the year. The best use a trader can make of the EBC Live Trader Cup is to treat it as a risk-managed simulation. Skip the heroics. Respect the leverage. The house collects its edge from every trade you place. If you still want to compete, protect your capital first and the trophy second. Author bio: Robert Kensington, a former operations executive turned industry analyst with two decades in emerging-market expansion and capital allocation. He writes about the distance between corporate promises and on-the-ground commercial reality.
More
LiTime Brought Two Batteries to Essen. The Actual Product Was a BMS. Business

LiTime Brought Two Batteries to Essen. The Actual Product Was a BMS.

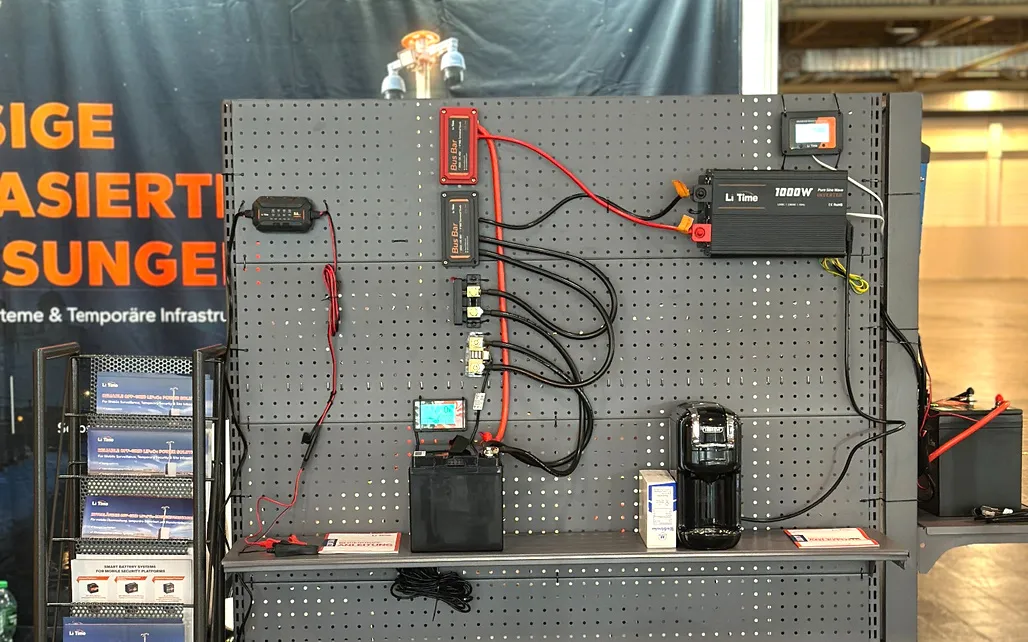
(SeaPRwire) - By: Ethan Gallagher Security integrators do not lose sleep over energy density. They lose sleep over the truck roll. A camera on a pole with a dead lead-acid battery costs a site visit, a ladder, and half a technician's afternoon. LiTime walked into Security Essen 2026 with that specific wound in mind. The show ran Sept. 22 to 25 in Essen, Germany. The booth presented two things. One was Bluetooth monitoring. The other was battery communication, system integration, and remote management. Strip the trade-show language away and the company is selling visibility. That is a smaller claim than it sounds. It is also a much larger one than the release admits. The release frames two solutions as two separate answers. I read them as one answer with two price points. LiTime pairs a 12V 50Ah LiFePO₄ battery with a Smart Shunt for standalone gear like alarm systems and outdoor surveillance cameras. Keep the existing battery. Bolt on a small data collector. For distributed projects, the 24V 50Ah Smart ComFlex pushes data into compatible systems such as Victron. Same problem, different wallet. An integrator running forty unattended cabinets does not want forty apps. They want forty rows in a dashboard they already open every morning. Here is what LiTime actually put on the record. Traditional lead-acid batteries have limited lifespan and demand frequent maintenance. Off-grid security deployments are not uniform. Standalone equipment needs on-site checks. Distributed, unattended installations need centralized battery data access. So the catalog splits. The 12V 50Ah plus Smart Shunt handles the first case without swapping in a communication-enabled battery at all. The 24V 50Ah Smart ComFlex handles the second, reducing point-by-point inspections across scattered sites. The subtext is a retrofit play versus a design-in play. A retrofit keeps an installed base alive. You sell the shunt, you keep the account, and you buy yourself two more years of goodwill before the battery really dies. A design-in is harder. It asks the integrator to specify your cell chemistry and your firmware on a drawing that a client will sign. That is where the margin lives. It is also where the accountability lives. Once your BMS sits inside somebody's monitoring stack, every dropped frame becomes your support ticket. LiTime is quietly volunteering for that burden. Most battery vendors spend their entire marketing budget avoiding it. The second half of the story is the data path, and this is where the engineering gets interesting. The two solutions collect information differently. Smart Shunt sits outside the battery. It measures voltage and current, then sends readings over Bluetooth to a phone. Simple. Cheap. No firmware negotiation with anyone. Smart ComFlex does the opposite. It embeds LiTime's proprietary Smart T5.0 BMS with native CAN and RS485 interfaces. Voltage, current, temperature, SOC, and operating status travel directly into compatible energy management systems. The same T5.0 technology appears in LiTime's new LiHeat™ 12V 320Ah ComFlex LiFePO₄ Battery. Read that product line carefully. A 12V 320Ah unit with heating and native communication is not aimed at a warm server room. It is aimed at an unheated roadside cabinet in February. That is a cold-climate, unattended, high-capacity application. It is also a signal that the T5.0 BMS is becoming a standard part number across the portfolio rather than a flagship feature. Naming Victron as a compatible system matters too. LiTime is accepting the role of component, not platform. That is a deliberate trade. Nobody wants a fourteenth dashboard. Batteries are commodity hardware now. Cells arrive from a handful of suppliers, and the price curve only moves one direction. What separates vendors is firmware, protocol support, and the documentation an integrator needs before a spec review. The Smart Shunt is a useful part. It is also copyable in a quarter by any competitor with a sourcing agent and a PCB house. The T5.0 BMS, with CAN and RS485 built in, is the only piece of this announcement that takes real time to replicate. That is the supply chain reality behind a booth full of shiny blue cases. Whoever gets written into the integrator's monitoring stack owns the replacement cycle for the next decade. Whoever stays app-only becomes interchangeable, and interchangeable parts get bought on price. LiTime will show up again at Expoprotection 2026 in Paris this November with the same one-stop power pitch. Watch what gets published between the two shows. Integration guides and register maps mean the strategy is real. Booth photos and social clips mean it is still a brochure. Any integrator evaluating this should demand the CAN documentation before signing a purchase order. If a vendor will not hand over the protocol sheet, that battery is not a component in your system. It is a subscription with extra steps. Author bio: Ethan Gallagher, a Silicon Valley hardware architect and infrastructure strategist who advises integrators on power, telemetry, and remote asset design.
More

Webuy’s Grocery Farewell: How a Desperate Pivot Almost Became a Masterstroke

(SeaPRwire) -By: Robert Kensington Let's be honest about what we're looking at here. Webuy Global didn't choose to exit grocery e-commerce because they saw a brighter future in travel. They left that business because it was bleeding capital and consuming management attention. The narrative spun around "strategic focus" and "higher-margin opportunities" reads like a boardroom rehabilitation effort. When a company exits a segment entirely, it usually means one thing: the math stopped working and nobody wanted to announce it publicly. But there's something else happening here that deserves attention beyond the standard earnings-call optimism. The official record tells a clean story. H1 2026 revenue from continuing operations hit US$14.31 million, up 94.4 percent from the prior year period. Gross profit came in at US$1.83 million after expanding 131.7 percent. Gross margin moved from 10.71 percent to 12.77 percent. The total net loss narrowed to US$3.32 million, a decline of 56.8 percent compared to H1 2025. Packaged-tour revenue surged 106.8 percent in Singapore and 106.9 percent in Indonesia. All revenue now comes exclusively from travel operations after the grocery segment was reclassified as discontinued. This is the sanitized version presented to shareholders and exchange regulators. It is also only half the picture. What the press release leaves unsaid requires reading between the lines. Webuy's exit from grocery wasn't a graceful strategic reallocation. It was a retreat from a market where they never achieved defensible scale. The fact that gross margin barely crossed 13 percent in the new travel segment suggests Webuy is still operating in a low-margin environment where growth alone cannot justify the burn rate. The CEO's emphasis on AI-enabled operations, customized journeys, and the China inbound push through WeTrip reads like a checklist of buzzwords designed to attract attention from a market hungry for the next narrative. But building a China inbound travel platform is not a novel concept. Multiple operators already hold entrenched positions with strong relationships to Chinese outbound tour operators and domestic hotel and transport suppliers. Webuy is entering through a narrow corridor with AI as its primary differentiator, which is a thin moat at best. The 132 percent gross profit increase looks impressive until you consider the base was alarmingly small. US$1.83 million in gross profit after six months means the company is still far from covering its operating expenses. The narrowing net loss is a positive signal, but the absolute figure remains deeply negative. The real test for Webuy will come in how it handles the next eighteen months of scaling WeTrip while proving that AI integration actually reduces cost per booking rather than simply adding another layer of technology spend. The company needs to move beyond the Singapore and Indonesia packaged-tour growth numbers and demonstrate that China inbound tourism can deliver sustainable unit economics. So far the evidence is directionally favorable but insufficient to declare victory. This is a company that traded one struggling business for another unproven one. Whether the second attempt sticks depends entirely on execution speed and capital efficiency. Nobody is winning anything yet. Author bio: Robert Kensington is an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion.
More

When Meta’s GPUs Died Every Three Hours, Someone Noticed the Downtime Was the Real Business

(SeaPRwire) -By: Ethan Gallagher KAYTUS walked into a market that already knows the pain but has not solved it. The company's AI Managed Service pitch is straightforward. Stock spare parts locally. Send factory-certified engineers to the data center floor. Fix a failed node in four hours instead of four days. The numbers look impressive on paper. Thirty percent reduction in recovery time. Twelve-hour average resolution per failed node. But here is what the press release does not say. KAYTUS is not selling maintenance. It is selling a seat at the table where compute availability becomes a contractual liability. The AI infrastructure market is approaching a point where the cheapest hardware is worthless if you cannot keep it running. This service announcement is really a land grab for that liability window. The timing is not accidental. The company announced the service from Singapore on September 28, 2026, right as the industry grapples with the operational reality of scaling AI clusters beyond the deployment phase and into sustained production. The press release cites Gartner's projection of $2.67 trillion in global AI spending by 2026, with $1.48 trillion allocated to AI infrastructure. That is the headline number. The real number is what Uptime Institute found in their 2026 outage analysis. Fifty-seven percent of respondents reported costs exceeding $100,000 for their most recent major outage. One in five reported losses above $1 million. Some compute leasing agreements impose compensation of up to 25% of the monthly rental fee for major SLA breaches. Meanwhile, Meta's technical report on Llama 3.1 405B recorded 419 unexpected interruptions during 54 days of pretraining on 16,384 GPUs. That averages one failure every three hours. Approximately 78% were confirmed or suspected hardware failures. A study presented at SOSP 2025 documented over 44,000 incidents across 778,000 training jobs in just three months on a large production LLM training platform. The industry subtext is that nobody building a thousand-node AI cluster can afford to treat hardware recovery as a logistics problem. Every hour that hardware sits dead is an hour you are losing money. Compute is billed by the hour. SLA penalties compound by the hour. Your customers' workloads are idle by the hour. Traditional maintenance models compound the problem. Extending recovery beyond 48 hours in a high-density AI data center means you are paying for compute that is not generating any value. That is a business model leak, and it is getting harder to ignore as clusters scale into the thousands of accelerators. KAYTUS positions its service around five components. Onsite critical spares inventory including compute nodes, network switches, and high-bandwidth NICs. Factory diagnostic equipment deployed directly at customer sites. Twenty-four-seven certified engineering coverage with Tier 2 specialist backup. AI-assisted failure prediction for proactive maintenance. Customized lifecycle maintenance tailored to each deployment. The company claims deployment at a leading global cloud service provider's AI data center supporting over 100 racks and thousands of accelerators. Caesar, Head of Services at KAYTUS, put it plainly. The value of a compute asset is not defined by its scale on day one, but by how reliably it delivers capacity hour after hour throughout its operational lifecycle. The industry subtext here is more interesting. KAYTUS is an OEM. It designs and manufactures GPU hardware. By embedding itself into the maintenance workflow with locally stocked spares and factory-grade repair tools, it is creating a dependency loop. Once a data center operator standardizes on KAYTUS onsite service, they are locking in hardware refresh cycles tied to KAYTUS's roadmap. The alternative is building an in-house OEM-equivalent support team, which costs millions and requires certified engineering pipelines that take years to develop. For most operators, that is not an option. The traditional maintenance model fails for structural reasons that go beyond cost. AI data centers now operate at rack power densities exceeding 40 kilowatts. Heterogeneous hardware means sourcing critical replacement parts from regional warehouses can extend delivery to several days. Complex node failures requiring offsite factory repair add transportation and queue delays. Faults spanning compute, networking, and cooling systems extend diagnosis timelines for conventional operations teams. Remote support alone cannot fully replace specialized onsite expertise. Node recovery stretches to 48 hours or more. For infrastructure billed by the hour, that is a direct revenue hit. KAYTUS's approach of deploying factory diagnostic equipment on-site eliminates the return-to-factory step entirely. Engineers can diagnose and repair individual components and complete nodes without sending systems back to the manufacturing facility. Here is the blunt assessment. KAYTUS's onsite service model will become table stakes for anyone running a hyperscale AI cluster with more than a few hundred accelerators. The companies that adopt it early gain a defensible advantage in SLA negotiation and customer retention. The companies that refuse to pay for it will lose compute availability to competitors who can guarantee uptime. The next layer of competition in AI infrastructure is not chip performance. It is recovery speed. Whoever controls the maintenance layer controls the economics of compute availability. KAYTUS just made that bet publicly. Whether it wins depends on whether the market treats maintenance as a commodity service or a strategic differentiator. Based on what I see in data center contracts today, it will be the latter within three years. The companies that build AI infrastructure as a long-term asset rather than a sprint deployment will need this model. The ones that treat compute capacity as a disposable commodity will find their margins eaten alive by downtime. KAYTUS did not just announce a service. It drew a line in the sand and said that the hardware recovery problem is no longer acceptable to solve slowly. Author bio: Ethan Gallagher, a Silicon Valley hardware architect and infrastructure strategist with two decades of experience evaluating AI compute supply chains and data center operations economics.
More
Shenzhen Hospital Says It Can Reverse Diabetes. The Real Product Is a Private Waiting List. Business

Shenzhen Hospital Says It Can Reverse Diabetes. The Real Product Is a Private Waiting List.

(SeaPRwire) - By: Robert Kensington Shenzhen Hengsheng Hospital has put a price tag on diabetes remission. That is the part the press release does not say out loud. The hospital is a subsidiary of Fosun Health. Its Center for Integrative Medicine for Chronic Diseases and Center for Natural Diabetes Therapy announced a new international medical approach. The model uses an optimal mix of traditional Chinese and Western medicine. The approach claims significant success in reversing diabetes. It helped 150 Type 1 patients and over 1,000 Type 2 patients achieve remission. Those numbers are striking. They are also filtered. The launch is in Shenzhen, China. The service is aimed at family offices in the Arab Gulf states and regions. It is also aimed at affluent families in Europe and the United States. It is aimed at international patients. That is not a public health campaign. It is a private medical corridor. The clinical story is real. The commercial story is just as real. The hospital is not selling insulin. It is selling an exit from insulin. That exit is not cheap. It requires travel. It requires follow-up. It requires access to a team led by Professor An Chiying and Dr. Zou Zhenjun. The press release calls this cutting-edge international medical services. The subtext is simpler. Diabetes reversal is being packaged for the wealthy. That is the sharp critique. The medical community should read the data. The market should read the client list. Start with Type 2. Since 2018, Dr. Zou Zhenjun’s team at the centers has implemented treatment protocols. The team says it reversed the progression of diabetes in over 1,000 patients with Type 2 diabetes. The vast majority reduced medication and injection frequency. 80% discontinued medication entirely. The release calls that a complete reversal of diabetes. The official endpoint is based on international consensus. Reversal means HbA1c below 6.5% for at least three months after stopping conventional glucose-lowering medications. It also requires long-term follow-up. That is a strict bar. It is not a vague wellness claim. Professor An Chiying emphasized verifiable metrics. Those metrics include HbA1c, fasting and postprandial blood glucose, time in range, coefficient of variation, C-peptide, and dosages of medications and insulin. The hospital also uses a world-leading mass spectrometry testing platform. That platform identifies underlying causes of diabetes. Then the team applies comprehensive, targeted interventions. The goal is to break dependence on medication. Here is the industry subtext. The real product is not a single treatment. It is a workflow. The workflow includes diagnostics, tapering, monitoring, and behavior management. That workflow is hard to scale. It is also hard to copy. The 80% number is powerful. But the release does not say how many patients were screened. It does not say how many failed. It does not say how many could afford the full program. Those gaps matter. In medical marketing, the denominator is often the hidden story. For Fosun Health, the denominator is not the global diabetic population. The denominator is the set of patients who can reach Shenzhen and stay in the protocol. That set is small. It is also lucrative. Now Type 1. Since 2024, Professor An Chiying’s team has managed 150 patients with Type 1 diabetes from around the world. 30 have successfully discontinued exogenous insulin. That happened under strict medical evaluation and precise follow-up. The remaining 120 reduced their insulin dosage. They also achieved more stable blood glucose levels within target. The Chinese integrated medical team calls this a real-world clinical exploration of a "functional cure for Type 1 diabetes." The definition is careful. Functional remission means maintaining HbA1c below 7% without exogenous insulin. That is not the same as saying Type 1 diabetes is cured. It is a functional endpoint. The subtext is critical. Type 1 diabetes is an autoimmune condition. Stopping insulin is rare. The release does not claim all 150 stopped insulin. It says 30 did. The other 120 still need insulin. That is a more honest picture than the headline suggests. The hospital is not replacing insulin for everyone. It is moving a subset of patients to a lower-insulin state. That is still meaningful. It is also commercially valuable. Professor An and Dr. Zou have been researching integrative medical reversal of Type 2 diabetes in China since 2018. The team has built an authority timeline. On November 14, 2023, World Diabetes Day, Professor An and Dr. Zou released the ultimate guide to diabetes reversal. On November 14, 2024, World Diabetes Day, they proposed the theory of indiscriminate diabetes reversal. The release calls that an outstanding achievement in the functional cure for Type 1 diabetes. This timeline is not just science. It is brand building. It creates intellectual authority. Authority attracts international patients. Patients bring data. Data improves the protocol. The protocol attracts more patients. The press release says the developments have gained attention from patients, the medical community, and international media. That attention is part of the acquisition loop. The contact details confirm it. There is a WhatsApp number with a +852 prefix. There is a phone number with a +86 country code. There is a website. The target patient is someone who can send a cross-border message and then book a flight. The market share question is next. Diabetes care is a massive global business. Insulin, monitoring, medications, and long-term management all generate recurring revenue. A reversal program does not replace that system overnight. It creates a premium niche above it. The hospitals that own the protocol, the data, and the follow-up will capture the wealthy patients. The hospitals that do not will keep selling sick care. Shenzhen Hengsheng is not trying to win the mass market. It is trying to own the top of the market. If the outcomes hold, Fosun Health has a new export. It is not a drug. It is not a device. It is metabolic management. That is the market share reshuffling. The losers will be clinics that cannot prove remission with hard metrics. The winners will be centers that can. The blunt assertion is this. Diabetes reversal is becoming a luxury service line. The public system will still manage the complications. The private system will manage the remission. The split is already visible in the client list. Family offices in the Arab Gulf states. Affluent families in Europe and the United States. International patients. The science may be integrative. The business is segregated by wealth. That is the real launch. Author bio: Robert Kensington, an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion. He tracks cross-border healthcare service models and premium medical exports.
More
Why Toobit Is Parking Its Flag at TOKEN2049 (And What It Really Means for the Exchange Wars) Business

Why Toobit Is Parking Its Flag at TOKEN2049 (And What It Really Means for the Exchange Wars)

(SeaPRwire) - By: Robert Kensington Toobit showed up. Not with a whisper, not with a soft launch, but with a Platinum Sponsor tier, a confirmed booth number, and a pre-conference party co-hosted with one of crypto's most recognizable media brands. That reads like commitment. It also reads like survival theater. The derivatives exchange space has grown suffocatingly crowded. Every platform claims fair execution. Every platform claims transparency. Very few can point to a booth at TOKEN2049 as proof of anything beyond marketing muscle. Let us look at what actually landed on the table. Toobit confirmed booth PB1-41 at TOKEN2049 Singapore 2026. The event runs October 7–8 at Marina Bay Sands. They are a Platinum Sponsor. That is a real line item. Platinum sponsorships at this tier do not cost pocket change. The 2025 edition brought 25,000 attendees from more than 160 countries. Over 7,000 companies showed up. Three hundred plus speakers. Five hundred plus exhibitors. That is a battlefield masquerading as a conference. Toobit is also co-hosting The Blue Party with Coin Bureau on October 6 ahead of the main event. Capacity is limited. Registration requires approval. You do not build that kind of pre-game without budget, relationships, and a deliberate push for mindshare. The official announcement frames this around product storytelling. Crypto trading. TradFi access. On-chain tools. Automated trading systems. AI-driven tools. Those are real offerings listed on their website. But strip the press release language and the picture becomes simpler. A mid-tier derivatives exchange is buying visibility in the single most watched room in crypto. The goal is not education. It is presence. Every founder, every trader, every allocation committee walks that floor. Toobit wants to be remembered when the next funding round opens or the next trading partnership forms. The Booth PB1-41 location is not random. It is placed traffic. Interactive activities and event-exclusive giveaways are not generosity. They are attention capture mechanics. Meanwhile the industry is doing what it always does at these events. Comparing sponsor tiers like badges. Tracking which platforms show up and which quietly fade. Exchange consolidation has been the unspoken story for years. Smaller platforms either get bought, merge, or disappear into illiquidity traps. TOKEN2049 is where the survivors announce they are still standing. Toobit's move signals a bet that scale at events translates to scale in volumes. Whether that bet pays off depends on whether their AI tools and TradFi bridges actually move needles or just look good on a booth screen. One thing is clear. The exchange war is not being won on technology alone anymore. It is being won on who shows up, who pays for the biggest table, and who controls the conversation in the room before the keynote even starts. Author bio: Robert Kensington is an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion, specializing in market positioning and competitive landscape analysis across digital asset sectors.
More

One Antibody, Four Regulatory Regimes: Leads Biolabs Is Quietly Building the Fastest Ticket in Immuno-Oncology

(SeaPRwire) -By: Lucas Caldwell Call it what it is. Opamtistomig just collected its third orphan drug designation, this time from Japan's MHLW, and the pattern is no longer subtle. Leads Biolabs is not chasing approvals one country at a time. It is running a simultaneous four-front regulatory campaign across China, the U.S., Europe, and Japan for a single bispecific molecule. Most biotechs this size struggle to manage one jurisdiction cleanly. This Nanjing outfit is stacking designations like frequent-flyer miles, and each one buys real leverage: subsidies, fee waivers, priority review lanes. The EP-NEC indication is the wedge, but the ambition is plainly much larger. Here is the dehydrated fact set. On September 28, 2026, Leads Biolabs (9887.HK) announced Japan's MHLW granted opamtistomig (LBL-024) orphan drug status for extrapulmonary neuroendocrine carcinoma. The designation unlocks clinical development subsidies, direct MHLW consultation, potential expedited review, fee reductions, and an extended re-examination period post-approval. Before this came the U.S. FDA's ODD in November 2024 and Fast Track in January 2026, plus the European Commission's ODD the same month. China's NMPA granted Breakthrough Therapy Designation back in October 2024. The commercial timeline matters more than the certificates. The NMPA accepted the drug's NDA in August 2026 after granting priority review in July, and it now sits in technical review. If it clears, opamtistomig becomes potentially the world's first approved 4-1BB-targeting antibody, the first approved agonist antibody in this class, and the first approved treatment for EP-NEC. Three firsts on one molecule. The drug has shown efficacy signals across seven tumor types, from NSCLC and SCLC to biliary tract, liver, esophageal, and ovarian cancers. Data has already aired at ASCO, WCLC, and ESMO. Now the game theory. Japan is a $73 billion-plus pharmaceutical market as of 2025, with immuno-oncology alone above $8 billion, trailing only the U.S., China, and Europe. Planting an orphan designation there for a rare, brutal indication is cheap entry. The real play is the regulatory beachhead. Once opamtistomig has priority consultation pathways and an established MHLW relationship through EP-NEC, every subsequent indication filing in Japan rides that same rails. It is 14 indications deep in development, including one registrational study, one confirmatory Phase III, and nine proof-of-concept trials. The mechanistic bet is the sharpest part of this story. PD-L1 blockade plus conditional 4-1BB agonism, built on Leads Biolabs' X-Body platform, targets exactly where checkpoint inhibitors fail: immunologically cold tumors and PD-1-resistant disease. Historical 4-1BB agonists died on systemic toxicity. A bispecific that activates 4-1BB only in the tumor microenvironment, with a safety profile comparable to standard PD-1 inhibitors, solves the problem that stalled an entire drug class for a decade. If the durability claims hold, this is an IO 2.0 backbone, not a niche orphan asset. Watch the NMPA technical review outcome, because the first agency to approve this molecule effectively validates 4-1BB agonism for every competitor still sitting in Phase I. Author bio: Lucas Caldwell, a tech opinion leader with millions of followers on X/Twitter, covering biotech platforms, drug development economics, and the intersection of clinical science and capital markets.
More

Japan’s Synthetic Membrane Bet at ACS 2026: Where the Real Commercial Game Begins

By: Oliver Hawthorne (SeaPRwire) - The US surgical supply chain has a quiet vulnerability most people in the operating room never discuss out loud. Biological patches from cadaver banks and bovine pericardium depend on import logistics that no amount of quality control can stabilize. Tissue adhesion, calcification, infection, and fluid leakage remain stubborn problems for implanted surgical materials. Surgeons have adapted to these limitations for decades. But the underlying fragility never disappears. Every cadaver bank faces supply constraints that fluctuate with donation rates. Every bovine pericardium source carries disease transmission risk that quality testing can only partially mitigate. When a dura mater substitute fails in a neurosurgical case, the patient bears the consequence. When a pericardial patch adheres to surrounding tissue during cardiac recovery, the surgeon faces a reoperation. The industry has known about synthetic alternatives for years. Most have fallen flat on biocompatibility tests or long-term adhesion data. TamaBio enters a crowded skepticism market. That skepticism is not irrational. The American College of Surgeons Clinical Congress 2026 in Washington, D.C. is where this tension surfaces again. The event runs September 26 through 29. It draws surgeons, researchers, and medical device companies from across the United States. This time, a Tokyo-based company called TamaBio walks into that crowd with something different. Its ion-beam-processed ePTFE membranes are designed to replace biological patches entirely. No donor tissue. No animal-derived pericardium. Just synthetic polymer material processed through ion-beam technology. The pitch is straightforward. A material that resists adhesion, calcification, and infection while still supporting the body's own tissue repair after implantation. That combination sounds simple on a conference poster. In practice, achieving it at the molecular level is where most attempts fail. TamaBio claims to have solved this problem using technology originating from RIKEN. Whether the US surgical community sees the same solution is the real question hanging over every booth conversation. The gap between "available in Japan" and "deployed in US hospitals" is where most international medtech companies stall. TamaBio was founded in Tokyo in 2016. Its platform draws on specialized polymer-processing technology from RIKEN, Japan's national research and development agency. The company exhibits at ACS Clinical Congress Exhibit Hall from September 27 to 29. Two products anchor the showcase. DuraBeam, a synthetic dura mater substitute for neurosurgical procedures. PeriBeam, a synthetic pericardial membrane for cardiac surgery. Both products are built on the same ion-beam-processed ePTFE biomembrane platform. The platform has been used in thousands of surgical procedures. Japan's Ministry of Health, Labour and Welfare has granted Class IV manufacturing and marketing approval for both products. The Class IV designation under Japan's system is the highest medical device category. It is equivalent to implants requiring extensive safety data. In December 2025, TamaBio announced the FDA-listed PeriBeam had been exported to the US for clinical surgical use. It was manufactured at an FDA-registered establishment. The FDA listing for PeriBeam is not full FDA approval. It is a registration that enables export for clinical use. That distinction matters for US procurement strategy. The company holds foundational patents in Japan, the United States, China, and Taiwan. TamaBio is also developing artificial blood vessels and experimental sheets for nerve, brain, and spinal cord injury repair. It is collaborating with Tohoku University on neurological function recovery after brain contusion, spinal cord injury, and cerebral infarction. CEO Tetsuya Nagao is in Washington from September 25 to 30. He is available for media interviews, industry briefings, and partnership discussions. The company's stated goal is to bring Japanese medical innovation to more patients worldwide. These are not abstract ambitions. Every claim above traces to an approved regulatory filing, a manufacturing facility, or a signed research collaboration. The RIKEN technology transfer gives the platform a research pedigree that goes back to Japan's national laboratory system. The FDA-registered manufacturing site removes the "imported from overseas factory" objection that slows down US hospital adoption. The Tohoku University partnership extends the platform beyond commercial products into regenerative medicine. Each piece of evidence compounds the next. The technology on the demonstration table is the easy part. The real work happens off the exhibit floor. Nagao's availability for partnership discussions signals the actual goal. It is distribution partnerships. The FDA-listed status for PeriBeam removes regulatory friction for US import. Class IV approval in Japan provides clinical credibility that regulators recognize. Patents across four jurisdictions lock in intellectual property defensibility. But none of that matters without a US distribution network capable of reaching hospitals. The commercial loop is straightforward. Secure FDA listing. Demonstrate clinical use through export shipments. Build surgeon familiarity at major conferences like ACS. Then find a distribution partner capable of scaling across North America. The end-game is not a single-product launch. It is supply chain integration. Once US neurosurgeons and cardiac surgeons adopt a synthetic membrane into their standard operating protocols, switching costs climb steeply. Training protocols shift. Inventory logistics shift. Procurement contracts shift. Biological patch manufacturers have decades of established hospital relationships. Hospital purchasing committees rarely switch suppliers mid-cycle. A new entrant needs clinical trial data, surgeon endorsements, and procurement-friendly pricing. TamaBio has the clinical data from thousands of procedures in Japan. It has regulatory clearance. But US hospital procurement requires something else entirely. Local distribution. Local clinical support. Local accountability for product performance. Those are the conversations Nagao is in Washington to have. TamaBio is not selling a membrane. It is selling access to a category that biological patch manufacturers have occupied for decades. The incumbents in that space know this threat. Their response will determine the speed of any market entry. The question is whether Japanese manufacturing capacity can scale fast enough to meet US demand once distribution partners commit. The answer will not come from this conference. It will come from the next eighteen months of distribution deals, regulatory filings, and hospital procurement cycles. Watch the supply agreements more closely than the conference booths. Author bio: Oliver Hawthorne, a Principal Correspondent permanently stationed at an international technology review covering medtech supply chains and global regulatory market entry strategies.
More

LetPot’s Dual-Reservoir Tower Admits the Industry’s Dirty Secret, but Can It Actually Ship?

(SeaPRwire) - By: Ethan Gallagher Every indoor garden tells you the same lie. Plug it in. Follow the app. Watch green things appear. That fantasy died the moment someone tried growing tomatoes next to basil in a single tower. The nutrient profile one demands destroys what the other needs. LetPot just handed that contradiction to Kickstarter on October 1, 2026, at 11:00 a.m. Eastern Time, with a product called LPH-Home. It is the first mainstream consumer device to admit the problem existed. The company was founded in 2019 in Hong Kong, and this launch represents their boldest architectural bet since then. Two reservoirs do not just mean more growing space. They mean the entire product philosophy has been rebuilt around decoupling nutrient management from spatial constraints. The industry has spent years optimizing for the simplest user experience. That meant forcing every plant into the same chemical cocktail. LetPot is betting that households actually want variety. The technology to deliver it without overwhelming the user already exists. The release sheet is clean and specific. LPH-Home features two independent 6-liter reservoirs with separate EC monitoring. The upper tier supports taller crops like compact tomatoes and peppers, with adjustable growing heights. The lower tier is dedicated to frequently harvested herbs and leafy greens. Together they hold up to 32 plants. A built-in TFT touchscreen and the LetPot App manage lighting schedules and water circulation. Water-level and EC data appear on-screen with alerts when intervention is needed. The structure is warm bamboo-forward with integrated wiring, modular assembly, and removable casters. Each reservoir detaches from the electrical section for rinsing. The campaign runs on Kickstarter with Super Early Bird rewards for early followers. LetPot was founded in 2019 under the brand vision "Fresh Grows Here." The open growing system lets users pick their own seeds and compatible growing sponges. No mandatory seed subscription required. Nutrients remain under the grower's control rather than being added automatically. That is a small philosophical statement disguised as a feature description. Rex Lin, co-founder and marketing director, framed the product as answering a simple question. How can families grow more of the plants they love without adding more complexity to their homes? Here is what the spec sheet does not say. The dual-reservoir architecture means LetPot is not selling a garden. They are selling a decoupled nutrient management system disguised as a kitchen appliance. The 6-liter capacity per zone is calibrated for household consumption cycles, not commercial output. Two weeks of herb harvesting or four weeks of compact pepper growth fits that volume without daily nutrient refills. The bamboo-forward aesthetic is not decoration. It positions the product outside the neon-purple grow-light aesthetic that alienates non-grower household members. The modular, water-separable design addresses a hidden customer support liability. Traditional tower gardens generate returns over mold contamination and electrical short-circuiting. By making each reservoir independently removable, LetPot shifts cleaning to the user while sealing the electronics. The open growing system sidesteps subscription dependency entirely, which is a deliberate margin strategy. Users select their own seeds and compatible growing sponges. That means no revenue-sharing agreements with seed suppliers. Every dollar from the hardware sale stays on LetPot's books. The adjustable growing heights on the upper tier signal that the product scales with user skill. No tiered subscriptions gatekeep advanced growing. The separate EC monitoring per zone tracks nutrient concentration independently. That is genuinely useful for anyone who has tried balancing different crops in one shared water volume. The real gamble is on the production line. Two separate EC sensors mean two sensor PCBs. They also mean either two pumps or one pump with zone-switching valves. Firmware must maintain independent data streams. That doubles per-unit sensor cost relative to a single-reservoir design while lowering the customer's total cost of ownership. Every additional sensor board is a manufacturing yield point. Bamboo structure implies CNC-milled or laser-cut engineered wood substrate. That material introduces tolerances injection-molded plastic never produces. Quality control at scale becomes harder. Removable casters and modular reservoirs add fasteners and moving parts. Every fastener is a BOM line item. Every BOM line item is a bottleneck when production ramps from pilot runs to Kickstarter fulfillment volumes. The modular structure is designed to simplify assembly, movement, and routine maintenance according to the release. That is true at the household level. At the factory level, more parts mean more steps, more torque specifications, more QC checkpoints. The bamboo construction also introduces humidity sensitivity that plastic never faces. Coastal shipping containers add moisture exposure. The adjustable growing heights require mechanical adjustment mechanisms that need testing for durability across thousands of open-and-close cycles. The question is not whether LPH-Home works. It does. The question is whether LetPot can ship thousands of units with consistent EC sensor calibration and bamboo assembly tolerances. A field return wave before year one kills the brand. Author bio: Ethan Gallagher, a Silicon Valley Hardware Architect and Infrastructure Strategist with a focus on consumer IoT device design and supply-chain risk analysis.
More
Why 2,999 AI Projects Battled in Hangzhou and What the $145K Winner Reveals About Open-Source AI’s Real Future Business

Why 2,999 AI Projects Battled in Hangzhou and What the $145K Winner Reveals About Open-Source AI’s Real Future

(SeaPRwire) - By: Lucas Caldwell Hangzhou ate itself last week. Eight thousand plus developers, researchers, engineers, and founders converged on the Cloud Valley Center between September 22 and 23, 2026. They came for one thing. The Global Open-source AI Challenge Grand Finals. Not a keynote. Not a panel discussion. A fight. Seventy teams stood on stage. Six tracks. One question that hung over every demo: Can open-source AI actually ship something that works in the real world? The numbers behind that question tell the whole story before you even watch a single pitch. Over 14,000 developers from 91 countries submitted 2,999 valid projects since the competition launched in July. Seventy made it through preliminary rounds and semifinals to hang in front of judges from Tsinghua University, Alibaba Cloud Intelligence Group, the Agent AI Foundation, and bodies like the U.N. Global Goals Ambassador Lumbie Mlambo. The bar was brutally narrow. The筛选 rate from 2,999 to 70 was roughly two percent. That is not accidental. It is structural. The six champion teams did not win on buzzwords. ExpLoop Lab took the GOAI Grand Prize with MirrorPeptidizer, a de novo mirror peptide design algorithm. The team won 1 million RMB and a place in history. The project tackles real problems. Mirror peptide research traditionally requires expensive target protein preparation and small datasets. The algorithm lowers those barriers through computational design and validated its outputs through wet experiments. That is the difference between a demo that looks good in a conference hall and a tool that a lab will actually use next month. The other five champions covered Agent Infra with DataFlow-Agent intelligent data governance, Boundless Agents with the ZhiChain Agent for commercial aerospace mission verification, Algorithm sub-track with an MD Transformer using spatiotemporal PE encoding, the GOLION dual-arm collaboration project, and the Wisdom Patrol Lynx all-terrain inspection system. Every winner proved the same point. Here is the uncomfortable layer most press releases skip. Open source is no longer just about code sharing. It is about who controls the pipeline from model to deployment. The four tracks tell you everything. Agent Infra and Boundless Agents point toward agentic systems that interact with software environments. AI for Research signals a new frontier where open-source models accelerate scientific discovery. Embodied Future is the physical world interface, where algorithms meet robots, drones, and autonomous vehicles. The Hangzhou Open Source Artificial Intelligence Foundation, the Agentic AI Foundation, and the LF AI & Data Foundation structured this competition around those seams because that is where the money flows. That is where the next decade of compute demand will be spent. The supply chain reality is simple and it is shifting under everyone's feet. China built a massive open-source AI arena in Hangzhou. The partnerships with Alibaba Cloud, Ant Group, Zhejiang Lab, and the global backing from AAIF and LF AI show that the center of gravity is no longer exclusively Silicon Valley. If your next career move depends on which ecosystem owns the developer mindshare in 2027, stop watching the headlines. Watch where the winning projects in Hangzhou ship next year. Author bio: Lucas Caldwell, a tech opinion leader with millions of followers on X/Twitter, writes about open-source AI, hardware economics, and the people building them outside corporate PR.
More
When the Rain Exposed China’s Broken Apple Market: Inside the Price Index That Changes Everything Business

When the Rain Exposed China’s Broken Apple Market: Inside the Price Index That Changes Everything

(SeaPRwire) - By: Alisa Mercer The rain didn't just disrupt Yan'an's 2026 harvest. It exposed a pricing structure that was already structurally unsound. Three and a half million mu of apple orchards produced 5.28 million tons in the previous season. But persistent rainy weather during harvest disrupted picking schedules and fruit maturation cycles. The commercial yield rate of high-quality apples dropped noticeably. When quality supply contracted, the market revealed its true pricing behavior. Premium large-sized fruit held prices. Everything else collapsed. This isn't a weather story. This is a structural market failure story. The widening price gap between high-end premium fruits and ordinary bulk products wasn't a seasonal anomaly. It was a structural revelation. The market had never been pricing apples by quality before. Now it's being forced to. The Xinhua China (Yan'an) Apple Price Index was born out of this operational reality. Not from a white paper. Not from a policy memo. From verified transaction records sourced directly from local primary producing areas. Xinhua Index Academy built this index to continuously track and analyze dynamic price movements across different fruit diameters and quality grades throughout the entire sales cycle. This is a tool built from actual trading data, not theoretical models. The infrastructure supporting this index is worth examining closely. Yan'an has completed 211 intelligent apple sorting production lines. These achieve an efficient sorting capacity of 511 tons per hour. That throughput number matters because it means the post-harvest grading and processing system is standardized enough to generate reliable, categorized data for the index to monitor. The FAO recognizes Yan'an as one of the world's superior ecological zones for apple cultivation. But ecological advantage alone doesn't create market precision. You need the industrial backbone to translate field-level quality differences into price signals. The diversified multi-level local trading market plays a critical role here. It has accumulated abundant and comprehensive sampling data over time. This ensures the index monitoring results carry authenticity, comprehensiveness, and representativeness. When an index claims to reflect market dynamics, the depth of its sampling determines whether analysts will treat it as a credible reference or dismiss it as a partial view. The index monitoring network covers major apple-producing counties across Yan'an. It incorporates both on-site purchasing transactions and cold storage outbound trading links. This dual-coverage approach captures the full spectrum of market activity. From farm-gate buying to warehouse release points. The data reflects both high-end premium apples and mass-market bulk fruits. No single segment gets artificially inflated or suppressed in the monitoring results. Here's what the actual market performance data shows. Premium large-sized and high-quality apples maintained strong market resilience and stable prices amid industry-wide fluctuations. Meanwhile, medium and small-sized apples, as well as fruits with slight appearance defects, faced obvious downward price pressure. The divergence isn't subtle. Fruit size and comprehensive quality have become the core decisive factors for local apple market pricing. For commodity traders, this is textbook supply-demand repricing. When quality supply contracts due to weather, the premium for quality grades expands. The bulk market absorbs the volume but loses pricing power. The sorting infrastructure determines which fruits land in which category. At 511 tons per hour, the 211 sorting lines can process enormous volumes through standardized quality grading. This isn't manual inspection. This is automated precision sorting. The index resolves a long-standing problem for scattered individual farmers. Information asymmetry has been the defining structural disadvantage for small producers in commodity markets. When thousands of individual orchard owners each make pricing decisions based on fragmented, second-hand market intelligence, the result is chaos. Blind hoarding drives prices up artificially. Concentrated sell-offs crush them down. The publicly released index gives farmers a scientific basis for judging market trends. It's a direct counter to irrational market behavior. For the financial side, the impact is equally concrete. The local apple industry's "insurance plus futures" financial pilot project needed a fair and authoritative market benchmark. Without a verified price index, financial instruments like futures contracts have no reliable reference point for pricing. The index effectively strengthens industrial risk prevention and control capabilities. This isn't abstract risk management theory. This is operational hedging infrastructure. The commercial intent behind this index extends beyond price discovery. Xinhua Index Academy is transmitting accurate market demand signals directly to the production and processing ends. Local orchards and sorting enterprises can now adjust their planting and grading standards in line with actual market preferences. This promotes the implementation of a "quality-based pricing and premium quality for premium price" market mechanism. The signal flows from the trading floor back to the orchard. The index is positioned as a vital barometer and wind vane for high-quality development of the local apple industry. Barometers don't just measure atmospheric pressure. They signal which direction the storm is heading. The index is explicitly designed to guide producers away from volume-driven competition toward quality and efficiency orientation. It connects all key links including apple planting, warehousing, processing, and sales. The goal is to transform Yan'an's unique ecological and resource endowments into tangible market competitiveness. Looking at this through a commodity risk lens, the structural shift the index enables has clear parallels to what we see in industrial metals markets. When a commodity market transitions from volume logic to quality logic, the winners are operators who can consistently deliver high-grade product at scale. The losers are volume-focused producers who can't distinguish between tonnage and tonnage. The 211 sorting lines and their 511 tons per hour capacity represent the industrial infrastructure needed to make that distinction operational. The expansion plans are practical. Xinhua Index Academy will continue to optimize the index data collection network. Monitoring coverage will expand. Multi-dimensional monitoring indicators for segmented apple products will be enriched. These aren't vague aspirations. They're concrete operational improvements to an existing index system. But the ultimate test of this index isn't its methodology. It's adoption. A price index only delivers value when market participants trust and use it. The farmers need to see the data and change their selling behavior. The trading merchants need to adjust their sourcing strategies. The warehousing operators need to recalibrate their holding periods. The financial institutions need to integrate the index into their hedging products. Every link in the chain has to act. What the Xinhua Yan'an Apple Price Index actually delivers is a structural correction that the market needed but couldn't achieve organically. China's agricultural commodity markets operated for decades on volume logic. Bigger harvests meant better outcomes. The price gap data from this index proves that logic is obsolete. Market resilience now correlates with quality grading, not tonnage. The 511 tons per hour sorting capacity isn't just infrastructure. It's a competitive moat. The 3.32 million mu under production isn't a liability. It's a diversified risk position. The only remaining question is whether individual farmers and trading merchants can adopt the new pricing paradigm fast enough to survive the transition, or whether the market will do it for them through the painful mechanism of price collapse and forced consolidation. Author bio: Alisa Mercer, a commodity risk desk lead specializing in industrial metals logistics and agricultural price index strategy, with two decades of experience in global commodity market dynamics and supply chain risk management.
More

Nasdaq’s Ruling Reveals the Hidden Tax on Micro-Cap Digital Nomads

(SeaPRwire) -By: Ethan Gallagher The Panel’s decision to delist Platinum Analytics Cayman Limited strips away the polite fiction that a Cayman-domiciled shell with a Singaporean CEO can hide behind institutional credibility. Nasdaq rejected the appeal not merely because of low liquidity, but due to "trading activity indicative of potential manipulation." For an infrastructure architect, this is a critical warning. Exchange gatekeepers are no longer asking if you have a product. They are auditing the pattern of who touches your stock. When a firm’s advisors have histories with halts and FINRA enforcement, the panel sees a red flag. They dismissed the advisor link as insufficient alone, but combined with liquidity failure, it became fatal. The official release states the Staff Delisting Determination came under Nasdaq Listing Rule IM-5101-4. The company appealed, held a hearing on August 18, 2026, and lost. Trading halted on September 23, 2026. These are hard timestamps. The subtext is a liquidity crisis. The company failed to demonstrate a fair and orderly market. This is not a product failure. FX trading software for Asia is a viable niche. The issue is capital structure. The Cayman entity creates distance. The Singapore residence of the CEO was noted but dismissed as a non-issue. The market did not care where the boss lived. It cared that the float was thin and the volume was erratic. On one side, the release highlights their focus on emerging markets and support from the Monetary Authority of Singapore (MAS). They offer AI-driven, low-latency tools. This is solid tech. On the other side, the stock was suspended because of manipulation risks. Investors in these micro-caps are not buying the software. They are buying a story of rapid growth. When the story fails, the liquidity vanishes. The panel’s affirmation of the Staff determination signals that Nasdaq is tightening its noose on firms that cannot sustain a two-way market. The appeal to the Listing and Hearing Review Council is a procedural move, not a strategic one. It likely will not stay the delisting. The supply chain for trust in small-cap tech is broken. If you cannot prove clean order flow and deep institutional interest, you do not belong on Nasdaq. The delisting is the price of admission for operating with opacity. Firms in this lane must pivot to transparent, high-liquidity exchanges or accept the OTC market’s reality. The hardware is irrelevant if the paper cannot hold weight. Author bio: Ethan Gallagher, a Silicon Valley Hardware Architect and Infrastructure Strategist who specializes in analyzing the intersection of cloud infrastructure capital allocation and emerging market tech governance.
More
The Gilded Cage: Why a Pair of Thrones Signals the End of Mass-Produced Luxury Business

The Gilded Cage: Why a Pair of Thrones Signals the End of Mass-Produced Luxury

(SeaPRwire) - By: Robert Kensington Somerset House in London feels colder than ever. It is the kind of venue where cultural diplomacy replaces real commerce. Maintur Furniture chose the "Refine the Mind" section to display its Dragon and Phoenix Harmony Jiaoyi-style Thrones. This is not a casual choice. It signals a pivot from standard furniture exports to high-net-worth cultural capital. The PR angle focuses on "Reflection of the Mind." The reality is much sharper. This is a display of monopoly power in a niche that is shrinking. The official narrative highlights the 2026 "Reviving Craft" exhibition organized by Sun Media Group. It runs from September 16 to 27. The theme is "Reflection of the Mind." Maintur presents a pair of thrones carved from black walnut. They trace their prototype to a Qing imperial court piece. The craftsmanship follows Dongyang Wood Carving standards. These are national intangible heritage techniques. The piece uses high-relief and openwork carving. Artisans hand-applied genuine gold leaf. The bronze pivots are custom-made via traditional hand-chiselling. The marketing calls this a dialogue with contemporary life. The subtext is different. This is a barrier to entry. Look at the supply chain facts. Maintur was founded in 1998. It now holds three core segments. Mahogany furniture, solid wood fit-outs, and low-carbon wooden houses. They have served as strategic suppliers for seventeen top-tier events. That includes the G20 Hangzhou Summit and the BRICS Xiamen Summit. This track record is their moat. They are not competing on price. They are competing on provenance. The thrones represent the Ming and Qing dynasties. They embody "harmony between dragon and phoenix." This is not just decor. It is a status symbol for global elites. The production process avoids machine mass production. It relies on provincial-level masters. This creates a bottleneck. It limits scalability. The commercial intent is clear. The company is positioning itself as the guardian of authentic Eastern aesthetics. They are moving up the value chain. The global market for luxury interiors is saturated with Italian and Japanese design. Eastern heritage furniture is an underexploited sector. By linking their brand to G20 and BRICS credentials, they reduce buyer risk. They signal reliability to diplomatic and corporate buyers. This is a B2B play disguised as art. The endgame is a closed loop of high-margin, low-volume sales. They will likely expand into low-carbon wooden houses as a secondary revenue stream. This leverages their wood processing expertise. It keeps the cash flow steady while they chase the prestige label. Author bio: Robert Kensington, an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion.
More