


(SeaPRwire) – By: Robert Kensington
Most European dealers still won’t admit it out loud, but Chinese auto brands are quietly eating the continent’s market share. They’re not showing up with cheap, ugly cars anymore. They’re arriving with NEVs that outsell domestic rivals, and they’re doing it in markets that spent decades dismissing Beijing-made machines as toys for hobbyists.
OMODA & JAECOO’s September numbers prove the shift is already irreversible. The brand moved 73,421 units globally, up 123 percent year-on-year. Nearly three-quarters of those — 53,957 units — were new energy vehicles. That’s not a side hustle anymore. That’s the core business. And it’s accelerating faster than any traditional OEM in Europe has managed to respond.
The UK market tells the whole story. OMODA & JAECOO recorded 22,296 registrations in September, up 106 percent from last year. Market share hit 6.37 percent, ranking second among all automotive brands in the country that month. The JAECOO 7 alone accounted for 10,813 of those registrations and became the single best-selling model across the entire UK new-car market. Not the best-selling Chinese car. The best-selling car, period. Two models, JAECOO 5 and JAECOO 7, each pushed past 22,000 monthly sales. Together they’re reinforcing growth through sheer volume in the most discerning market in Europe.
The brand is now building a proper European R&D centre at UTAC Millbrook in Bedfordshire, focusing on chassis tuning and advanced driver-assistance systems. That’s not a sales office. That’s a signal that they intend to compete on engineering credibility, not just price. They’re trying to earn their place in these markets instead of renting it.
Spain delivered an all-time high 4.3 percent market share in September, with 4,010 registrations up 91.5 percent year-on-year. Electrified models represented 98 percent of total sales. The brand leads its C-SUV and D-SUV segments across the country. Italy added 4,678 registrations with a 3.31 percent share, ranking eleventh overall. Three models — OMODA 5, JAECOO 7, and OMODA 9 — all cracked the monthly top five within their respective SUV classes.
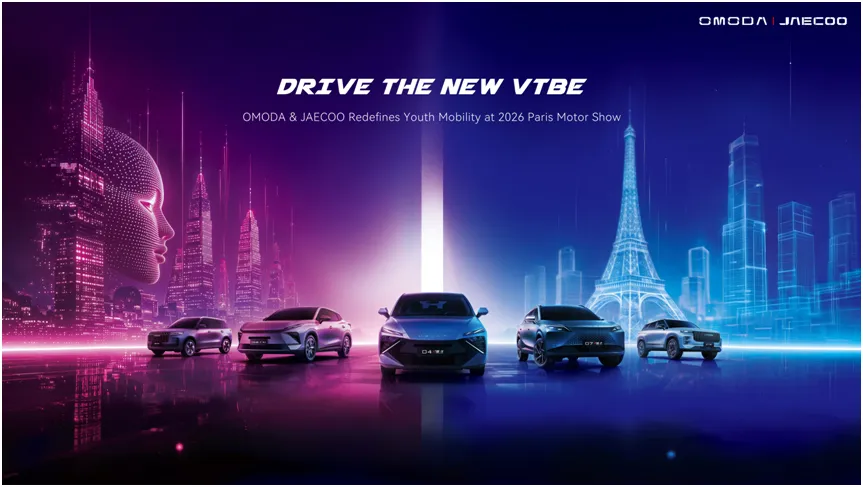
France is the most astonishing data point. JAECOO entered the market in April. Six months later, it captured 1.6 percent of French registrations with 2,589 units in September alone. Private customers made up 75.1 percent of the base. A publication called Journal de l’Automobile explicitly noted that no Chinese automotive brand had ever reached that kind of share in France in such a short timeframe. The brand will showcase OMODA 4, OMODA 5 NEXT, and OMODA 7 at the Paris Motor Show in October, cementing its push into a market that traditionally protected its domestic producers fiercely.
Cumulative sales for the first nine months of 2026 reached 587,846 units worldwide, just short of the 600,000 milestone. On current trajectory, they’ll clear it before year-end. The UK’s nine-month cumulative registrations stand at a strong position, and Spain has already passed 62,326 units year-to-date.
The OMODA X makes its global debut on October 20th under the tagline “MORE OMODA THAN EVER,” describing itself as a response to what the brand calls “CROSSVOLUTION.” The international user summit that month will also feature a super hybrid marathon and an intelligent experience lab showcasing next-generation cockpit and driving technologies.
The real question isn’t whether Chinese brands can sell cars in Europe. They clearly can. The question is whether European manufacturers will respond with meaningful platform investment or keep reacting to each monthly registration report with press releases about heritage and craftsmanship. The numbers don’t care about your legacy. They care about what reaches the driveway.
If OMODA & JAECOO maintains this pace through Q4 and the OMODA X resonates with mainstream European buyers, several German and French segment leaders will face genuine profit compression by early 2027. This isn’t speculation. It’s the math of 73 percent NEV share in a single month. The brands that treat this as a temporary spike will pay for that judgment call in shareholder meetings next spring.
Author bio: Robert Kensington is an overseas entrepreneurial veteran with decades of experience in real-economy industrial investment and expansion, specializing in global automotive market dynamics and emerging-market competitive strategy.